What happened: A Singapore court dismissed an insurer's bid to recover a $109,800 workplace death payout from the insured employer.
Who's involved: Etiqa Insurance (insurer/claimant) and Chye Joo Marine (ship repair employer/defendant).
What's at stake: $109,800 in statutory compensation already paid by the insurer.
Why it matters: "Reasonable precautions" clauses require insured recklessness, not just employee misconduct - even when someone dies.
Where it stands: Judgment delivered October 30, 2026; costs submissions due within 14 days.
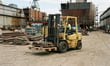
The forklift had faulty brakes. The operator wasn't certified to drive it. His supervisor knew both of those things and waved him on anyway.
What happened next killed a man.
Etiqa Insurance paid out $109,800 in statutory compensation for the workplace death and then sued the employer to get the money back. A Singapore district court has told the insurer it cannot recover a cent.
The case, decided on October 30, 2026, turned on two words buried deep in a standard employer's liability policy: "reasonable precautions."
Ship repair company Chye Joo Marine had sent a crew to a shipyard in May 2019 for grit-blasting and spray-painting work on a vessel. A supervisor on site allowed one of his crew - a grit-blaster who lacked the required forklift certification - to operate a forklift that both men knew had defective brakes.
The operator lost control. The forklift crashed through a guardrail, sending the machine and a blasting pot onto a slipway below. A colleague working underneath was struck and killed.
Both the supervisor and the operator were criminally charged and convicted under Singapore's Workplace Safety and Health Act for recklessly carrying out acts, without reasonable cause, that endangered the safety of others at work. The shipyard occupier - a separate company - was also convicted for failing to prevent unauthorised forklift use and ensure its equipment was properly maintained.
Chye Joo Marine itself was never charged.
Etiqa had issued Chye Joo Marine a work injury compensation policy, as required by Singapore law. After paying the $109,800 compensation assessed by the Commissioner for Labour, the insurer pointed to two conditions in the policy and demanded repayment.
The first required the employer to "take all reasonable precautions to prevent accidents and disease." The second required it to "comply with all statutory obligations and requirements."
The insurer's position was straightforward: a supervisor allowed an uncertified worker to drive a faulty forklift, someone died, two people were convicted - plainly the employer had not taken reasonable precautions.
The court applied a principle from a 1942 English case - Woolfall and Rimmer v Moyle - later reinforced by the English Court of Appeal and adopted by Singapore's own Court of Appeal. The rule: in an employer's liability policy, "reasonable precautions" does not mean the employer has to be perfect. It means the employer must not have been reckless.
That is a much higher bar. One employee's recklessness cannot be pinned on the employer simply because the employer is responsible for its staff. The court has to ask whether the employer itself recognised a danger and deliberately took no steps - or steps it knew were not good enough - to deal with it.
Here, Chye Joo Marine had appointed a supervisor who held the relevant qualifications, had completed a shipyard supervisor's safety course, and had worked in Singapore's marine industry since at least 2008. The company's own risk assessment forms had identified forklift hazards, rated the consequences as "major" or "catastrophic," and specified that only certified operators could drive them.
The court found no evidence that the employer knew, or had any reason to suspect, that its supervisor would let safety standards slide. Delegating to a qualified person was enough. That the supervisor then acted recklessly was his failure, not the company's.
On the second condition - compliance with statutory duties - the court was equally unmoved. The workers' convictions under one provision of the Act did not prove the employer had breached a different provision: the general duty to ensure workplace safety. And in what the court called an "odd" omission, the insurer's own closing legal submissions offered no argument at all on how the employer had actually broken that duty.
The claim was dismissed in full.
For liability insurers writing employer's cover, the decision is a pointed reminder that "reasonable precautions" conditions remain a narrow recovery tool - clawing back a payout requires proof that the employer itself was reckless, not merely that its people were, and hiring a qualified supervisor may be all the precaution the law demands.