The Insurance Council of Australia’s redrafted General Insurance Code of Practice would write key insurer commitments into retail policy contracts for the first time, giving policyholders a route to court alongside AFCA and the Code Governance Committee, and putting the wording of the policies brokers place at the centre of the change. Lodgement with ASIC has already slipped twice.
The ICA opened consultation on the draft on June 24, with submissions open until July 21. Pending ASIC approval, the Code would form part of retail consumer contracts, except the Principles and Section 10 on enforcement. Home and motor claims would be automatically accepted after 12 months where no decision has been made, subject to defined exceptions. The draft also proposes a circumstances-based definition of vulnerability with an accompanying Extra Care framework, broader family violence protections covering financial abuse and coercion, and enhanced expectations for trauma-informed claims handling. Insurance Business reported that the consultation drew 28 submissions.
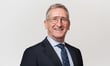
A legal commentary on the draft, published this week by Michael Bracken (pictured), principal at McCabes, says insurers would have to include a policy term requiring compliance, and that a breach would give policyholders the option of complaining to the insurer, the Code Governance Committee or AFCA, or taking court action for breach of contract.
The commentary notes limits. The Code terms would not be conditions or warranties of the policy, liability would exclude indirect or consequential loss and loss caused by the policyholder’s own failure to meet their obligations, and third-party beneficiaries would not gain enforcement rights.
The new remedies would supplement rather than replace rights under the Insurance Contracts Act, the ASIC Act and the Corporations Act, and most disputes are still likely to go through established complaint channels. PwC describes the change as adding legal exposure and reputational risk that did not exist before, similar to the Banking Code of Practice.
The commentary says the draft treats an insurer as in breach if its employees, distributors, service suppliers or claims fulfilment providers fail to comply when acting on its behalf. That principle already exists in the current Code, so what changes is that such conduct could now create contractual liability. PwC says insurers will need to oversee parties such as builders and motor repairers for that reason.
The commentary does not say how brokers acting for an insurer, such as under delegated claims authority, would be treated. The 2014 Code defined service suppliers to include a broker who manages claims on an insurer’s behalf, and a submission to the consultation that quotes the redraft’s definitions shows similar wording, again referring to a broker who manages claims for the insurer. How that language works with contractual enforcement is a question for the final text and for insurers’ delegation arrangements.
Bright Law’s summary of the draft, published on July 21, says it applies to all retail general insurance products, including home contents, building, car, pet and travel insurance, and to some small business commercial insurance. Small-business protections are contested. Insurance Business reported a rift between industry and consumer advocates over whether the redraft strengthens or dilutes existing protections, which bears on brokers with SME clients.
The ICA has pushed lodgement with ASIC to late October, the second time the schedule has slipped, citing the number and complexity of submissions and requests for more consultation time. Approval would follow under ASIC’s process, and only the Banking Code of Practice currently holds ASIC approval. The ICA anticipates a 24-month transition before commencement, so the contractual terms are unlikely to take effect before 2028 on the current timetable.
ASIC commissioner Alan Kirkland said at the ICA’s annual conference last October that a new Code enforceable by contract “is an important step towards rebuilding trust.”
During the transition, policy wordings are likely to carry a Code term, and the 12-month rule gives brokers a reference point in long-running home and motor claims. The industry reported 5.7 million lodged claims across 41.6 million policies in 2024-25. Insurers have yet to set out how Code obligations will pass down through delegated authority and claims-handling arrangements.