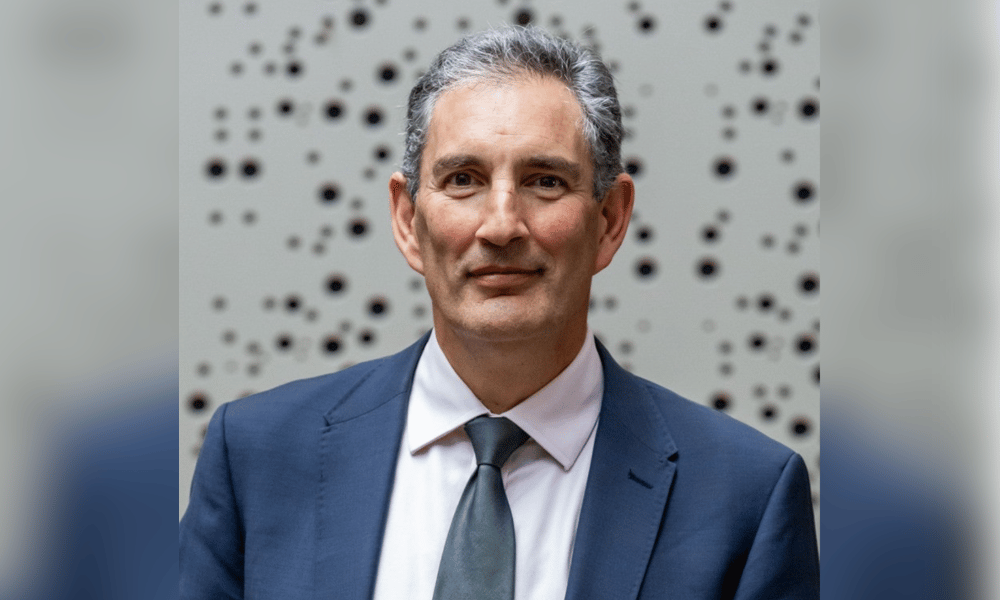
Asked how NIBA decided where to draw the line on fee transparency, the answer came back in a single word.
"Evidence," said Richard Klipin (pictured), CEO of the National Insurance Brokers Association (NIBA).
That one word carries the weight of an argument with regulators and consumer groups that ran most of 2026 and included the threat of mandatory regulation. The 2027 Insurance Brokers Code of Practice launched at the Gold Coast Convention gives any client the right to ask what their broker is paid and receive the answer in dollars, irrespective of client or product type. However, it stops short of requiring brokers to volunteer that figure unprompted, which is what the association's critics had demanded.
The reasoning is now on the record. NIBA published op-eds while the board was deciding, collected in a companion document to the Code called The Profession's Promise to Clients. The third, also published as an Insurance Business column, is headed A Code Built on Evidence, Not Instinct and it sets out the test the board applied.
On the question of extending disclosure further, NIBA's conclusion was blunt. Across two rounds of consultation, the document states, the argument for expansion was made in principle rather than from demonstrated client harm.
NIBA's case rests on client research and complaints data it published alongside the Code.
Its Complexity to Clarity research, which surveyed advised clients rather than direct buyers, found 84% trust their broker to act in their best interest, 91% say their broker helped them achieve a better outcome, and 95% consider their broker essential at claim time. The same research put successful claims resolution at 98%.
On complaints, NIBA reported that broker clients accounted for 686 complaints to the Australian Financial Complaints Authority in 2025-26, from roughly 117,000 the scheme received, which it calculated at under 0.6%.
Read next: Broker fee transparency fight moves outside the Code review
Klipin made a related argument about how much disclosure already exists. Documentation governing the relationship runs to multiple points, he said, with disclosure occurring when the relationship begins, when a recommendation is made and at invoicing. Put to him that at least one regulator would prefer a line-by-line breakdown of fee and commission, his response was flat.
"Which already happens," he said.
His argument against prescription rests on how differently the association's members operate.
"Some charge fee only, some take fee and commissions, some take commission only, some have full disclosure," Klipin said.
NIBA's published position is that the Code binds more than 14,000 brokers across around 380 firms, from sole practitioners to global multinationals, and that a single prescribed method cannot serve that range. The association framed the layers as law, licensing, Code and firm standards, with each firm deciding how it competes within the boundaries the Code sets.
Where the evidence pointed the other way, NIBA moved. Automatic remuneration disclosure now extends to all strata insurance, residential and commercial, disclosed to the owners corporation whether or not it is a retail client. NIBA identified strata as the clearest pressure point, citing findings from AFCA, the Insurance Brokers Code Compliance Committee (IBCCC) and state-based inquiries.
Read next: NIBA's new strata broker rules win over consumer groups
The IBCCC's strata review this year found none of the representative agreements it examined met the Code's requirements. It made nine breach determinations and referred three brokers to ASIC and NSW Fair Trading. NIBA acknowledged that finding directly in its own document and said being evidence-led meant following the evidence even when it pointed at the profession.
Those changes brought the three consumer groups that had withdrawn from consultation in July back on side. The Australian Consumers Insurance Lobby, the Owners Corporation Network and the Unit Owners Association of Queensland said the final Code addressed the concerns that prompted their exit.
Not everyone is satisfied. Insurance Business reported that IBCCC chair Oscar Shub told a federal inquiry into small business insurance the draft fell short because it did not require proactive commission disclosure to all individual and small business clients. ACIL took similar concerns to assistant treasurer Daniel Mulino in September 2026.
Klipin was unapologetic about who the Code is written for.
"Many other voices sit in that conversation, but at the core of it, it's the broker and the client relationship," he said.
The Code takes effect on January 1 2027, replacing the 2022 Code. Submissions on the revised draft closed on 7 August 2026 and NIBA reported 51 written submissions and more than 300 pieces of feedback on the draft, with 21 clauses changed between draft and final version.
Whether that settles the disclosure argument is another matter. The IBCCC's position has not changed and the federal inquiry has not gone away.