Australia’s travel insurance sector is moving to fill a distribution gap created by one of the biggest structural shifts in the market’s recent history – and the race to do so is not limited to one company.
From October 1, 2026, the Reserve Bank of Australia’s (RBA) interchange fee reforms cut the cap on domestic consumer credit card transactions from 0.8% to 0.3% – a reduction of more than 60%. The RBA estimates the change will reduce issuer interchange revenue by approximately $660 million per year, according to its March 31, 2026, Conclusions Paper.
All four major Australian banks have responded with benefit reductions. NAB removed international and domestic travel insurance and rental vehicle excess cover from six cards from May 15, 2026. Commonwealth Bank stripped insurance from several products from September 29. Westpac removed trip cancellation, travel delay, and luggage cover from October 1. ANZ’s changes take effect in stages from December 9, 2026.
Canstar data insights director Sally Tindall, speaking to ABC, said the banks were not prepared to absorb the revenue loss. “They’re looking to recoup at least some of that loss … the consumer, in many cases, will end up paying for part of this ban at the minimum,” Tindall said.
The 2024 Insurance Council of Australia (ICA) and Department of Foreign Affairs and Trade Travel (DFAT) Insurance Survey – a nationally representative study of 1,007 Australian overseas travellers – found 25% of insured travellers cited credit card or employer arrangements as a reason they held cover for their most recent overseas trip. The Australian travel insurance market was valued at approximately $1.4 billion in annual revenue in 2026, according to IBISWorld.
Read next: Allianz taps AIG veteran to lead global captive solutions business
Multiple insurers and distributors are moving to capture the distribution space those changes are opening up – through configurable, digitally delivered embedded products that do not depend on bank card economics.
Allianz Partners announced September 28, 2026, the launch of its Metaportal platform, a digital tool for banking and loyalty program operators that allows customers to activate and manage cover online, with optional add-ons across cruise, snow sports, adventure travel, cancellation limits, and excess levels. Partners can configure benefit tiers at a segment level.
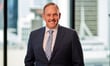
Damien Arthur (pictured), executive head of travel at Allianz Partners Australia, said the existing model had run its course. “For many years, travel insurance attached to financial products has largely operated as a one-size-fits-all proposition. Customer expectations have evolved. Today’s travellers want cover that reflects how, where, and why they travel, while businesses want solutions that build stronger customer relationships and support long-term loyalty,” he said.
Allianz Partners is not alone in this space. Zurich Cover-More – formed through Zurich’s 2017 acquisition of Cover-More and its subsequent integration with AIG’s Travel Guard business – publicly describes its business-to-business-to-consumer capability as spanning embedded propositions, white label distribution, non-additional-charge (NAC) programs, and agent platforms. The company states it has more than 200 distribution partners globally and covers more than 20 million travellers annually.
Both companies are competing for relationships with the institutional partners – banks, loyalty programs, airlines, and travel operators – that form the non-broker end of travel insurance distribution in Australia.
The appetite for embedded distribution reflects a longer-term structural forecast. PwC Australia projects that embedded insurance will account for $35 billion, or 18% of the total Australian insurance market, by 2033 – growing at an estimated compound annual growth rate of 34% between 2024 and 2033, compared with 4% for traditional insurance channels over the same period.
That forecast predates the RBA reforms. The interchange changes add near-term pressure to the structural long-term trend, accelerating the need for insurers to develop distribution infrastructure that does not rely on bank card funding models.
Read next: Allianz, Strata Community Insurance extend exclusive strata partnership to 2036 amid broker scrutiny
Neither Allianz Partners nor Zurich Cover-More’s embedded platforms are broker-facing products. But the conditions reshaping embedded distribution carry a direct implication for the advice channel.
The National Insurance Brokers Association (NIBA) flagged in a September 9, 2026, practice note that commercial credit cards retain the 0.80% interchange cap that consumer cards are leaving behind. For brokers with corporate clients paying premiums on commercial cards – and holding corporate travel programmes backed by those same card benefits – the interchange cuts do not offset the surcharging loss the way they do for consumer card arrangements.
More immediately: corporate clients who have relied on credit card benefits as background cover for employee travel now hold terms that have changed without their active involvement. Benefits differ by card product, effective date, and activation requirement. A cardholder who misses a minimum spend threshold does not hold the cover their card nominally provides.
For brokers managing corporate or group travel accounts, the current bank changes are a concrete, externally generated prompt to initiate a coverage review – and to make the case for standalone annual policies that do not carry the funding and activation dependencies card cover does.
The Allianz Partners and Zurich Cover-More announcements confirm that the embedded channel is adapting rather than retreating. For brokers, the more immediate question is which of their clients are carrying coverage gaps they have not yet identified.