Across roughly 60,000 sites worldwide, FM says between 30% and 40% of its gross loss dollars come from about 1,000 locations and that the same concentration repeats year after year. The mutual says it can name those locations in advance.
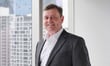
Andrew Stafford (pictured), FM's operations senior vice president and operations manager for Australia and New Zealand, said identifying those locations is what lets the commercial property mutual tell a client where to put money.
“This location is where we think the loss is going to occur,” said Sydney-based Stafford.
The finding lands in a market moving the other way. Global commercial property insurance rates fell 10% in the third quarter of 2026, the ninth consecutive quarter of decline across the commercial market, according to Marsh's latest Global Insurance Market Index. In the Pacific region the fall was 14%.
Marsh, which compiles the index from its own renewal data, also recorded what buyers did with the saving. John Donnelly, president of global placement at Marsh Risk, said many were “more inclined to retain premium savings rather than reinvesting them in additional coverage”.
One day after Marsh published, FM announced an estimated US$855 million resilience credit for 2027, a 10% premium offset for the second consecutive year, which it attributed to clients' risk reduction work and historically low losses. It followed with a separate US$1.5 billion membership credit in April 2026.
Read next: Why the simplest alternative risk transfer programs often win
The resilience credit supports action on FM's engineering recommendations, so what it is worth to a client depends on what the client does with it. FM CEO Malcolm Roberts said the mutual model lets the insurer support further improvement when clients invest in loss prevention, “creating a powerful circle of resilience”.
Stafford joined FM as a field engineer three decades ago.
“That mantra of the majority of loss is preventable was ingrained in us from that point,” he said.
The claim rests on volume. He said FM engineers make about 60,000 site visits a year, gathering an average of 600 data points on each one, set against 180 years of loss history: construction materials, occupancy, finished floor elevation, how equipment is maintained.
“It's data that you can't collect by a computer,” he said.
Those inputs feed a benchmarking tool FM calls RiskMark, which Stafford said the insurer has used for more than 20 years and which sorts every location into quartiles. By FM's own analysis, locations ranked in Quartile 4 are seven times more likely to suffer a loss, and when they do, the loss is 30 times more severe than one in Quartile 1. The Quartile 4 example Stafford gave was a building with no sprinkler protection, made from combustible construction.
Stafford said clients use the ranking to work out where to invest across a portfolio of assets, which is the same question the concentration finding answers from the loss side.
The ability to name the 1,000 locations in advance is newer. Stafford said it began to emerge about a decade ago, as the benchmarking was overlaid with analytics and the loss history, and has improved since.
The harder part is not the engineering. It is that spending on mitigation competes against a product that already exists to absorb the loss, and this year that product is cheaper. Marsh found most buyers kept the saving rather than spending it, which is the position a broker meets at renewal.
Read next: Reinsurance still built for the big one as secondary perils drive most catastrophe losses: Marsh Re
Stafford said that gap is larger than some clients imagine. Field engineers traditionally examined damage to property and interruption to business, which he called the tip of the iceberg. The exposures outside it are lost market share, the cost of capital and reputational damage.
“That’s not what the traditional insurance product responds to,” he said.
Stafford’s answer is to stretch the timeframe until the comparison changes, treating a site as an asset with a 20, 30 or 40-year investment life rather than a risk assessed once.
“We’re really trying to look at, let’s say, risk over the life of a building,” he said.