Few brokerages are five years old and already being shopped to private equity. Fewer still have owners who settle on an $82.5 million harbourfront estate in the same season.
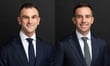
John Angelis (pictured right) and Yianni Gourlas (pictured left), school friends from Scots College who now run Clearlake Insurance Brokers as co-chief executives, settled on 14 Tivoli Avenue, Rose Bay, on 30 October. They agreed to buy the estate in October 2025, and the settlement period ran about a year. When they signed, it was the highest price ever agreed for a Rose Bay house. In December, a nearby Bayview Hill Road home sold to Birkenstock heir Alex Birkenstock for $83.5 million and took the record.
The house comes with three residences, harbour views across to the Opera House and a boathouse. The business that paid for it is more interesting to brokers.
Clearlake was registered in 2021. The two founders, both now in their early thirties, each own half of it, according to ASIC records. In its early years it operated inside the Coverforce Partners network, which Steadfast owns, and it became the network’s largest member.
In 2024 the founders took it independent. Clearlake rebranded, secured its own financial services licence and set out on its own. At that point it had a team of about 20 and was managing a little over $120 million in premium.
What followed was rapid. Buying Logan Insurance Brokers, an SME specialist, in mid-2025 pushed gross written premium (GWP) above $200 million. In June 2026, Clearlake bought the broking portfolio of WEB Financial & Insurance Services and said the deal took GWP past $300 million a year.
“We’re excited about what this means for Clearlake’s trajectory,” Gourlas said at the time.
The company’s figures show that premium has grown about two and a half times in about two years. Clearlake now describes itself as Australia’s largest privately owned insurance brokerage.
Read next: More premium, fewer brokers: inside Australia’s intermediary shift
The growth isn’t concentrated in one niche. Clearlake’s client base reportedly runs from strata and property owners’ cover through machinery, cargo, professional indemnity, directors’ and officers’ liability and workers’ compensation. It also reportedly has access to more than 100 insurers, including Lloyd’s, Chubb and Zurich.
A broad commercial book with deep market access is the kind of recurring, diversified income that has drawn private capital into Australian broking for a decade. It’s also what lets a broker keep acquiring, because every book it buys can be placed through a wider panel of insurers.
By August, reported figures put Clearlake’s annual revenue at about $45 million, with GWP of more than $250 million. That GWP figure is lower than the company’s own June number, possibly because the two were measured at different points. Either way, the business has gone from a network member to a stand-alone mid-market player in about two years.
The clearest sign of that success came in August. Clearlake mandated Barrenjoey Capital Partners to explore strategic options, including bringing in a private equity firm as a minority partner. Barrenjoey’s bankers have since been gauging interest among PE investors.
A minority raise lets founders bring in capital for more acquisitions without giving up control. For a business that has grown mostly by buying other brokers, it’s a natural next step.
The process won’t be a formality. Some firms approached have reportedly questioned the brokerage’s margins. That’s not unusual for a broker that has absorbed two sizeable books in a year, because integration costs tend to show up before the acquired premium fully pays off. But margins will be central to the price. Clearlake declined to comment on the process.
Read next: Steadfast extends exclusivity as $7.7 billion takeover bid advances
John Angelis has grown up around this industry. His father, Jim Angelis, built Coverforce into a large private broker and sold it to Steadfast for $411.5 million in 2021. That same year he bought 12 Tivoli Avenue, the waterfront property next door to his son’s new home, for $45 million.
The financing of the younger pair’s purchase hasn’t been disclosed. What is on the record is the business they’ve built, and their timing.
Private capital is paying heavily for Australian distribution right now. Steadfast signed a scheme implementation deed in August with a consortium of Amwins, Dragoneer and KKR, at $6.00 cash a share. The deal implies an enterprise value of about $7.7 billion and a 51.9% premium to the undisturbed share price. The independent expert has found the scheme to be in shareholders’ best interests, and the scheme meeting is set for 27 November.
That deal sits within a wider surge of M&A across the sector, with consolidation now reaching well into distribution. Clearlake has grown to the size where it can either keep consolidating or become a target itself.
Read next: Broker poaching wars: why Australia won’t follow the US to court
A minority investor in a founder-led broker is backing the founders as much as the client book. In Clearlake’s case, that’s the main selling point. The two have shown they can grow premium organically, close acquisitions and run the business as equal partners.
Even so, any incoming investor will look closely at a few things. With a 50/50 split, the shareholder agreement needs clear rules for what happens if the founders ever disagree. Retaining the producers who came across with Logan and WEB will matter, as will how much the book depends on the founders’ own relationships. Investors will also want a clear distribution policy once an outside shareholder is on the register. These are standard terms in any founder-led deal, and they’ll shape the valuation.
Barrenjoey’s process will give Clearlake something it hasn’t had before: a price set by an outside investor. If a partner signs on at a valuation that supports the founders’ acquisition plans, it will confirm how much value they’ve built in five years. The Rose Bay settlement would then read as a confident move by two owners who backed their own business early.
For mid-sized private brokers watching from the sidelines, the result will also be a useful benchmark for what founder-built scale is worth in this market.