WFI Insurance recorded 73 haystack fire claims in its most recent financial year. Its five-year annual average sits at approximately 30 – a 143% rise in a single season.
Individual losses ranged from thousands to hundreds of thousands of dollars. Total haystack fire payouts have exceeded $7 million across the five-year period.
These are self-reported figures from one insurer’s rural book, not industry-wide data. They arrived before this El Niño reached its projected peak, and before a spring season that three independent bodies have flagged as carrying above-average fire risk.
The Australasian Fire and Emergency Services Authorities Council (AFAC) released its Spring 2026 Seasonal Bushfire Outlook on August 19, identifying heightened fire risk across northern and southeastern NSW, southeast Queensland, northeastern Tasmania, parts of WA, SA, and Victoria, and large parts of the NT.
AFAC CEO Rob Webb said the outlook “highlights a heightened risk of fire across several parts of the country, driven by a combination of dry conditions in the east and increased fuel loads through parts of central and northern Australia.”
Bureau of Meteorology (BOM) data supports this picture. The Southern Oscillation Index (SOI) remains strongly negative, while BOM’s models forecast the tropical Pacific to continue warming through spring, likely peaking in late spring or summer, with this El Niño event expected to persist into autumn 2027.
WFI meteorologist Peter Chan said the heat and dry conditions are already compressing harvesting windows. “There is elevated risk of bushfires in Queensland and Northern NSW through to November. Initially the highest risk area is on the plateau west of the ranges in both states, with vegetation further drying out after the dry winter. Low-rainfall thunderstorms are also expected through the second half of spring which can be an ignition source for fires from dry lightning,” Chan said.
Read next: The strongest El Niño in recorded history is building. Insurers are already paying the price
The Insurance Council of Australia’s (ICA) Catastrophe Resilience Report 2025-26 found bushfire carries the highest average claim cost of any peril at $114,888 – more than double the next highest. The ICA also noted that bushfire impacts on the agriculture sector are expected to grow as conditions become hotter and drier.
Victoria’s January 2026 fires – the state's worst since the 2019-20 Black Summer – generated $599 million in insured losses across 4,852 claims, at an average of $123,378 per claim. Commercial lines carried a significant share of those losses, driven largely by primary producers and small businesses.
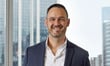
WFI executive general manager Damien Gallagher (pictured) described conditions on the ground as compounding the seasonal risk. “Crops are surging above the fenceline in some areas, roadside vegetation is high, stubble is dense, and natural firebreaks are reduced,” he said.
Harvesting machinery is a specific ignition source under sustained heat. Bearings and belts under thermal stress, combined with the accumulation of crop debris – chaff, straw, and dust – on equipment, create a recognised fire pathway. The Country Fire Authority (CFA) advises that haystacks be limited in size, stored away from machinery in well-ventilated areas, and monitored regularly for signs of heating.
On the coverage side, farm pack policies are modular. Machinery damage caused by fire typically falls under the farm property section, while machinery breakdown sits under a separate optional section that must be specifically selected. Equipment added, upgraded, or replaced since the last renewal but not listed on the schedule will not respond at claim time. Nutrien Ag Solutions, which arranges farm insurance for Australian primary producers, lists farm motor, machinery, buildings, and liability as distinct coverage categories – each requiring its own schedule entry.
Read next: Record El Niño arrives as reinsurance pricing hits cycle lows
The Australian Prudential Regulation Authority’s (APRA) Mind the Gap Insurance Climate Vulnerability Assessment (CVA), released in March 2026, found approximately one in seven Australian houses are currently uninsured. Under both modelled climate scenarios, that figure could reach one in four by 2050. APRA found that regional and rural communities would be disproportionately affected, with the protection gap widening more sharply where coverage levels are already low.
The ICA’s 2025-26 report found building costs rose approximately 30% between 2021 and 2026, outpacing CPI growth of around 24% over the same period. For rural properties – where rebuilds involve remote access, specialist trades, and compliance with current building standards – the gap between declared and real replacement values tends to be wider than national figures suggest.
Common shortfalls on farm policies include stored commodity values set against outdated prices, building sums that predate recent construction cost increases, machinery schedules not updated after equipment changes, and seasonal production peaks not captured in the sum insured.
A haystack loss in the hundreds of thousands of dollars – within the range WFI’s own claims history shows – can land against a sum insured set when commodity values and rebuild costs were materially lower.
Every available independent measure points to 2026 as a significant fire year. Farm policy schedules that have not been reviewed against current asset values and replacement costs carry a gap this season has a reasonable chance of finding.