More than three million Australians are using AI tools to manage their finances. Most of them will not act on what those tools recommend.
That distinction is the most commercially useful finding in a new national study for life insurance brokers – and it arrives as qualified advisers are in shorter supply than at any point in the past decade.
The Understanding Modern Australia report, released September 15 by life insurer TAL and social research firm McCrindle, surveyed 2,005 Australians aged 18 to 80 in late April and early May 2026. It also draws on four generational focus groups and nine financial adviser interviews.
Read next: TAL data confirms mental health as life insurance’s defining claims problem
When asked how likely they are to act on financial guidance, 42% of respondents said they are extremely or very likely to follow a paid, in-person financial adviser. For AI platforms, that figure falls to 18% – below family members (33%), reputable finance authors (31%), and online resources from financial organisations (25%).
Trust levels reflect the same pattern. Qualified financial advisers score 56% for high or very high trust. AI scores 33%.
The generational split matters for client segmentation. Gen Z respondents are 8.4 times more likely than Baby Boomers to use AI for financial management (25% vs. 3%). Even so, 42% of all respondents – across every age group – strongly or somewhat disagree that they feel comfortable using AI for major financial decisions.
Hood Sweeney director and life insurance specialist Mark Mullins, who leads an AI working group, said clients who self-research with AI tend to engage more substantively with professional advice. “We love it when clients use AI to inform themselves to ask questions and test the advice that we’re putting forward to them, because in the end they will see more value in the advice we provide, and that should strengthen our relationship,” Mullins said.
The report finds 57% of Australians are comfortable with their adviser using AI tools to inform advice. But 87% want to know when AI has been involved in producing it.
That figure now carries regulatory weight. The Australian Securities and Investments Commission (ASIC) has confirmed that existing licensee obligations – including the best interests duty – apply in full to AI-assisted advice, regardless of which tool produced the output.
Separately, the Office of the Australian Information Commissioner (OAIC) has confirmed that from December 10, 2026, the Privacy Act will require businesses to disclose in their privacy policies when personal information is used in automated decision-making that could significantly affect a client’s rights or interests.
For brokers using AI to assist with advice documentation, that deadline means disclosure processes need to be in place before year end. The 87% client expectation and the incoming regulatory requirement are pointing the same direction.
The trust premium attached to qualified advisers matters more as their numbers fall.
According to the Financial Advice Association of Australia (FAAA), licensed adviser numbers have dropped from around 29,000 at the start of 2019 to 15,127 as at March 2026 – a decline of nearly 48% in under eight years. Only 464 new advisers entered the profession in 2025. The FAAA has described the shortfall as structural, driven by regulatory reform exits, retirements, and a new entrant pipeline that is not keeping pace with demand.
For those who remain, the TAL-McCrindle data points to a client base that arrives better informed than ever – and still turns to professionals when decisions need to be made.
The report introduces the Modern Australia Confidence Index (MACI), which tracks the gap between what Australians say they value and what their actual behaviours reflect – the distance between aspiration and action. Each of five pillars is scored from 0 to 100. The overall 2026 score is 70.
Australians who hold life insurance score 76 on the MACI. Those without cover score 68. The gap is widest in the Financial Wellbeing pillar, where insured respondents record an action score of 71 against 56 for those without cover.
Only 32% of survey respondents said they hold life insurance, though the report notes this is likely an undercount given how many Australians carry default super cover without knowing it. Industry estimates suggest around 3.4 million Australians are underinsured for income protection insurance.
On motivation, the top two reasons for taking out or considering life insurance were protecting family (46%) and peace of mind (44%). Debt did not feature in the top two – a shift from the framing the industry has historically led with.
Read next: Mental health claims are reshaping life insurance – and advisers are on notice
NAB’s Consumer Stress Index reached 59.1 in the March 2026 quarter – the highest reading since 2014 – driven by rising costs across groceries, utilities, rent, and mortgages.
The TAL-McCrindle data reflects that pressure. Despite 86% of respondents saying they regularly monitor their spending and 80% prioritising budgeting or financial planning, only 28% reported satisfaction with their finances. Some 62% feel stressed when thinking about money.
Financial Wellbeing recorded the largest aspiration-to-action gap of the five MACI pillars at 18 percentage points – wider than the gaps recorded in health, digital life, social connection, and civic engagement.
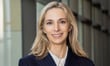
TAL group CEO and managing director Fiona Macgregor (pictured) said the findings mark a shift in what clients need from the advice relationship. “The Understanding Modern Australia report shows the rise of the hyper-informed DIY generation is reshaping the advice profession. As a result, advisers are evolving from information providers to trusted partners who help clients navigate complexity, apply judgement, and build the confidence to act,” Macgregor said.
McCrindle founder Mark McCrindle said the volume of available information has become part of the problem clients bring through the door. “Technology has fundamentally changed how Australians access information, make decisions, and seek advice. As information becomes more accessible, we’re seeing a generation of consumers who are more self-directed and more willing to do their own research than ever before,” McCrindle said.
The MACI is designed as an annual benchmark, with TAL and McCrindle committing to track shifts across the five pillars each year.