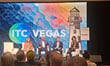
A dented bumper can be made to look like a write-off in seconds. A hospital invoice can be produced from nothing. And a stranger can lodge a claim on someone else's policy without the real policyholder ever knowing. That is the reality claims teams are now dealing with, according to a fraud panel joined by Insurance Business at InsureTech Connect in Las Vegas last week.
Jeremy Jawish, chief executive and co-founder of fraud-detection firm Shift Technology, told the session that insurers were seeing a sharp rise in AI-assisted fraud, from fake photos and fabricated accounts of events through to manufactured testimony, as Insurance Business US reported from the conference. Alina Wilkinson, a vice president overseeing claims processing at Liberty Mutual, said identity fraud alone was costing carriers hundreds of thousands of dollars per incident, with criminals filing claims in the names of people who never held a policy.
It would be easy to file this under "American problem". That would be a mistake. Shift is the same company the Insurance Council of Australia (ICA) chose last year to help build a national fraud-detection platform, and local insurers are reporting the same pattern turning up in their own claims queues.
Gallagher Bassett's 2026 claims study, which surveyed 250 insurance leaders across Australia, North America and the UK, found 72% of Australian respondents had seen an increase in fraudulent or suspicious claims involving AI-generated documents, with premium affordability now the sector's biggest worry. In Gallagher Bassett's own summary of the findings, 62% of Australian carriers said technology-enabled fraud and AI manipulation were adding significantly to cost pressures, and 70% were turning to AI and digital tools to fight back.
The bill was hefty before generative AI arrived. ICA members detected $560 million of opportunistic fraud in motor and property claims in 2023, and the council puts the cost of fraud that slips through undetected at roughly $400 million a year, according to the ICA. The ICA says those undetected cases push up premiums for honest customers.
Australia also catches far less fraud than it could. Detection rates here sit at roughly 1% of claims, against about 5% in the UK, according to industry estimates discussed at a Sydney claims summit in May.
The ICA saw this coming. In its submission to the Senate inquiry into AI, the council warned that generative tools could be used to touch up photos to inflate claims, and to support voice spoofing, phishing and synthetic identity fraud.
Read next: Australian insurers call for flexibility in fight against rising scam threats
Part of the problem is that faking a claim no longer feels like fraud to many people. Verisk's State of Insurance Fraud study, published in March and based on surveys of 1,000 US consumers and 300 claims professionals, found 36% of consumers would consider digitally altering a claim photo or document even if it broke the insurer's rules. Among Gen Z the figure was 55%, falling to 49% for millennials, 28% for Gen X and 12% for baby boomers.
Insurers were close to unanimous: 98% said AI editing tools were driving an increase in digital fraud. More than half believed that at least half of the policyholders who tweak their claim images don't realise it could count as fraud. There's no equivalent Australian survey yet, but there's little reason to think younger Australians, raised on the same filters and apps, would answer very differently.
The ITC panellists agreed that technology alone won't settle it, because fraudsters can use the same AI as the carriers, a dynamic Verisk has previously described as an arms race for insurers. Cain Hayes, a former health insurance chief executive, argued that if everyone has the same tools, the winners will be decided by the quality of their data, their operating model and their people. Wilkinson put it in kitchen terms: "Everybody has an oven. But it's the recipes and the cooks in the kitchen" that make the difference.
Read next: ICA report – how AI redefines insurance risk and operations
Australia's response has been to stop insurers fighting fraud alone. In November 2025 the ICA, EXL and Shift Technology announced they would build a national fraud detection and investigations platform with the Insurance Crime Intelligence Network of Australia (ICINA), the ICA's counter-fraud and scams division. Insurers will share fraud patterns and coordinate investigations, starting with motor claims, and the build was slated to begin in early 2026. It follows similar association-led schemes in the UK, France, Canada, Hong Kong and Singapore, many of them built on Shift's technology.
ICINA is led by Andrew Gill, who spent 24 years as a detective in the NSW Police fraud and cybercrime squad before the ICA appointed him to head its new counter-fraud unit. At the Claims Leaders Summit in Sydney in May, Gill said cooperation between insurers had increased dramatically, uncovering tens of millions of dollars in fraud. A shared analytics product is now spreading from motor into pet, travel and home contents.
Gill has also warned against assuming every fraudster is a tech wizard. He described Australia's organised criminals as "very organised but not particularly sophisticated", recycling the same vehicles, damage photos and injury claims across insurers; once records were pieced together, one claimant's house had apparently been struck by lightning 41 times.
Generative AI makes that recycling cheaper and more convincing, which is why a system that can spot the same fake turning up at several insurers matters more than ever.
The Las Vegas panel pointed to a second shift: moving from chasing suspicious claims after the fact to catching them early. Wilkinson said the carriers making most headway were joining up claims and underwriting, two teams that have traditionally worked apart, and that Liberty Mutual had begun loading its standard operating procedures into AI agents so investigators reach the right files sooner. Jawish said Shift now works with insurers in more than 20 countries, and that adoption is split between carriers going all-in on AI and those that freeze.
Read next: Fake Google claims number leads to vehicle ransom scam
For brokers, the fallout will affect us in two places: price and paperwork. Fraud losses, and the money insurers spend detecting them, feed into premiums, so honest clients carry part of the cost.
Clients should also expect more friction when they lodge a claim. That could mean identity checks at first notice of loss, requests for original photo files rather than screenshots, and more claims evidence captured through insurer apps. Legitimate claims may take a little longer while that screening bites.
The practical advice is simple and worth giving before a loss, not after. Tell clients not to edit claim photos at all, not even to brighten or crop them, and to keep the originals. A harmless tweak can now look exactly like the start of a fraud investigation.
It's also worth reminding them to ring their insurer on the number in their policy documents rather than one found online. WA's Consumer Protection agency has warned that crash victims searching for their insurer have been routed to rogue operators who tow vehicles and hold them until fees are paid.
Wilkinson described the fight against AI fraud as a treadmill that never stops. Brokers who understand how their insurer partners are running on it will be better placed to keep genuine claims moving.