The insurance industry is facing a fraud threat unlike any it has previously confronted. Artificial intelligence is arming bad actors with tools to fabricate claims at scale – forged images, invented narratives, synthetic testimony – and carriers are only beginning to understand how to fight back.
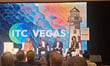
That was the consensus from a panel at InsureTech Connect (ITC) Vegas 2026, held at Mandalay Bay in Las Vegas, today. The panelists, pictured above, were Jeremy Jawish, CEO and co-founder of Shift Technology; Cain Hayes, former CEO of Blue Ridge, who has extensive experience in health insurance; and Alina Wilkinson, vice president of claims processing, medical, and quality of service at Liberty Mutual. Together they mapped the scale of the problem and the industry's response.
"We're seeing an enormous spike in fraud using AI in insurance," Jawish said. "We're seeing it on fake pictures, fake narratives, even fake testimony across the claim. It became so easy to generate things that are not real and that look super real."
Hayes highlighted the financial stakes. "If you think about the healthcare industry, there is $4.5 trillion of spend approximately in the U.S. One-third of that is fraud, waste, and abuse," he said. Official data now put the figure higher: the Centers for Medicare & Medicaid Services (CMS) reports that national health expenditure in the United States reached $5.3 trillion in 2024. "AI has made it easier for bad actors to create fake identities, fake documents," Hayes said. "It's a bit of an arms race."
Identity theft is already costing carriers hundreds of thousands of dollars per incident, Wilkinson said, a pattern that mirrors how AI is making health insurance fraud faster and harder to detect. Fraudsters are impersonating real policyholders and filing claims under stolen identities without the victim ever knowing. "Before you know it, we've paid hundreds of thousands of dollars to folks that really never even had our policy," she said. Insurers are tracking known bad actors through data shared with vendor partners such as Verisk and Shift Technology, she noted. The harder problem is fraudsters who arrive unidentified and keep changing their identities and tactics.
The traditional model of waiting for suspicious claims to surface is no longer viable. "We're all moving from a reactive investigation, reactive claims handling, to trying to be more proactive," said Wilkinson. She argued that the carriers winning the fraud fight are those connecting claims and underwriting, two functions that have historically operated separately. Liberty Mutual has begun loading standard operating procedures directly into AI agents so that investigators reach the right files at the right time.
Few carriers yet feel ready for that shift, as shown by a survey finding few insurers prepared for AI-driven fraud, conducted by SAS and the Association of Certified Fraud Examiners (ACFE). Increasingly, the advantage lies not in the technology alone but in the data behind it.
The uncomfortable reality is that the same AI tools available to insurers are equally available to fraudsters. Verisk has described the same dynamic, warning that AI-fueled fraud is forcing insurers into an arms race. Hayes argued that if every carrier has access to the same underlying technology, differentiation comes down to data quality, operating model and people. "You can have great technology, but if you don't have the people and the talent in the organization and the willingness to change, you're going to be unsuccessful."
Younger consumers are most willing to edit insurance claims
Share of US consumers by generation, 2026
Source: Verisk State of Insurance Fraud study, March 2026. Survey of 1,000 US consumers, December 2025 to January 2026.
Wilkinson's analogy was direct: "Everybody has an oven. But it's the recipes and the cooks in the kitchen that are going to really win those appetites." Asked whether the industry is keeping pace with bad actors, she did not soften her answer. "It's a perpetual treadmill. And some are going to run fast, and some are going to be in there for the endurance, for the long haul."
Jawish said Shift Technology works with insurers in more than 20 countries to detect AI-assisted fraud, and that the industry's adoption pace is split. Some carriers are moving aggressively and deploying every available AI tool. Others, he said, simply freeze. Shift has treated AI internally as a productivity multiplier rather than a workforce threat. According to Jawish, the company is targeting output equivalent to 7,000 full-time employees from a team of 700.
The fallout from AI-assisted fraud is likely to reach clients in two ways: cost and friction. Fraud losses and the investment needed to detect them ultimately feed into pricing, so honest policyholders bear part of the bill. Clients should also expect more verification at first notice of loss (FNOL), the point at which a claim is initially reported to the carrier. That may include identity checks and more structured, app-based submission of photos and documents.
Brokers who explain these changes before a loss occurs will be better placed to keep legitimate claims moving and to protect client relationships when a carrier asks for more evidence. The ITC panel discussed how the carriers that pull ahead will be those that combine better data, connected claims and underwriting teams, and people willing to change. Brokers who understand how their carrier partners are approaching that challenge will be able to advise clients with more confidence.