This article was written in partnership with NZI
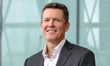
Troy Sexton (pictured) has spent close to 30 years underwriting commercial property across New Zealand, Asia-Pacific and Europe. He joined NZI – the commercial insurance brand of IAG New Zealand – in July as executive manager, portfolio performance and strategy, a newly created role on the insurer's leadership team. For brokers, Sexton’s new role brings that experience to shaping NZI's appetite and making it clearer where and how the insurer can support business. His message to brokers working in a softening market is not just about price.
“Engage us early and give our underwriters the opportunity to understand the risk, explore solutions and provide a clear response,” Sexton told Insurance Business.
It is a simple ask and in a hard market it would barely register. In this one it matters more, not less. Softer rates and broader terms give brokers more options, but do not remove the need to understand the underlying exposures and secure appropriate cover.
NZI's portfolio data is consistent with broader market indicators and shows commercial insurance remains in a sustained soft market environment. The insurer continues to see pricing pressure across a number of commercial segments, with competition remaining strong and brokers having more choice than they have had in recent years.
Read next: NZI works to catch electrical fires
Sexton joins NZI from Everest Insurance, where he established and led the company's property business for Asia-Pacific. Before that he spent 18 years with ACE and Chubb, including as Chubb's chief underwriting officer for property in Asia-Pacific, where he helped lead a portfolio spanning 12 countries.
The gap between pricing and exposure makes the conversation between brokers, insurers and clients about long-term resilience important.
The Insurance Council of New Zealand's 2025 Annual Review recorded total insurance claims across all lines of $3.8 billion, with full-year extreme weather losses of $278.2 million. The Natural Hazards Commission Toka Tū Ake reported in May 2026 that it was receiving more claims for landslide damage than for any other natural hazard, logging almost 13,000 landslide claims over five years – roughly 10,000 more than in the preceding five-year period.
Sexton's reading of that environment is that it is a feature of the market, not a flaw in it.
“We are a small country at the bottom of the world, but we have a highly developed insurance market, strong product penetration and access to broad coverage that is not available in many other markets,” Sexton said.
He is direct about what the market is doing. “The market is competitive, with brokers and customers benefiting from greater choice and capacity,” Sexton said. His caution is about what happens next: “Alongside price and breadth of cover, brokers should consider an insurer's financial strength, claims capability, consistency and commitment to supporting New Zealand businesses through different market cycles.”
That is a reasonable test to apply when capacity is abundant, because abundant capacity is the condition most likely to change. NZI has operated in New Zealand since 1859.
Read next: NZI research calls attention to risks faced by commercial drivers
Sexton's experience building portfolios without a claims history to lean on shapes how he reads appetite. “Building a portfolio from scratch teaches you to define the risk appetite, underwriting discipline and culture from day one,” he said. Running Chubb's book across 12 countries taught him something brokers will recognise from their own placements: “global models must always be tested against local conditions.”
For brokers who read underwriting discipline as a euphemism, he is unambiguous. “Discipline is not about defaulting to no,” Sexton said. “It is about knowing which risks you understand, what terms are needed and where the portfolio can grow sustainably.”
Asked what he would most like to change about how brokers work with clients, Sexton named one thing.
“The conversation I would like brokers to start earlier is about resilience,” he said. “That means helping clients strengthen risk management, maintain accurate valuations, understand their business interruption exposures and invest in measures that can prevent losses or support a faster recovery.”
Valuations and business interruption are two exposures that can be overlooked when competition intensifies and pricing pressure increases, and the two that surface fastest after an event. The pressure is measurable. The Reserve Bank of New Zealand placed insurance affordability on its financial stability risk register for the first time in its May 2026 Financial Stability Report, warning that underinsurance and insurance retreat from areas exposed to elevated flooding risk indicate financial stability risks may increase.
Sexton frames resilience as something that works in both directions. “Strong risk management gives insurers greater confidence and helps create more sustainable outcomes for customers over the long term,” he said – which is to say a documented risk management programme helps protect the client and gives underwriters a clearer basis for assessing the risk.
His role is built to act on that. “Individual submissions are assessed on their own merits, but collectively they tell us a great deal about changing customer needs, emerging exposures and the opportunities brokers are seeing in the market,” he said. “I use those insights to help shape our appetite and make it clearer where and how we can support business.”
The NZI Business Series, a broker roadshow held across five regions in August, gave Sexton a direct read on what brokers want from that process. “The strongest message was that brokers value clarity, consistency and early access to experienced underwriters,” Sexton said. Technology, in his account, serves that rather than replacing it: “Data and technology are important, but their real value is in helping experienced people make better decisions and respond more quickly.”
“For us at NZI, the challenge is to turn that feedback into action,” Sexton said. “We need to be clear about where we want to grow, consistent in our decisions and open to early conversations about how we can support brokers and their customers.”
Garry Taylor, executive general manager at NZI, said the appointment, alongside that of Kent Chaplin as head of liability, reflected a long-term commitment. “Troy and Kent are highly respected insurance leaders with proven leadership and extensive industry experience and bring deep technical expertise,” Taylor said.
So, for brokers, Sexton's message is that while the market may provide greater flexibility on price, the greater opportunity lies in strengthening the quality of risk conversations. This means getting an underwriter into the conversation while there is still something to shape. Valuations, business interruption and risk management detail are harder to retrofit at renewal than to build in early, making early dialogue between broker and insurer valuable for customers.