France’s latest riot losses have put existing insurance cover and routes to state compensation in focus, following legislation creating a new state-backed riot insurance scheme.
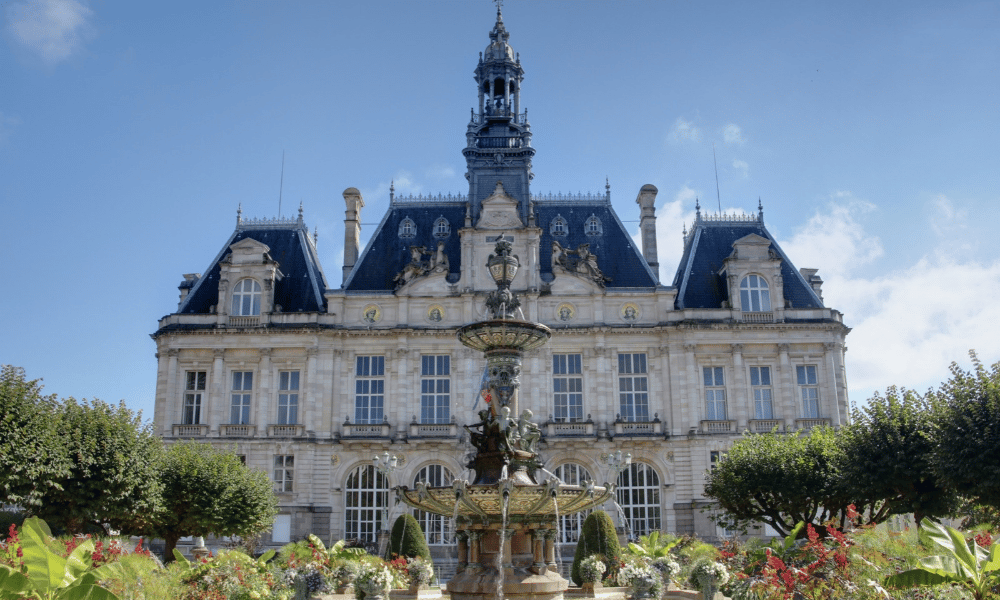
Protests over living costs and public services turned violent across French cities on 17 October, with looted shops, burnt vehicles and a fire that badly damaged Limoges' town hall. Alain Di Crescenzo, president of CCI France, said the number of businesses directly affected would exceed 2,000, with damage running to hundreds of millions of euros. Retail federation FCD had put the figure at 1,500 the previous day.
France's 2026 Finance Law will make riot cover mandatory in all property damage policies, with no exclusions permitted, and extend it to business interruption where a policy already includes that cover. If an insurer refuses to cover a risk because of riot exposure, the applicant will be able to petition the Bureau Central de Tarification, which can compel cover and spread the risk across insurers.
Insurers will be able to cede riot losses to a mutualisation fund that reimburses at least 90% of what they cede, financed by a solidarity contribution levied on insurers and backed by a state guarantee.
The regime, set out in Article 171 of the 2026 Finance Law, will take effect on a date set by decree, no later than 12 months after a favourable European Commission decision on state aid. The French Senate’s implementation tracker, last updated on 28 September, lists the decree setting the scheme’s commencement date as awaiting publication. Confirmation of its application to the 17 October losses was pending at publication.
The 2024 unrest in New Caledonia accelerated work on the scheme, after some insurers in France's overseas territories withdrew riot cover from certain policies.
Until the scheme takes effect, existing wordings decide what is covered. Article L.121-8 of the French Insurance Code excludes riots by default, but most multi-risk home and business policies write the cover back in through fire, theft, vandalism and glass sections. Article L.211-10 of the Internal Security Code also provides a route to recovery from the state, subject to conditions, for victims and insurers exercising subrogation rights.
The last comparable event offers a benchmark. The 2023 riots that followed the death of a teenager shot by police cost insurers €793m across some 16,400 claims, according to France Assureurs' latest estimate.
Public buildings are a particular pressure point. Council property accounted for 27% of the cost of the 2023 riots, and some local authorities saw riot excesses soar afterwards: a French Senate report cites a town of 20,000 people whose insurer unilaterally notified it of a €2m excess on riot damage less than a month after the unrest. Those insurability problems were a key driver of the new regime, and damage to buildings such as Limoges' town hall brings them back into focus.
The government has announced support. After a crisis cabinet meeting on 19 October, Prime Minister Sébastien Lecornu said the government was talking to insurers so people could access funds as quickly as possible. He announced a partial unemployment fund for workers whose businesses are out of action, and said a new law would make those responsible pay for repairs.
The mayors of Paris, Lyon and Marseille have also called for the national budget to fund repairs to damaged local authority facilities. Assurland spokesperson Olivier Moustackis has warned that higher claims costs could eventually feed through to premiums.
England and Wales take a different route. Eligible uninsured riot damage can be claimed from the relevant police claims authority under the Riot Compensation Act, while Pool Re’s public-private backstop covers terrorism rather than riot. Over the past decade, many insurers have cut SRCC limits or removed the cover from standard policies, a gap highlighted again by protests in Portsmouth last month.
For UK brokers arranging multinational property programmes, the practical question will be how mandatory French riot cover interacts with master policies covering clients' French locations once the regime takes effect.