The Australian Consumers Insurance Lobby (ACIL) says the revised General Insurance Code of Practice now before the corporate regulator still fails to expressly prohibit commercial arrangements that could compromise the independence of expert reports used to decide claims.
The Insurance Council of Australia (ICA) lodged the redrafted Code with the Australian Securities and Investments Commission (ASIC) yesterday. This new version proposes making key insurer obligations contractually enforceable for the first time since the Code was introduced in 1994. Insurance Business reported on the Code obligations becoming legally binding on insurers when the submission was made.
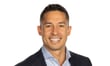
ACIL chairperson and broker Tyrone Shandiman (pictured), said the draft contains improvements, including stronger disclosure requirements but does not address how insurers appoint, instruct and remunerate the experts whose findings determine claim outcomes.
“After years of scrutiny of insurance claims handling, it is extraordinary that the proposed Code still does not expressly prohibit some of the very arrangements that could undermine expert independence,” Shandiman said.
Read next: Insurers face legally binding Code obligations for first time under revised Code of Practice
The group’s review of the Code and the ICA’s Use of Expert Reports: Industry Best Practice Standard concluded that neither document expressly bars financial incentives that reward expert suppliers for reducing, containing or denying claims; commercial restrictions that discourage experts from making findings contrary to an insurer’s interests; or instructions designed to steer experts towards predetermined conclusions.
ACIL’s characterisation seems to hold up against it. The expert report provisions sit at paragraphs 70 to 75 of Section 4 and they do not expressly prohibit any of the three arrangements the group names.
Those paragraphs require insurers to notify customers within five business days that an expert has been appointed, to use experts with appropriate expertise, to obtain reports within 60 business days, and to comply with – and instruct external experts to comply with – the ICA’s Use of Expert Reports: Industry Standard. Paragraph 74 requires insurers to monitor that compliance, with remedies including cancelling the expert’s contract, declining to assign them future claims, or requiring training.
Nothing in the Code addresses how external experts are paid. On commercial restrictions, paragraph 74 runs the other way: it expressly authorises insurers to deselect an expert, with non-compliance as the stated trigger and no safeguard against deselection on other grounds. On instructions, the only obligations point outward – to the Standard, and to experts’ own professional rules.
Read next: Draft Code would make insurer promises enforceable in court as ASIC lodgement slips twice
The contrast within the Code is sharper than ACIL’s release sets out. Express conduct prohibitions do appear – for investigators. Paragraph 104 requires insurers to direct investigators to avoid tactics designed to intimidate or unduly pressure a claimant, not to induce someone to do something they would not otherwise have done, and not to make any threat, promise or inducement. The Code is drafted with that language available. It is applied to investigators and not to external experts.
“The industry has rules about how expert reports should be written, but it still needs stronger rules about the commercial arrangements behind them,” Shandiman said.
There is a counterweight. Paragraphs 70 to 75 fall within Sections 1 to 9, which under paragraph 21 form part of the consumer insurance contract – so the obligation to instruct experts in line with the Standard will be legally enforceable by customers. The Industry Principles, including the commitment that services will be provided efficiently, honestly and fairly, expressly do not form part of the Code and operate as a guide only.
The ICA has previously rejected similar criticism, telling Insurance Business in 2024 that its standard requires experts to report objectively on the evidence presented. That exchange is set out in coverage of the ICA’s response to criticism of its expert report standards.
For brokers, the question is practical. Expert reports are the documents most often contested when a property or business interruption claim is declined, and brokers acting for clients in those disputes work from the report the insurer commissioned. ACIL is also seeking a fairer process for consumers to challenge questionable reports without having to fund competing expert evidence, which it says can cost thousands of dollars. The ICA lists “provide every expert report automatically” among the proposals it did not adopt in full, in the ICA’s industry response to the Code public consultation, published alongside the submission.
ACIL wants the ICA to publish a recommendation-by-recommendation reconciliation of the parliamentary inquiry into insurers’ responses to the 2022 floods and the Independent Review of the General Insurance Code of Practice, identifying what has been implemented, what remains outstanding and why.
Arguably, that demand is satisfied to a resonable degree already. The response paper the ICA released with its submission includes a section headed “Where we did not adopt proposals in full”, setting out six proposals and the reasoning behind each – among them the proposal that every expert report be provided automatically. The paper is organised by consultation theme rather than by recommendation, however, and responds to the 28 non-confidential public consultation submissions rather than itemising the findings of the two reviews. ACIL’s request is therefore answered in part on substance, but not in the form it has asked for.
“Consumers deserve more than wholesale assurances that lessons have been learned. They deserve evidence that meaningful reforms have been delivered,” Shandiman said.
ASIC will assess the Code under Regulatory Guide 183, the framework for approving codes of conduct in financial services. The Banking Code of Practice is currently the only industry code approved under it. Shandiman said the regulator’s decision carries reputational weight.
“ASIC’s approval must mean something. It should not endorse a Code that leaves significant consumer protection issues unresolved,” he said.
The lodgement followed two schedule slips, with the ICA pushing the deadline to late October after consultation closed in July. Insurance Business covered the delay to the Code lodgement and the industry-consumer divide in August.
ICA chief executive Andrew Hall said in the Insurance Council’s statement on submitting the Code to ASIC: “Our focus now is on working constructively with ASIC through the regulatory process so that the Code is approved and these stronger protections can begin delivering for consumers.”
A transition period is anticipated before the Code takes effect on new and renewed policies.
Insurance Busness has reached out to the ICA for a response to ACIL’s criticisms of the draft Code