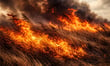
Bushfires are burning across Tasmania. Wind gusts of up to 100 km/h are driving fire fronts toward residential areas. Temperatures across multiple states are running as much as 15C above September averages – and summer has not started. For insurance brokers, the timing is the story.
Seven fire alerts are active across Tasmania, covering Colebrook, Seven Mile Beach, Lewisham, Dodges Ferry, Carlton, and Franklin. Three are Watch and Act alerts.
The Bureau of Meteorology (BOM) issued a severe wind warning on September 20, with gusts of up to 100 km/h recorded in the state’s south. Northwesterly winds averaging 65 km/h to 75 km/h were forecast over elevated terrain and the west coast.
“The fire is travelling towards Sandy Point and is impacting now. The fire is expected to be difficult to control. Embers, smoke, and ash may threaten you and your home before the main fire. It may become difficult to see and breathe,” BOM’s warning states.
BOM senior meteorologist Dean Narramore said the conditions are not short-lived. “It is looking a warm and dry week overall and will really start heating up in the latter part of the week and into next weekend,” Narramore said.
The heat extends nationally. Sydney and Melbourne are forecast to hit their highest September temperatures since 2023. Hobart is on track for its warmest September since 2019. South Australia is expected to see conditions up to 15C above average, with the far north reaching the mid to high 30s. Victoria is tracking 8C to 12C above September norms, with Melbourne expected to drop sharply from 27C to 15C in a single day.
Temperatures are forecast to ease briefly Monday and Tuesday before rising again from Wednesday, with early spring readings expected to exceed 30C in some states.
Read next: Postcode pricing cannot see what the Victorian fires revealed
The fires arriving in September sit within a risk picture that emergency services documented before spring began.
AFAC’s Seasonal Bushfire Outlook for Spring 2026, published August 19, identified heightened fire risk across northeastern Tasmania, northern and southeastern NSW, southeastern Queensland, parts of WA, SA, and Victoria, and large parts of the NT. The driver in Tasmania: below-average rainfall increasing fire risk potential across the northeast and east of the state.
AFAC CEO Rob Webb said: “This outlook highlights a heightened risk of fire across several parts of the country, driven by a combination of dry conditions in the east and increased fuel loads through parts of central and northern Australia. The variety of risk factors across different regions reinforces the need for communities to understand their local conditions and prepare early.”
BOM contributed to the AFAC outlook and, at an August 20 briefing in Melbourne, confirmed the Spring 2026 forecast identifies above-average risk for northeastern Tasmania – weeks before the current fires broke out.
The Insurance Council of Australia’s (ICA) 2025-26 Catastrophe Resilience Report recorded $3.98 billion in insured losses from 147,552 claims across seven declared events for the financial year – up from approximately $2.2 billion across three events the prior year.
Bushfire carries the highest average claim cost of any peril at $114,888 per claim since 2019, more than double the next-highest. That figure reflects how frequently bushfire results in total property losses rather than partial damage.
Those costs are rising in step with what it costs to rebuild. The ICA report cites Cotality’s Cordell Construction Cost Index, which shows national home building costs rose around 30% over the five years to 2026, against CPI growth of about 24%. In Tasmania, that increase is approximately 43%. Roof tiles – the first structural element destroyed in most fires – rose 77% over the same period.
For any client whose sum insured has not been reviewed in the past two to three years, the gap between their coverage and actual rebuild cost is likely material.
The affordability pressure in Tasmania predates the current fire activity. A March 2026 report from the Tourism Industry Council Tasmania (TICT), drawing on data from 109 tourism businesses that collectively host more than 2.2 million visitors annually, found public liability and property insurance premiums had risen by more than 50% over five years.
That pressure is significant enough that the Tasmanian government has been pursuing TasInsure – a government response targeting tourism operators, small businesses, and community groups where market access has become difficult. Originally proposed as a state-owned insurer at the 2025 election, the model was revised in May 2026 following expert advice from insurance specialist John Trowbridge. TasInsure will instead operate as a government-owned, not-for-profit statutory authority with a broad mandate to oversee and support the state’s insurance market.
In January 2026, Premier Jeremy Rockliff said: “For too long, Tasmanians have been underinsured, unable to get insurance, or paying the price of disasters on the mainland.” Legislation to formally establish TasInsure had not passed as of publication.
For commercial clients in fire-affected zones, the ICA’s data from Victoria’s January 2026 bushfires is a relevant reference. Commercial claims in that event carried a disproportionately high cost share, driven by losses to primary producers, tourism operators, and businesses reliant on visitor access – a pattern directly applicable to Tasmanian operators facing active alerts now.
Read next: Storm fraud surge puts broker conduct records in ASIC’s sights
The ICA has not issued a catastrophe or significant event declaration for the current Tasmanian fires as of publication. No claims data has been released. Brokers should monitor the ICA’s current catastrophes page for updates as conditions develop.
Three risk conversations are worth having before a claim is lodged:
The ICA’s catastrophe data shows declared events impacted 149 of Australia’s 150 federal electorates between 2022 and 2026. The fires burning now are a prompt, not a warning.
The three points above reflect general risk considerations for brokers and do not constitute financial or insurance advice.