A Senate committee has recommended that legislation removing the age-based private health insurance rebate for Australians aged 65 and over be passed. A peak body representing more than 5.4 million Australians has renewed its call for senators to reject it.
The Senate Community Affairs Legislation Committee released its report on the Private Health Insurance Amendment (Modernising the Private Health Insurance Rebate) Bill 2026 on October 7. Members Health Fund Alliance responded the same day, warning the change will force pensioners and lower-income retirees to pay more for cover at the stage of life when they need it most.
"At a time when older Australians are facing mounting cost-of-living pressures, the government is still trying to press ahead with a proposal that will force many pensioners and lower-income Australians to pay more to keep the health cover they have maintained throughout their lives," said CEO Matthew Koce.
The bill would set the private health insurance rebate by income alone, removing the higher rates currently available to older Australians. It would take effect on April 1, 2027, the same date as the industry's annual premium adjustment.
Read next: Older clients, higher costs: why brokers can't wait for the Senate
Around 3 million older Australians hold private health insurance, about 1.5 million of them age pensioners, according to the Parliamentary Budget Office (PBO). The PBO estimated age pensioners will bear roughly half the cost of the rebate cut.
Under current settings, Australians aged 65 to 69 receive a base-tier rebate of 28.139%, and those aged 70 and over receive 32.158%. Both groups would drop to the under-65 rate of 24.118%.
Modelling by Private Healthcare Australia shows what that means when combined with the April 2027 premium round:
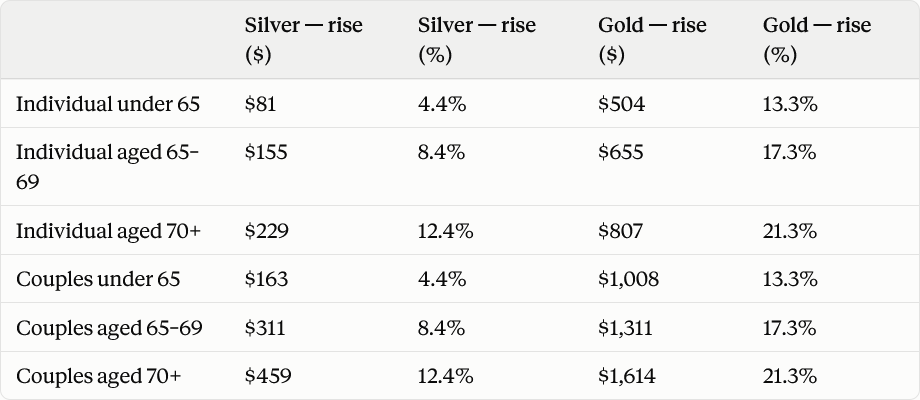
Based on average Gold single cover of $3,790 and Silver single cover of $1,854. Source: Private Healthcare Australia, May 2026.
Koce said those most exposed are the least able to absorb the increase. "Many of these Australians did exactly what successive governments encouraged them to do. They took responsibility for their healthcare, paid private health insurance premiums for decades, and helped relieve pressure on the public health system. They are now being asked to pay the price for a budget decision that will remove support at the very time they need healthcare the most," he said.
The more immediate risk for clients is not cancellation but downgrading, moving to a lower tier to manage costs and losing access to the procedures they held cover for.
Gold cover includes joint replacements and cataract surgery. According to National Seniors Australia's submission to the Senate committee, downgrading to Silver may leave policyholders without cover for those procedures. On average, the price difference between Gold and Silver single cover is about $1,936 a year, based on Private Healthcare Australia's published averages, although individual policies vary.
That trade-off was already playing out before the bill. The proportion of Australians holding Gold cover fell from 40% in 2020 to 30% in 2025, according to CHOICE. Gold tier policies absorbed average increases of 13.3% from major funds in the April 2026 premium round, against an industry average of 4.41%.
Catholic Health Australia's independent modelling estimated that one in five affected over-65s will change their level of cover in the first three years, about 665,000 downgrades. That is significantly higher than the government's assumption of one in 75, according to the Coalition's dissenting report to the Senate committee.
Members Health warned the impact will extend beyond those directly affected. "When private health insurance becomes less affordable, healthcare demand does not disappear. More Australians will be forced to consider downgrading or dropping their cover, pushing additional demand onto public hospitals that are already under significant pressure," Koce said.
Catholic Health Australia told the Senate committee the bill removes revenue from a private hospital sector that recorded a $756 million operating loss in 2024-25, with the sharpest impact on standalone regional facilities where older patients dominate admissions. The finding is cited in the Coalition's dissenting report.
Medibank separately warned the committee that declining participation in comprehensive products concentrates costs among fewer policyholders, putting upward pressure on premiums across all age groups.
Read next: PHI rebate forecasts diverge on older Australians leaving cover
Members Health pointed to the breadth of opposition, with the Coalition and the Australian Greens both filing dissenting reports. "It is rare to see such broad agreement across the Parliament, but the Coalition and the Greens are right to recognise the significant impact these rebate cuts will have on lower-income Australians and the public health system," Koce said.
Coalition senators cited a 2023 independent report by Finity Consulting, commissioned by the Department of Health, which found the age-based rebate provides "good value" and that removing it would produce declining value for government. The Greens raised concerns about the impact on pensioners and part-pensioners on fixed incomes.
The committee noted that private health insurance participation is projected to grow by 3.5% between 2025-26 and 2028-29. The Department of Health's modelling projects about 44,000 fewer adults aged 65 and over will hold cover by 2028-29.
Members Health called on crossbench senators to weigh that position carefully. "The Senate now has an opportunity to stand with older Australians, listen to community concerns, and reject a proposal that will make healthcare less affordable for pensioners and place further pressure on an already strained public hospital system," Koce said.
The bill still requires a Senate floor vote. If it passes, the April 2027 start date is fixed, and for clients holding Gold tier cover in their later years, the window to review their options is narrowing.