An insurance executive whose legs were crushed when a coconut palm fell onto her sun lounger in Sri Lanka is suing the law firm she hired to win her compensation. The firm sent the paperwork launching her case to the wrong email address.
Claire Saywell, from Sittingbourne in Kent, is seeking £4.5m from Slater and Gordon UK. The firm has admitted it failed to validly serve the claim form in her personal injury action against Tui UK, and that failure led to the claim being struck out. It doesn’t, however, accept that the mistake cost her anything close to £4.5m, arguing her case against the travel company was never a strong one.
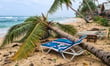
The High Court heard that at about 10.20am on 16 February 2017, Saywell was sunbathing by a pool at the four-star Club Hotel Dolphin in Waikkal, on Sri Lanka’s west coast. It was hot, with only a light breeze. The loungers sat beneath mature coconut palms which, according to her barrister, stood roughly 25 to 30 metres tall.
One came down without warning. Its trunk broke through her lounger and bent her legs backwards at the knee. She had emergency surgery in Colombo before being flown home to Kent. Almost a decade later she has had about 10 operations on her legs and lives with ongoing pain and disability. She now needs single-storey accommodation.
Saywell built her career in insurance. Local press described her as a commercial insurance broker in 2017. In court she was described as a well-paid peripatetic insurance executive, a job that kept her travelling between clients. She has had to give it up and is now unemployed.
Read next: UK insurers urged to brace for surge in summer travel claims
Saywell instructed Slater and Gordon, one of the best-known names in UK personal injury, to pursue Tui, through which she had booked the holiday. Speaking outside court, her barrister Howard Elgot said the firm served the claim on the wrong email address for Tui’s solicitors, and the claim was struck out as a result.
Litigators will wince. Under Part 7 of the Civil Procedure Rules, a claim form served within the jurisdiction requires the claimant to complete the relevant step before midnight on the calendar day four months after the form was issued. Email is not a default option either. Under Practice Direction 6A, email service is only valid if the receiving party or its solicitor has previously confirmed in writing both that it will accept service that way and the specific address to use. The Supreme Court showed how unforgiving that rule can be in Barton v Wright Hassall, where a claim form was emailed to the defendant’s solicitors without any prior indication that they would accept service that way, and it was common ground that this was not good service.
The court reports do not say why the claim could not simply be reissued. Timing is the likely obstacle. Under section 11 of the Limitation Act 1980, personal injury claims generally have to be brought within three years of the accident, or of the injured person’s date of knowledge if that is later. Courts do have a discretion to disapply that limit in some cases. How far Saywell’s case had progressed by the time of the strike-out has not been reported.
Breach is admitted, so the dispute is about what it is actually worth. Master John Dagnall described it as a “loss of a chance” claim. The court must assess what Saywell’s prospects would have been if the case against Tui had gone ahead. Under the approach the Supreme Court confirmed in Perry v Raleys Solicitors, where a beneficial outcome depends on what others would have done, it is evaluated on a loss of chance basis, applying the relevant percentage to the prospective benefit.
Her team puts that chance above 90%. Elgot told the court that an arborist who reviewed the evidence in the original claim found a spike and concrete had been driven into the base of the tree to anchor a utility line, causing rot and damage to the trunk. In the expert’s view, palms like this would not normally blow over unless already rotten, and a layperson could have spotted the damage. Four witnesses would also have said the wind was modest that day.
Clare Elliot, for Slater and Gordon, told the court the case against Tui did not exceed a 51% likelihood of success. She added that the £4.5m figure is highly contested. As set out in court, the defence is that a sudden strong gust brought the tree down, a natural event with no human failing on the part of the hotel or its contractors.
The gap between those positions is worth a lot of money. As a purely illustrative example, if a court accepted £4.5m as the full value of the lost claim, a 51% chance would be worth about £2.3m and a 90% chance about £4.05m. That is a difference of roughly £1.75m before anyone argues about the £4.5m itself.
Master Dagnall gave Saywell permission to rely on the arborist’s evidence. Both sides will now try to settle through alternative dispute resolution.
Read next: Solicitors facing expensive professional indemnity insurance costs - report
The error behind this claim is administrative, not a failure of legal advice, which is exactly the type of loss PI insurers keep seeing. Travelers has warned of a rise in retainer management issues and errors due to slips and lapses, and says such claims stem from distraction rather than bad advice.
The size of the claim also matters. Under the SRA’s indemnity insurance rules, the minimum sum insured for any one claim is £3m for relevant recognised and licensed bodies and £2m for everyone else. The SRA’s register lists Slater and Gordon UK Limited as a licensed body authorised and regulated by the SRA, which puts it in the £3m bracket. A claim pleaded at £4.5m therefore sits well above the compulsory primary layer. That gap is what excess layer cover is designed to fill. The firm’s own insurance arrangements were not discussed in court.
Capacity is not the problem for law firms right now. Broker Howden reports that 63 participating insurers are listed on the SRA’s website for the 2026/27 indemnity period, the highest number on record and more than double the 26 when the hard market began in 2019 (the current list is on the SRA’s participating insurers page). Howden adds that rate cuts of around 10% were common for many firms at the October renewal. It also cautioned that falling rates should not be read as evidence that the underlying risks facing solicitors have shrunk. That echoes last year’s renewal, when the market softened despite rising claims activity.
For travel and liability insurers, the original claim shows how a UK tour operator can end up answering for what happens at a hotel abroad. The current package travel rules, the 2018 regulations, only apply to packages and linked travel arrangements concluded on or after the commencement date, which was 1 July 2018. A holiday taken in February 2017 would fall under the older Package Travel, Package Holidays and Package Tours Regulations 1992. Under those rules, the other party to the contract is liable to the consumer for the proper performance of its obligations, even when a foreign supplier delivers the service. Court reports do not say how Saywell’s booking was structured.
Injuries like hers are expensive. Recent figures show medical expenses made up 43% of travel insurance claims, with fractures and broken bones the most common medical claim type at 34% (see the full breakdown).
When Saywell first went public in 2017, Tui said it regularly audited the hotels it featured for health and safety and that incidents like this were rare. Slater and Gordon’s travel specialist said at the time that resorts and tour operators needed to make sure their trees were properly inspected and maintained. Nine years on, the firm’s own procedures are the ones under examination.
Read next: ‘He is sexually attracted to fish’: is there insurance for that?