Insurance brokers in Australia and New Zealand want governments to set the limits on artificial intelligence but an underwriting agency CEO has pushed back, arguing regulators cannot keep pace and that the industry is better placed to control the risk.
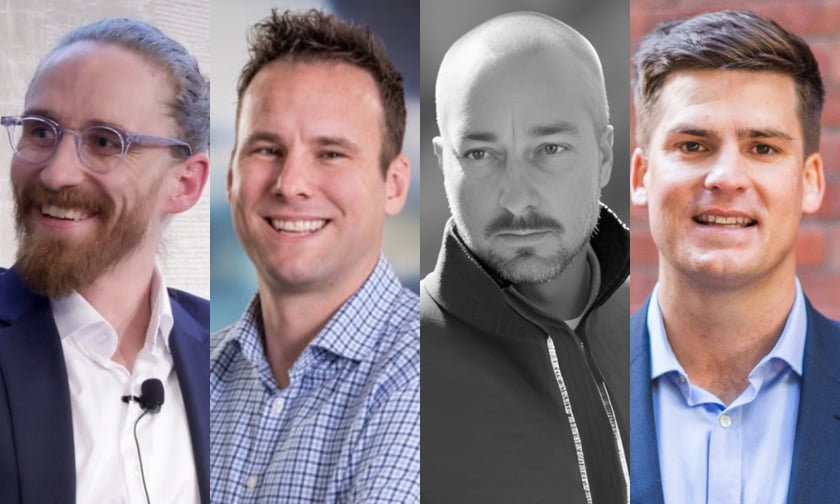
Mark Luckin (pictured left), national manager for the cyber and technology sector at Lockton Companies Australia in Sydney, was unequivocal about where authority should sit.
"My vote would be for government (and independent regulators within government)," he said, adding that industry self-governance would lack accountability and that insurance does not carry the required influence and authority.
His qualification concerns are driven by risk. "The brake should attach to the risk of the use case, not simply the label 'AI'," Luckin said. "A tool helping draft an internal email should not face the same constraints as a system materially influencing employment, credit, healthcare or safety-critical decisions, by example."
He set out a minimum standard for what regulation must deliver: "To work, regulation must establish non-negotiable boundaries, while developers and organisations using AI remain accountable for ownership, testing, human oversight and the ability to stop or roll back a system."
On his own industry's role, Luckin drew a firm line. "Insurance can reinforce that discipline, but it cannot substitute for it."
Damian Schade (pictured centre-left), client director at Lockton Companies NZ, reached the same position from a trans-Tasman perspective, arguing "the consequences of no brakes will impact all areas of society". He described government intervention as critically important while acknowledging it would be "challenging from a multi-jurisdictional perspective".
Andrew Brett (pictured right), director of Adelaide-based cyber brokerage Infosure and a certified cyber insurance specialist, dismissed the alternatives outright.
"Self-governance often prioritises commercial interests. It is not very effective in my opinion," he said. He was equally blunt about insurance: "Insurance tends to influence behaviour after risk awareness has emerged, rather than proactively change social norms."
"I believe government regulation remains the strongest mechanism for achieving widespread change," Brett said. "If we are looking for any kind of change at scale, government regulation has repeatedly proven to be the most effective tool available."
He does not rule out a slowdown but expects it to hurt. "A slowdown is still realistic, however it is often a slow and costly process, which we are somewhat seeing at the moment," he said.
Jaydon Burke-Douglas (pictured centre-right), chief executive and founder of Sydney-based Antipodean Underwriting, disputed the premise the three broking voices share.
"Government has repeatedly shown that it is unable to keep pace with the speed at which the technology is developing," he said. "Industry needs to take responsibility for how AI is developed and deployed."
Burke-Douglas, who spent five years as general counsel and head of operations at underwriting agency ProRisk after an earlier role as general counsel and company secretary for the DUAL Asia Pacific group entities, also rejected a slowdown outright.
"I don't think a complete slowdown of AI development is realistic, nor necessarily desirable," he said. "Nor do I think that inviting government regulation and the resulting overreach is beneficial."
Rather than treating the three mechanisms as alternatives, he places them in sequence: "Government regulation sets the floor, industry self-governance should raise the standard, and insurance can provide an additional market-based mechanism for rewarding responsible risk management."
His most concrete point concerns what brokers will encounter at renewal.
"As AI becomes embedded in businesses, insurers will increasingly be asking questions about how AI is being used, what controls are in place, who is accountable when something goes wrong, and what the price is to transfer that risk of business' balance sheets," Burke-Douglas said.