This article was written in partnership with Zurich
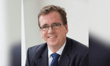
Brokers heading into renewals with double-digit rate reductions on the table face a question that outlasts the quote in front of them: whether the client is still well served when the cycle turns. Matt O’Sullivan (pictured), chief underwriting officer at Zurich Australia and New Zealand, told Insurance Business at the recent National Insurance Brokers Association (NIBA) Convention on the Gold Coast that pricing pressure can be a big challenge for brokers and insurers.
"We’re obviously in a market at the moment that is often talked about as being a really soft market, which means there’s a lot of pressure from the insurance point of view around pricing," he said.
The soft conditions are well documented. Pacific commercial insurance rates fell 12% in the third quarter of 2026, the eleventh consecutive quarterly decline, according to Marsh’s Global Insurance Market Index published in October. Property led the fall at 14%, as set out in our analysis of why not every client gets the full rate cut. Marsh groups Australia with New Zealand and the wider South Pacific.
O’Sullivan said the length of the softening had created a practical problem for parts of the market.
"One of the biggest challenges we see from the broking side of things is how do they ensure that they have a long-term sustainable approach to the customer?" he said.
Read next: Three challenges facing Kiwi and Aussie brokers
O’Sullivan said it's important the customer gets the right level of service over the whole cycle rather than just a short-term low price.
"You have to look over the medium to longer term and make sure that you’re providing the customer with the sustainable solution that we should be providing,” he said.
Asked how Zurich was supporting brokers, O’Sullivan said the insurer tried to shift the conversation away from rate alone. "We try often to take price as not the most important factor when we’re talking about the way in which we’re trying to manage a customer’s risk," he said. "We look at other things like claims payment, capital strength and longevity and relationship."
He acknowledged the limits of that position. "Obviously price has a factor to play, we’ve got to be realistic about that, but we’re trying to make sure that the consumer, the ultimate consumer of the insurance product, is getting a longer-term view of risk mitigation rather than just looking at short-term gains."
Read next: NZUAC Expo aims to help brokers seize soft market opportunities
From the insurer perspective, he said connecting early with brokers and working together with them through the whole insurance process was key.
“Make them see that this is not just about price, it’s about a whole other range of factors as well," he said. The tension O’Sullivan described between discipline and market share is one our reporting on chasing premium in a soft market has tracked through the current cycle.
Catastrophe exposure remains the main variable in the outlook. Property in flood, bushfire and cyclone zones has largely missed the softening and storm season is only beginning, as noted in our coverage of the gap between retail and commercial rate movements. O’Sullivan also named geopolitics and new technologies among the pressures raised at the convention but said the cycle was where Zurich was concentrating.