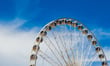
New Zealand’s workplace safety regulator has prohibited a Ferris wheel from operating after two teenage girls fell from the ride at an agricultural show in Greymouth, raising questions about how liability is structured at events where amusement attractions are supplied by independent contractors rather than the organiser.
The teenagers fell from the Ferris wheel, operated by Sturgeon Amusements, at AgFest West Coast on Saturday October 17, striking another girl on the ground. All three were taken to hospital and subsequently discharged. Police accounts suggest the girls fell approximately 12 metres after a support component on their carriage broke, causing the seat to tip forward, though WorkSafe New Zealand has not announced its findings and enquiries are ongoing.
WorkSafe issued a prohibition notice preventing the Ferris wheel from operating while a competent person is engaged to assess it and provide a report to both the owner and the regulator. AgFest West Coast managing director Andy Thompson said organisers had received safety documentation from the ride operator before the event, including maintenance records. The accident occurred approximately 30 minutes before the two-day event closed, following Saturday attendance of more than 10,000 people.
Event organisers and ride operators may each hold public liability policies, but whether coverage responds to a mechanical ride injury depends on the insured activities, applicable exclusions and how contractual responsibilities are divided between the two parties. Brokers advising event clients should not assume that an organiser’s event liability policy automatically picks up injuries involving rides operated by an independent contractor.
Underwriting practice in the region illustrates the gap. One Underwriting’s event liability product lists amusement rides among its exclusions. Arena Underwriting’s event liability proposal requires applicants to disclose amusement rides and identify who operates them and whether they carry their own public liability insurance. Such provisions are standard across specialist event liability products precisely because the exposure is treated as a separate risk, not an extension of the general event program.
Where an organiser’s policy excludes amusement rides, separate cover is necessary - either held by the ride operator and confirmed before access is granted, or arranged by the organiser as a condition of the contractor’s participation. Reviewing contractor insurance certificates and checking that ride operator policies cover the specific type of attraction and the quantum of potential injury claims are practical steps brokers can take with event clients ahead of the summer show season.
The incident comes as public liability insurance for the leisure and events sector remains under pressure. The Insurance Council of Australia reported in October 2025 that average public liability costs had increased by up to 60% since 2019 for festival operators, amusement venues and community organisations. Insurers in the region have tightened underwriting around amusement devices in particular.
New Zealand’s amusement device requirements mandate engineering examinations, equipment registration and local authority permits. WorkSafe’s enquiries into the Greymouth incident remain ongoing.