Lloyd's absorbed one of its worst catastrophe years in recent memory. The syndicates still made money.
Helios Underwriting PLC, the only publicly traded company providing diversified access to Lloyd's syndicates, posted a profit before tax of £11 million for the first half of 2026, up from £4.4 million in the same period of 2025. The result was driven by an improvement in estimated syndicate profits, with net asset value rising to £2.70 per share after payment of a 10p dividend - a 6.5% total return in the half year. The 2023 year of account closed with £40 million in net underwriting profits received in May. Helios expects the 2024 year to produce another positive return.
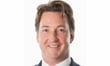
The numbers matter less as financial outputs than as evidence of what the Lloyd's market absorbed to produce them. The 2024 underwriting year carried hurricanes Helene and Milton, which chief executive Louis Tucker (pictured) said generated market-wide insured losses of approximately US$20 billion (£15.1 billion) each. The year also included the Baltimore Bridge Collapse, which Tucker described as "the costliest loss ever to have hit the marine liability insurance market."
The bulk of the estimated US$40 billion (£30.2 billion) in California wildfire losses from early 2025 also fell to 2024 year policies. Despite that load, the 2024 year of account's mid-point profit forecast improved in the half year, tracking towards 10.2% profit on capacity.
Pricing across Lloyd's has been easing. Risk-adjusted rates across the Lloyd's market fell 6.7% in the first half of 2026, nearly double the 3.5% reduction recorded in the same period of 2025, even as gross written premium rose 6.9% to £34.7 billion on the back of volume growth. Tucker acknowledged the shift, noting there has been softening in pricing levels across most classes over the past year, while maintaining that rating remains robust.
The 2026 year has, so far, seen catastrophe losses below recent averages, with Middle East conflict losses partly offset by improved marine transit premiums. The underlying combined ratio, which strips out the benefit of lower catastrophe losses and prior-year reserve releases, moved from 82.1% in H1 2025 to 84% in H1 2026. That direction points to the gradual erosion of rate adequacy rather than any deterioration in loss experience.
The investment income picture provides some buffer. Higher bond yields, combined with substantial reserves built across the syndicates Helios supports, have made investment returns an increasingly meaningful contributor to Lloyd's overall profitability. That structural shift did not exist in the low-yield environment of the previous decade.
The structure of Lloyd's underwriting, where profits from a given year of account are recognised over a three-year period, means that brokers placing business now are operating in a market still releasing the gains of the hard-market years. Helios expects the cash flow benefit of its 2024 and 2025 pipeline profits to materialise in 2027 and 2028, respectively.
That deferred recognition is not a technicality. It means that even as current-year pricing softens, the syndicates underpinning the Lloyd's market carry a substantial cushion of unrealised profits from years where discipline held firm.
Tucker pointed to that cushion in the company's outlook statement, arguing that the Lloyd's market's strong pricing environment continues to flow through in recognised pipeline profits. Lloyd's own forward guidance, published late in 2025, projected £67.4 billion in gross written premium for 2026 alongside a 91.2% combined ratio. That market remains structurally profitable but where the margin for discipline to slip is narrowing.
That narrowing is the backdrop against which brokers are now working placements. The 2025 year of account is still at an immature stage of development, but the lower incidence of major losses compared with 2024 points towards a strong result. The 2026 year has not yet generated the kind of catastrophe load that would test the market's reserve buffers. Helios noted that overall forecast results remain on plan. The question heading into the second half is whether underwriting discipline holds as competition for premium volume intensifies.
AM Best, assessing the Lloyd's reinsurance segment in September, noted that rates have moderated from a very strong peak but remain adequate, with the caveat that profitability through the rest of the year will depend heavily on catastrophe experience, and on how losses from the Middle East conflict develop.