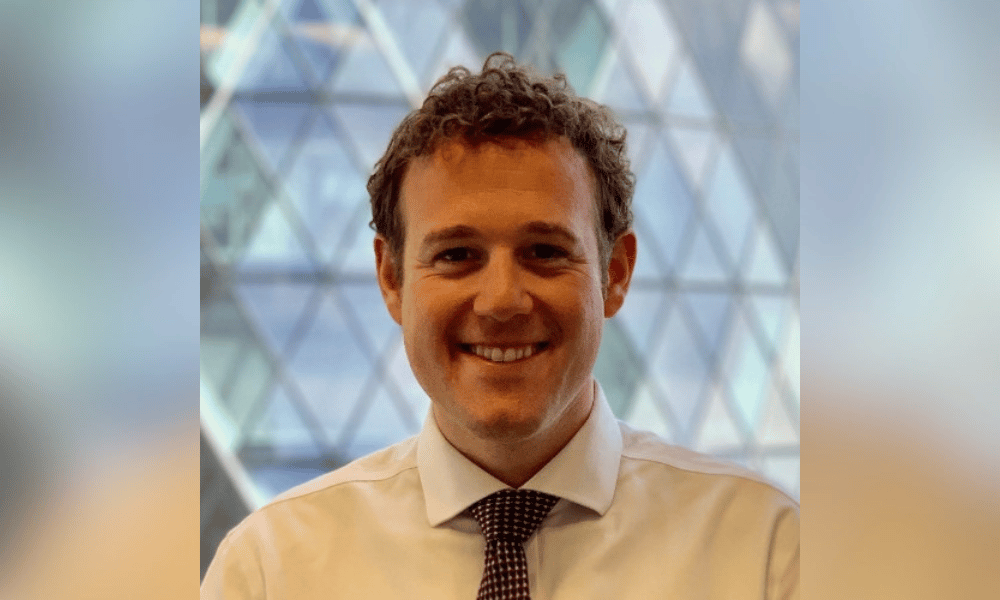
Insurers are competing harder for UK mid-market business, but a cheaper quote does not necessarily mean a broader underwriting appetite. As commercial rates continue to fall, brokers have more room to negotiate on property and liability placements. Rob Carslake (pictured), head of London, mid-market at Allianz UK, said that can mean improved wordings, more flexible deductibles, multi-year agreements and service commitments, as well as lower premiums.
The harder question is whether an insurer will consider risks it previously declined, or simply offer better terms on business it already wanted. Carslake said insurers naturally have more flexibility with risks they know well, making that distinction difficult to judge from pricing alone.
"The real test of appetite expansion is whether an underwriter is willing to consider opportunities they may have not historically pursued, while remaining within their risk appetite and underwriting framework," he said.
Carslake said brokers can establish how far an insurer's appetite has moved by asking which sectors it is more willing to consider and why. The discussion can then turn to the characteristics of an individual risk: what would make an underwriter comfortable supporting it, and what expertise or capabilities has the insurer developed to pursue that business?
Those questions are more revealing than a general statement about growth. An insurer may be willing to quote more competitively across its existing book while remaining selective about unfamiliar trades or more complex exposures. For Carslake, the evidence of expansion lies in the decisions underwriters can make and their willingness to engage with a risk that does not fit neatly into established classifications.
"Growth isn't just a statement in an insurer's marketing literature," he said. "It's reflected in the decisions underwriters make, the authority they have to act and their willingness to engage in conversations about new opportunities."
Regular conversations also give brokers a chance to learn where appetite is changing before a specific placement becomes urgent. That can help them identify the right market for a client and understand what information an underwriter will need to make a decision.
Broader appetite does not remove the need for a strong submission. Carslake said underwriters need a clear picture of a business, including its management, risk controls and future plans, rather than the minimum information needed to seek a quote. Sector knowledge and a well-presented account of the exposure help them judge the individual risk, rather than relying on its trade classification alone.
"Strong underwriters don't lower standards to achieve growth," he said. "They use their expertise to distinguish between a challenging risk that can be improved and one that is outside appetite."
That leaves room for a conversation about what could change an underwriter's view. A risk may need better controls, clearer evidence of how it is managed or a different programme structure. A submission that explains those points gives the underwriter more to work with than one built around the prospect of a lower premium. Allianz has also emphasised understanding a client's business in depth in its approach to large mid-market broker relationships.
Carslake said the strongest negotiating position comes from customer insight, the quality of the risk presentation and relationships built over time. Those factors matter when seeking terms now, but also when considering whether a programme will remain sustainable as the market changes.
Greater competition gives brokers more to compare than price. Claims performance, service after placement and consistency in underwriting can all affect the value of an insurer's offer, particularly if a client needs support during a difficult claim or at a future renewal.
Carslake said competition can improve service and customer outcomes, but said decisions driven chiefly by short-term market pressure work against that. "Healthy competition drives innovation, service improvement and better customer outcomes," he said, but customers "aren't looking for innovation at any cost. They want clarity, fairness and reassurance that their insurer will respond in the right way when it matters."
Every broker polled in Ascend Insurance Holdings' survey expects the soft market to plateau by the fourth quarter of 2026. If it does, the test will be whether insurers remain willing to support risks beyond their established book.