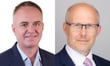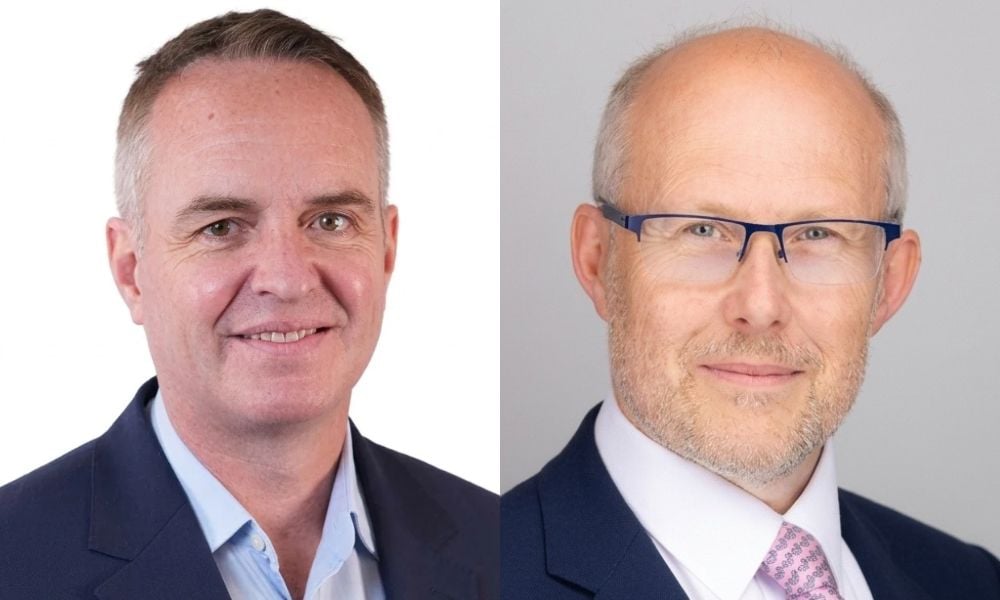
Two years ago, slow authorisations were the complaint brokers raised most often on the British Insurance Brokers' Association's (BIBA) regional tour. So far on this year's tour, chief executive Graeme Trudgill (pictured, right) said, he has not had one.
When the association looked at the numbers last year, he said, there had been something like three applications to become a new directly authorised broker in the first quarter, which he called incredibly low given the amount of M&A in the market.
BIBA has now launched a Start-Up Hub with Intact Insurance to guide would-be founders through authorisation and business planning. Fraser Edmond (pictured, left), vice president of sales, distribution and marketing for commercial lines at Intact, said a thriving independent broker market "is good for customers, it's good for brokers, it's good for insurers". But brokers who have set up recently have told IBUK the regulator was never their only obstacle.
The association's regulation committee pinpointed the blockers, Trudgill said, then made the growth case to the Treasury using comparisons with France and Italy, and took the evidence to the FCA's director of authorisations. "Could they have a can-do approach rather than, sorry, question 17B isn't quite answered correctly?" he said. He credited the FCA with working "really, really constructively" since, though applications still need to give the regulator everything it genuinely needs.
The Financial Services and Markets Bill, which Trudgill said has cleared the Lords and is now in the Commons, goes further. He said it would shorten the statutory deadline for authorisation decisions and create a provisional licence regime letting an eligible new firm trade before it is fully authorised. He expects it to take effect in the first quarter of next year.
Until now, getting a new broker's authorisations approved could take around a year, "You can imagine, having to wait a year with no clients and no business to support investment of the firm," Trudgill said. The licence will not be open-ended, though. HM Treasury's December 2025 policy update would cap it at up to 18 months and let the FCA limit the amount and type of business a firm writes in that time.
The appointed representative (AR) route has been the more popular way in because the principal takes care of agencies, IT and regulation. Some use a network to incubate the business for a year or two before moving to full authorisation, while others go direct from the start to control their own regulatory matters and IT platforms.
Brokers who chose not to go direct point to agencies as much as authorisation. Martin Castleton of Aureum Insurance Brokers told IBUK in September that low early volumes could leave a new directly authorised firm on lower-commission agency terms. John Elliott, who launched a Coversure franchise in August, said a new brokerage without a book to bring across would struggle to win the agencies it needs on its own.
Edmond said a firm with no premium history has to demonstrate credibility and capability. Founders usually bring a track record from previous roles and should make that clear to underwriting partners, alongside a clear view of where they will play and which customers they are going after, all "wrapped up in a clear and ambitious business plan". He said Intact has recently worked with start-ups in exactly that position that have gone on to deliver on their plans.
For Trudgill, that plan is where solvency, technical expertise, market knowledge and commitment are evidenced. Some insurers require minimum levels of support while others are more flexible, and recent start-ups among its members have asked BIBA for help with their business plans and regulatory applications, the ground the Start-Up Hub now covers.
Edmond said today's start-up could be a medium-to-large broker within five years, and said he had just spoken to one with £10m of premium two years after launching. Trudgill described start-ups as the insurer's regional branches around the UK, and said he has seen new firms step into local gaps left when acquisitions close branches. "With so much M&A, we've got to support this pipeline coming through," he said. There is a lot of support for start-up brokers from the market right now, he added, though that has not always been the case.
The regulatory door is opening. Whether more founders walk through it as directly authorised firms, rather than via a network, may now depend less on the FCA than on whether insurers will write agencies for brokers that have yet to build a book.