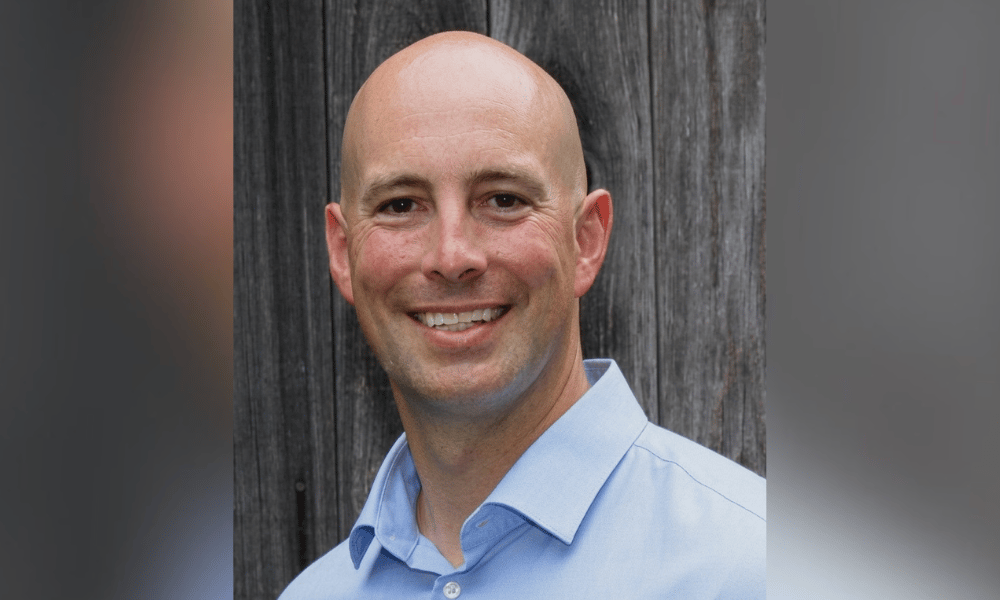
Insurers pouring money into artificial intelligence are still underestimating what the technology needs to work, according to Aaron DiCaprio (pictured), US head of programs at Atlanta-based Accelerant. In his view, clean, standardized specialty insurance data has to come before any model can deliver on its promise.
Accelerant operates the Accelerant Risk Exchange, which connects MGAs and other specialty underwriters with risk capital providers. The exchange spans roughly 700 specialty insurance products across 22 countries, according to the company’s August 2026 regulatory filing.
That same month, Accelerant entered into a definitive agreement to be acquired by affiliates of Thoma Bravo in an all-cash transaction with an enterprise value of more than $4 billion, just over a year after its July 2025 debut on the NYSE. The transaction is expected to close in the first half of 2027, subject to customary closing conditions, including approval by Accelerant shareholders and receipt of required regulatory approvals.
DiCaprio said the way carriers are built can work against them.
“Carriers can be monolithic organizations where change looks and feels different. They were built for stability, control, and consistency, which can make it harder to pioneer new waves, move, and adapt quickly,” he said. Much of the industry’s digital transformation, he said, began by wrapping digital interfaces around existing processes, an approach that leaves the underlying data problem in place.
“AI doesn’t solve fragmented, inconsistent data. You need the infrastructure to ingest, standardize, validate, and understand that data first,” DiCaprio said. He said Accelerant’s lack of legacy infrastructure allowed it to build the exchange around data from the start. He sees the next stage as agentic AI, which he described as systems that move beyond organizing information to interpret it, making decisions within defined parameters and taking action.
DiCaprio credited the traditional carrier model with creating controls, governance and financial stability around underwriting risk. Over time, he said, those structures can also put distance between the people who know a risk best, the information they need and the capital behind them. Accelerant’s approach places authority with specialist underwriters and connects them to long-term risk capital through the exchange.
“The data gives us visibility across that system without requiring layers of traditional handoffs. That means specialist underwriters can move really fast while the risk exchange continuously understands what’s happening across a much broader and robust portfolio,” he said.
Among MGA partners, DiCaprio said, technology has removed a great deal of friction but has never been a substitute for underwriting discipline. “The best specialty underwriters have always deeply understood their niches – most of them are 10 inches wide and a mile deep in that specific space. They know their appetite really well and exercise judgment. That doesn’t disappear with AI. It becomes the foundation AI builds upon,” he said.
“The future is technology making great underwriting discipline scalable.”
The opportunity, in his view, lies in encoding that expertise into systems that learn continuously from exposures, pricing, claims and portfolio performance, shortening the feedback loop between what an underwriter believed about a risk and what actually happened.
The approach sits alongside Accelerant’s shift toward a capital-light business model. The company reported exchange written premium of $4.19 billion for 2025, up 35% year over year, and third-party direct written premium rose to 41% of the total in the first quarter of 2026 from 19% a year earlier. DiCaprio said that shift changes the questions Accelerant asks when evaluating new program partnerships.
“Our role increasingly isn’t simply deciding whether Accelerant wants to retain a particular risk. We can ask: Is this great underwriting? Do we understand the risk? Do we have the data to monitor it? How does it fit within the portfolio? And what capital is best suited to support it?” he said. “The underwriting discipline doesn’t go away. In fact, understanding risk becomes even more important when you’re connecting it with third-party capital.”
DiCaprio said the industry’s AI transformation is still early but moving quickly. The first wave, he said, has largely helped people work faster by summarizing information, querying data and automating tasks. The next phase embeds AI directly into operations, interpreting incoming data, monitoring portfolios, flagging anomalies and routing work, a direction reflected in specialty insurer CFC’s pilot of an agentic underwriting system. “Agentic technology takes that another step. The system can understand what is happening, determine what should happen next, and then take action within defined authority and parameters,” he said. Humans remain essential for judgment, relationships, creativity, and complex exceptions. For brokers and policyholders, technology itself isn’t the point. The outcome should be a faster, smarter, more responsive insurance market.