Specialty insurance has been one of the market’s growth stories, and Asia has been part of that expansion. Lloyd’s alone writes around US$10bn of premium in Asia Pacific, growing at just under 10% a year, its chief executive said last year. But its Singapore-based Asia Scheme was broadly flat in 2025, ending four years of growth, as financial and professional lines rates in Asia fell for a twelfth consecutive quarter, according to Marsh.
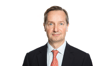
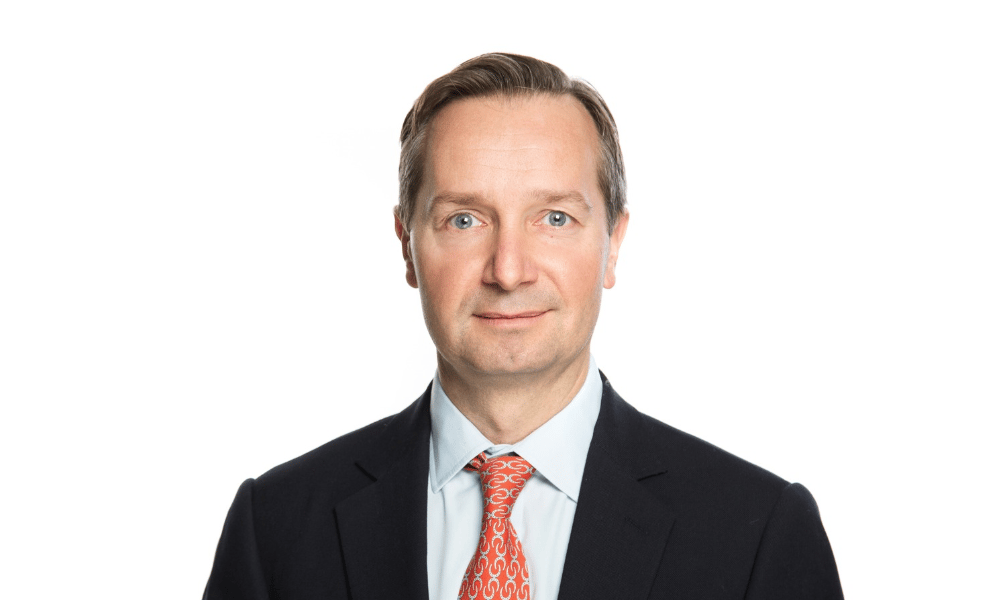
Carl Bach (pictured), head of international business in the UK at The Hartford, believes demand is being driven by increasingly complex risks, shaped by the macroeconomic and geopolitical environment.
“Asia’s growth reflects the fact that clients want specialised expertise delivered closer to where they operate,” Bach said.
He pointed to cyber, D&O, and power and renewables among the lines growing rapidly in Singapore. As local capacity and expertise develop, he argued, brokers and their clients benefit.
He does not see that as a threat to London, which he expects to remain “one of the world’s premier specialty insurance centres”. The London market’s total premium came to £104.8bn in 2024, according to the International Underwriting Association, and Bach said London’s scale, across open market, MGA, binder and coverholder business, is hard to compete with. He sees Singapore, Hong Kong and Shanghai playing an increasingly important role in regional insight and local access.
The question of staying power is sharpest in classes such as D&O and financial lines, which swing between hard and soft markets. Bach sees the market as transitioning, with the picture varying by product. In the UK, Marsh’s data showed commercial rates overall falling 8% in the second quarter of 2026, and brokers expect the soft market to plateau by the end of the year, according to a survey by Ascend Insurance Holdings.
As carriers invest in automated quoting and digital placement, speed is becoming easier to match. Bach sees the greater opportunity in improving the information behind placement and underwriting decisions.
Cargo, one of the oldest lines in the market, shows what is at stake. Bach said the supply chains it protects have never been more complex, and information has typically sat across emails, spreadsheets and shipping documents. He argued the real value of digital platforms lies not in making paper forms electronic but in giving brokers, underwriters and clients better visibility into risk and faster access to the information behind their decisions. He is also wary of forcing brokers down a single route, pointing to a mix of direct APIs and market placing platforms such as Whitespace and PPL.
“If technology can accelerate quote turnaround times, then the value can shift from processing transactions to providing insight,” Bach said.
Technology can inform underwriting, Bach said, but competitive advantage will increasingly come from insight and market knowledge. He expects The Hartford’s underwriters to use the time saved to help clients understand complex risks and find better long-term solutions.
If specialty’s growth is to outlast the soft market, it may depend less on how much capacity arrives than on how much of it comes with the expertise to stay.