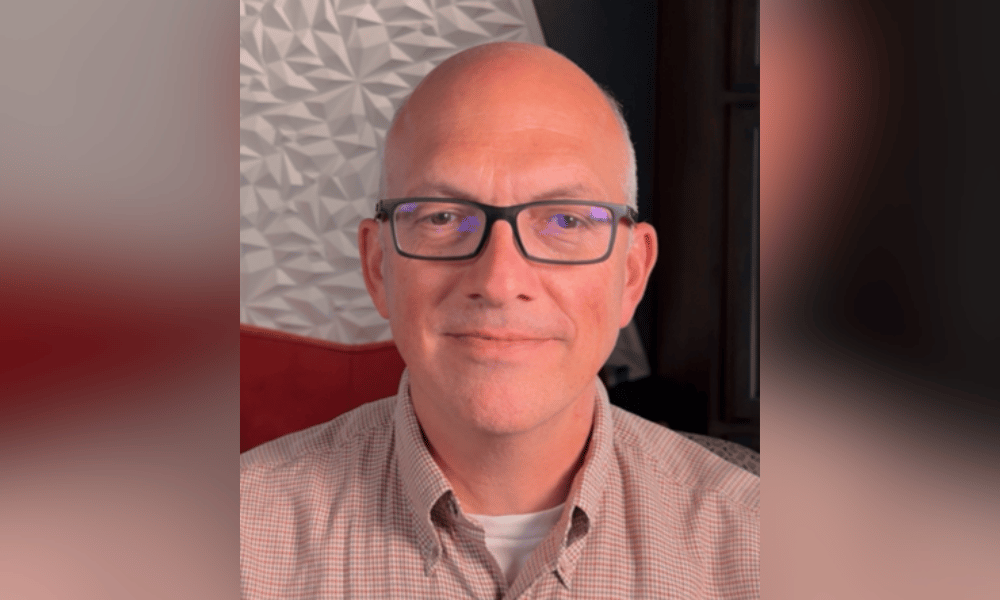
The group benefits industry is deploying artificial intelligence faster than it is preparing its people to work alongside it and according to Craig Weber, head of insurance strategy at Cognizant, that gap may be the single biggest risk brokers and carriers face right now.
Weber, a 30-year insurance industry veteran who presented at InsureTech Connect (ITC) Las Vegas this month, told Insurance Business Benefits US that while AI adoption across group health, voluntary benefits, and stop-loss has accelerated, most of the industry has yet to bring the technology into the beating heart of insurance: claims and underwriting decisions.
"The industry maturity is relatively uniform in that most people started with efficiency plays around IT," Weber said. "Most folks have not progressed very far in bringing AI into the core of claims and underwriting. That's not where most people are yet."
Weber says that the carriers and administrators who have moved from pilot to production share a sense of urgency around improving the experience for brokers and employer plan sponsors.
The broker channel, he said, is a particularly strong opportunity because so much can be done to smooth administrative friction without breaching regulations.
However, while regulators say they want AI to be used, they are simultaneously uncomfortable with the non-deterministic nature of large language models; the inability to guarantee the same output from the same inputs.
"If you can't audit a decision and you can't reliably get to the same decision with the same inputs, that's a real problem from a regulatory standpoint," Weber said. "As long as you stay short of making the actual decision, I think there's a lot you can do without running afoul of regulation."
The benefits enrollment process is one of the clearest illustrations of that principle. It involves heavy unstructured data exchange upstream of any coverage decision which is exactly the kind of work AI can organize quickly and safely without triggering regulatory concerns over automated decision-making.
Cognizant's own research, published in its August 2026 report Cognitive Debt and the Erosion of Insurance Expertise - a survey of 542 director-and-above insurance leaders - found that 62 percent of insurers are already scaling or maturing AI in production.
The survey found that the primary driver of that adoption is not cost reduction but better decision quality, cited by 47 percent of respondents, followed by improved customer and distribution experience (46 percent) and speed in underwriting and claims (45 percent).
Weber frames AI-assisted decision-making as a four-step sequence: organize, research, recommend, and then interrogate and decide. The first two belong to AI.
"Those last two - interrogation of the recommendation and deciding - are the human element," he said. "That's where judgment comes in and where you need someone accountable."
This framework has direct implications for benefits brokers, whose value proposition rests on confidence and the advisory relationship. Reducing the human role risks undermining the very reason employers retain a broker at all.
"Why people use brokers, why people rely on human experts, is for the confidence," Weber said. "Otherwise you could sort out these issues on your own. It would just take a lot of research and you would never have that feeling like, hey, an expert has looked at this."
The interrogation step is where Weber believes the industry needs the most work. When a large language model produces a clean output, not every user realizes they are obligated to push back on it - to ask whether all options were considered, whether the right question was even answered.
"Not everybody knows that they're on the hook to do that," he said. "The job is not done when the LLM spits out an answer. It really should be the start of a process, not the end."
On disclosure, Weber said full transparency is best practice. Users typically detect AI interaction quickly regardless, and the risk of non-disclosure outweighs any perceived benefit.
Beyond regulatory exposure, Weber flagged an underappreciated risk already operating inside most organizations: shadow IT, where employees use personally paid AI tools outside corporate controls to structure their work and make decisions.
"If you think about how people personally use AI, they are going off on their own, probably using a tool that they pay for personally, not even their company's paying for, and they are making decisions and structuring their work using those tools," Weber said. "That raises a real risk to their employer."
His says that employers should address shadow IT by offering compliant, controlled AI tools internally, rather than allowing ad-hoc personal tool use to proliferate unchecked.
For benefits brokers advising employer plan sponsors on Affordable Care Act (ACA) compliance, Employee Retirement Income Security Act (ERISA) obligations, and fiduciary standards, the compliance and data exposure risk is acute.
The focus of Weber's ITC session was not about what AI is doing for insurance, but what it may be doing to it.
Cognizant's August 2026 study introduced a concept it calls cognitive debt: the erosion of human capability that occurs when people rely on AI as a substitute for their own expertise. Like financial debt, it is easy to accumulate and hard to discharge.
The research found that the overall Cognitive Debt Index (CDI) across 542 insurance leaders stands at 3.48 on a five-point scale - above the midpoint on all four dimensions measured: skill atrophy, judgment deference, declining agency and initiative, and automation bias. Fifty-seven percent of leaders surveyed fell in the high-debt bands, a score of 3.5 or higher.
Critically, this is not a future concern. Ninety-six percent of insurance leaders surveyed said they had already personally observed signs of cognitive debt in their organizations.
Fifty-eight percent reported staff who had lost the ability to do the work AI now handles. Fifty-two percent had seen staff accepting AI output without meaningfully reviewing it. Forty-nine percent said staff could not explain the reasoning behind their AI-assisted decisions.
The study also surfaces a troubling paradox: the firms reporting transformative AI productivity gains show higher cognitive debt than everyone else - a CDI of 3.58 versus 3.43 among those with more modest gains. The most successful AI adopters appear to be accruing debt the fastest.
"We have spent so much time chasing the technology solution and piloting it six ways to Sunday, but we haven't taught humans how to incorporate that and what it might be doing to their own decision-making," Weber said. "It's a much more thoughtful conversation that needs to happen."
The study, which draws on academic research into cognitive offloading, transactive memory, and automation complacency, also found that the people most worried are the ones who understand AI best. Technology and information technology leaders scored highest on the CDI at 3.70 — the sharpest feel for the machine's limits tends to come from those who understand it most closely.
Walking the exhibit hall at ITC Las Vegas, Weber photographed vendor booths and fed the images to an AI tool to characterize what the show was about. The clear winner was agentic AI.
"Most of the more compelling content there was about efficiency gains," he said. "It wasn't about replacing humans at all. It was about making your underwriter 80 percent more efficient."
Recently, MetLife’s US leader Ramy Tadros spoke with IBB and shared the impact AI has made on his team’s productivity, highlighting MetLife's structured settlements business where AI has eliminated 80 to 90 percent of the manual, paper-heavy processing work that previously consumed advisor time. The result, he said, is faster turnaround, faster speed to market, and advisors freed up for higher-value client conversations.
For benefits brokers and carriers, Weber’s near-term recommendation is to head toward fully automated decision pathways as a long-term end state - while keeping humans firmly in charge today and using AI to drive out cost and efficiency gains along the way.
His single biggest caution for the benefits brokerage market is complexity. Too many AI tools, too much vendor marketing, and too little clarity are slowing informed adoption. Long-term strategic decisions should not rest on present-day assumptions about token costs or provider economics in a market Weber describes as a wild frontier.
"I don't know that we've ever had a technology that was self-reinforcing and creating like AI," he said. "A new model every three weeks is shocking."