Hurricane Isaias is putting an abrupt end to an extraordinarily quiet Atlantic hurricane season and raising questions over whether months without a hurricane have left some homeowners less prepared for a major loss.
Isaias became the first Atlantic hurricane of 2026 late Wednesday and was continuing to strengthen Thursday as it moved toward the northern Gulf Coast. By Thursday morning, maximum sustained winds had reached around 80 mph, with landfall expected late Friday or early Saturday along the Florida, Alabama or Mississippi coast.
The storm comes after more than four months without an Atlantic hurricane. The lull was largely attributed to a powerful El Niño, and NOAA had previously forecast a 75% chance of a below-normal season. In an event update on Isaias, Marsh Re noted hurricane activity during El Niño years can shift toward the Gulf Coast and subtropical Atlantic, leaving significant concentrations of insured property exposed even when basin-wide activity is suppressed.
Marsh Re also reported heavy rainfall over already saturated ground could make inland flooding a major loss driver, with rainfall totals potentially reaching eight to 12 inches east of landfall and much higher localized totals. Tornado exposure could also extend hundreds of miles inland as the system moves north.
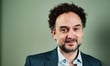
For John Sence (pictured), chief sales officer SageSure, a Managing General Underwriter (MGU) and third-party administrator specializing in catastrophe-exposed, high-risk property insurance markets, the quieter hurricane season brings up concerns that policyholders have become more willing to trim protection after several years of rising insurance costs.
“It’s understandable that some clients are looking for ways to reduce their premiums,” said Sence. “A quiet season can make it easier to question whether certain coverages are still necessary.”
He urged agents and brokers to seize the opportunity to revisit deductibles, flood coverage and the potential cost of a prolonged recovery.
“Conversations about deductibles, flood coverage, and recovery costs are most effective before a storm is on the horizon,” Sence said, noting that the biggest claims risks is “the difference between what policyholders think their insurance covers and the protection actually contained in the policy.”
He explained: “Many clients don't realize that a standard homeowners’ policy generally does not cover rising water, and flooding can occur well beyond coastal communities and designated flood zones.”
Recovery expenses can create another gap. Power outages, shortages of contractors and supply-chain disruption can lengthen the period before homes and businesses return to normal, placing more importance on additional living expense and business interruption limits.
In a separate event report on the storm, Gallagher Re said historical losses from Category 1 and Category 2 landfalls and the exposures currently in Isaias’ path suggest insured losses could reach the low to mid-single-digit billions. Despite that potential bill, the reinsurance broker said ample reinsurance capital means the event is unlikely to materially change January 1 renewal discussions.
Sence doubts one hurricane would reverse broader softening trends in the property insurance market. “It could, particularly if losses are severe and concentrated in a region,” he said. “The impact depends on the size of the losses, who absorbs them, and how capital providers respond afterward.”
For now, he said, agents have a key role to play in identifying clients who have reduced coverage, taken higher deductibles or underestimated flood and recovery costs during a year in which the Atlantic gave them few reminders of what hurricane exposure can look like.
“Hurricane risk isn't determined by how quiet a season has been so far. It only takes one storm affecting your community to make it a significant season for you,” Sence said. “A quiet season is welcome, but it doesn't change the underlying exposure. The homes are still there, and the cost to rebuild them hasn't gone away.”