As much as 40% of catastrophe claims resources available in 2024 could no longer be deploying by 2027, according to a senior claims executive, as new labor data points to a sharp contraction in the US claims workforce.
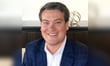
Andrew McCallum (pictured), Vice President, Specialty Operations at Sedgwick, said the potential loss of experienced catastrophe adjusters is arriving just as insurers are having to spread claims resources across a wider range of perils and locations.
“From 2024 to 2027, we're talking about about 40% of resources are no longer going to be deploying on CAT,” McCallum told Insurance Business. “The diminishment of not only the resource but also the knowledge base is going to be significant.”
The Jacobson Group's September 2026 Labor Market PULSE, drawing on Bureau of Labor Statistics (BLS) data, showed employment in claims was down 20.9% year over year in July, a substantially steeper decline than in other major insurance segments. Property and casualty employment fell 1.7% over the same period.
The latest BLS occupational projections also point to a smaller claims workforce over the longer term. There were approximately 376,100 claims adjusters, examiners and investigators in the US in 2025, with employment expected to fall 5% to around 355,500 by 2035.
Across the broader category of claims adjusters, appraisers, examiners and investigators, BLS expects approximately 21,600 openings a year, but says all of those openings will come from the need to replace workers who change occupations or leave the labor force, including through retirement.
For catastrophe claims, McCallum said the issue goes beyond replacing headcount. The industry is also at risk of losing adjusters with direct experience responding to some of the largest disaster events in US history. He pointed to hurricanes Harvey, Katrina, Sandy and Hugo as examples where experienced claims professionals were needed to manage enormous volumes of losses under difficult conditions.
“Those are the memorable events that you need the folks that can go there and manage to those things,” he said. “Are they going to be available?”
The workforce contraction is coinciding with a shift in how catastrophe resources need to be deployed.
“Historically, CAT planning was heavily focused on hurricanes. You could concentrate resources in one place and work backwards from there,” he said. This model is becoming less viable as different catastrophe events increasingly have the potential to compete for the same pool of adjusters.
“Now you have to be much more strategic because you could have a wildfire in the Northwest, a hurricane in the Southeast and other major events happening at the same time,” McCallum continued.
This now creates different kind of capacity problem for insurers. An adjusting organization may have a large national workforce on paper, but several simultaneous catastrophes can quickly create competition for specialists in property, flood, wind or complex commercial losses.
The changing environment puts greater importance on agreeing claims resources before a catastrophe occurs. Insurers need realistic discussions with adjusting partners about how many people can actually be committed to an event, particularly if claims teams are simultaneously responding elsewhere.
For brokers and risk managers, the issue may also make the claims infrastructure behind an insurance policy more important during carrier selection. The question is not simply whether an insurer has a catastrophe response plan, but whether it has access to enough experienced adjusters if several major events occur at once.
At the same time, digital tools are helping to make a smaller claims workforce more productive.
BLS expects automation, faster data processing and AI to handle more of the work historically performed by claims professionals, including evaluating photographs of damaged property and calculating estimated claim amounts.
At Sedgwick, McCallum said technology is already helping catastrophe teams decide where scarce human expertise should be deployed. The firm uses catastrophe modeling and AI after events to assess population density, wind speeds and different types of damage across an affected region, which can enable teams identify where flood, wind or commercial claims specialists are most needed.
“Digital tools, virtual tools and portalized claims can make a huge impact. If customers can upload photos or estimates instead of calling and sitting on hold, you’re moving in seconds rather than days or weeks,” he said.
“In the cat space, giving someone a portal where they can see who their adjuster is, who’s making decisions and where to submit information can be the difference between a great experience and a poor one. I’m a true believer in virtual assist and measuring tools.”
But he also cautioned against treating technology as a straightforward replacement for departing adjusters: “We’re introducing more digital tools from a risk mitigation standpoint, but the challenge is that many of them still haven’t been implemented at scale.”
“The question is: what can we actually use at scale, and what creates too steep a learning curve for people on the ground? If I’m moving 1,000 people into a wildfire zone, I’m not going to teach them a GIS mapping program overnight.
“That’s why we’re using sandboxes now, so people understand how the information is gathered and how these tools can help us put the right people in the right place, doing the right work, and ultimately improve outcomes.”