Kinsale Capital Group reported a 30% drop in net income for the third quarter of 2026, and almost none of it came from underwriting. Net income fell to $98.1 million from $141.6 million a year earlier, but $37.6 million of that decline was a pre-tax loss from a deliberate repositioning of the investment portfolio, a move the company said had no impact to book value. Strip it out and net operating earnings rose 5.9% year-over-year to $128.3 million, with a combined ratio of 75.4% versus 74.9% in Q3 2025.
What the results actually show is a company making a pointed choice about where it will and will not compete, and that choice has direct consequences for what E&S brokers can expect when placing commercial property risks with one of the market’s best-capitalized specialty carriers.
Gross written premiums fell 4.8% year-over-year to $462.9 million, and the source of the decline is specific. Premiums across Kinsale’s property divisions fell 19.3% in Q3. The steepest decline came from the commercial property sub-division, which writes larger layered accounts and was down 26.8%. Casualty, by contrast, grew 0.9%. This is not a market that moved against Kinsale. It is Kinsale’s underwriting discipline moving against the market.
“We continue to produce exceptional underwriting margins and strong investment income,” said CEO Michael P. Kehoe, framing the results as a function of discipline rather than growth.
The pattern has been consistent across multiple quarters. In Q2 2026, competition in the E&S property market cut into Kinsale’s commercial property division premiums by 32.7%, even as overall earnings rose. The Q3 figure of 26.8% represents a slight narrowing of that contraction, suggesting the rate of decline in property volume may be leveling, but not reversing.
The broader E&S market context explains why. According to the Wholesale & Specialty Insurance Association’s (WSIA) 2026 midyear report, the E&S lines market is splitting along two tracks: property and select professional lines are easing, while commercial auto, umbrella and general liability continue hardening. Kinsale’s numbers are a single carrier’s confirmation of that divide. The appetite for E&S commercial property is narrowing precisely where it was widest two years ago, during the hard market peak.
Casualty growth of 0.9% in Q3 looks modest but is the steadier part of the business. Net earned premiums rose 3.0% to $423.5 million, and net investment income climbed 17.5% to $58.3 million, driven by portfolio growth from operating cash flows. The company’s investment portfolio held $5.5 billion in cash and invested assets at September 30, up from $5.2 billion at year-end 2025.
The investment repositioning that depressed headline net income was a tactical move. Kinsale simultaneously sold lower-yielding fixed-maturity securities at a loss and reinvested in higher-yielding bonds, while also rotating into higher-conviction equity positions. The company stated there was no impact to book value from the transaction, and the long-term yield improvement was the stated rationale.
One structural feature of the results worth noting: prior accident year reserve releases of $19.7 million contributed 4.5 points of favorable development to the Q3 loss ratio, versus $15.8 million and 3.7 points in the prior year period. The reported combined ratio of 75.4% reflects that release. The current accident year loss ratio, before prior-year development, was 57.9% including catastrophe losses, a more modest figure but still well within Kinsale’s historical range.
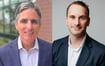
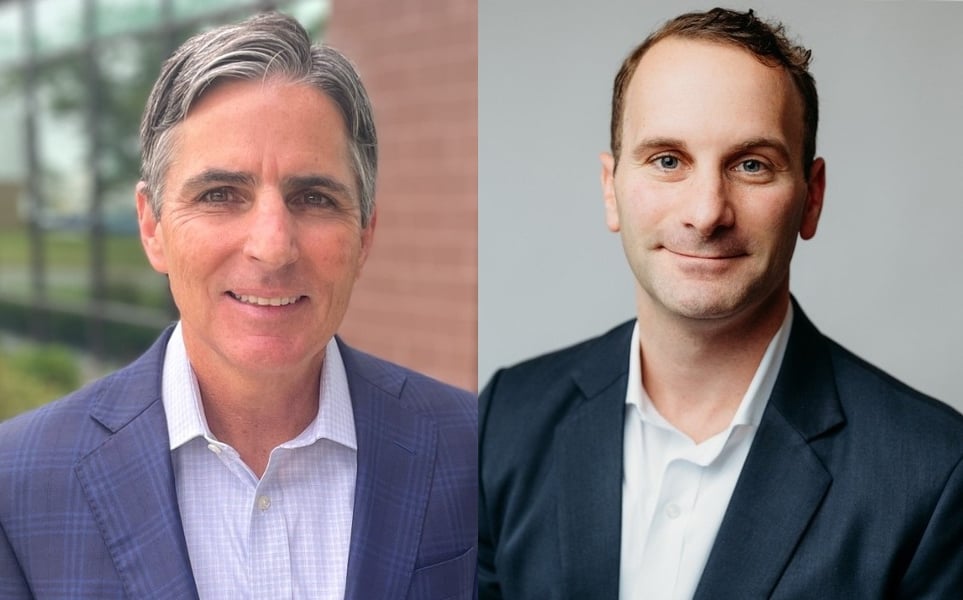
Kinsale announced separately that Bryan P. Petrucelli (pictured, left), who has served as chief financial officer since the company’s founding in 2009, will retire from his executive role on March 2, 2027. He has been simultaneously elected to the company’s board of directors. His successor, Christopher R. Tangard (pictured, right), has served as chief accounting officer since March 2024 and joined Kinsale in 2019. Prior to Kinsale, Tangard was a senior manager in the audit practice of KPMG LLP.
The transition is orderly and internally sourced. Petrucelli’s elevation to the board means his institutional knowledge of the company’s capital structure and reinsurance strategy remains available to leadership. Tangard, for his part, has spent seven years inside Kinsale’s financial operations, rising through internal audit and finance roles before taking the top accounting position. Kehoe’s statement positioned the handover as continuity rather than change: “He understands how our technology-enabled, cost-efficient business model drives our success,” Kehoe said of Tangard.
What the combined picture from earnings and the CFO announcement describes is a company managing a deliberate transition in its property mix while sustaining underwriting margins that most of the industry would struggle to replicate in a hard market, let alone a softening one.