What happened: A lawsuit alleges a dementia patient wandered into an unlocked walk-in freezer at a Florida assisted living facility, became trapped, and died. The facility landlord's insurer now says its policy was never meant to cover patient injuries.
Who's involved: Kinsale Insurance Company (surplus lines insurer) and HB Rubicon LLC (facility landlord).
What's at stake: Kinsale wants a declaration of no coverage, no duty to defend, and reimbursement of the defense costs it has already paid.
Why it matters: Landlords leasing to healthcare operators may find their commercial liability policies exclude the very injuries most likely to occur on the premises.
Where it stands: Declaratory judgment complaint filed October 8, 2026, in federal court in Tampa.
A walk-in freezer with an unlocked door. A dementia patient who wandered in and could not get out. A death that the landlord's own insurer says falls outside the policy.
That is the scenario at the center of a new federal lawsuit filed by Kinsale Insurance Company in the US District Court for the Middle District of Florida. Kinsale, a surplus lines insurer - a carrier that covers risks too specialized or high-exposure for the standard market - is asking the court to confirm it has no obligation to defend or pay claims on behalf of the facility's landlord, HB Rubicon LLC. It also wants back every dollar it has already spent on the landlord's legal defense.
The underlying lawsuit, filed in May 2026 in Pasco County circuit court, alleges that the resident was an "in-patient" at The Waverly Assisted Living & Memory Care, a facility operated by Wellness Center of Trinity LLC. According to that complaint, the resident suffered from dementia, confusion, and "significant cognitive impairments," and had a documented tendency to wander into areas he was not permitted to enter.
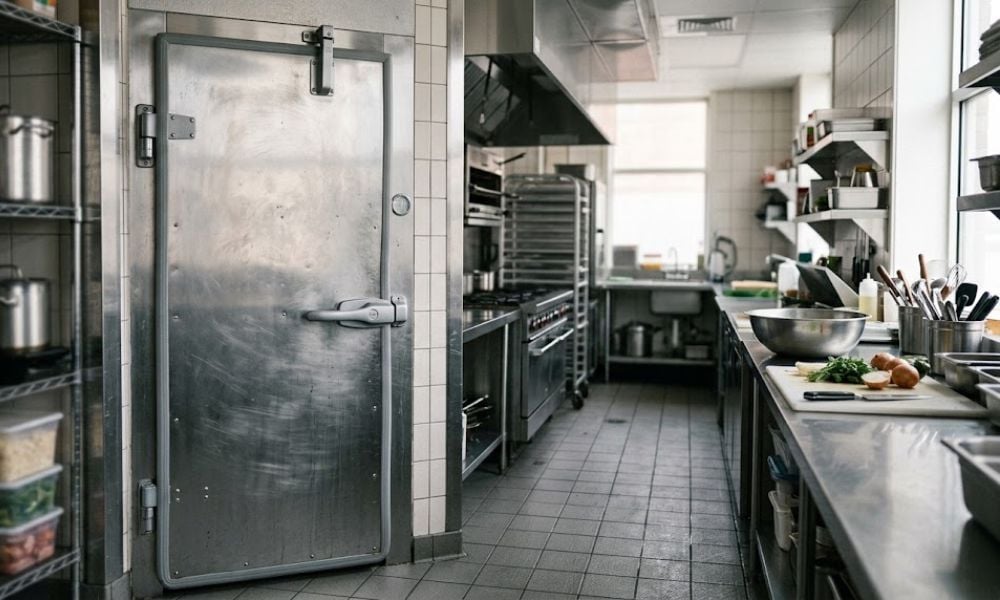
On September 26, 2025, the filing alleges, the resident wandered unattended through the facility, reached an allegedly unlocked kitchen, entered a walk-in freezer, and became trapped. He suffered severe hypothermia. He ultimately died.
The underlying suit names HB Rubicon - the company that owns the property and leased it to The Waverly's operator - as a defendant. It alleges HB Rubicon knew the facility would house vulnerable adults and owed them duties of care, including keeping the premises in a reasonably safe condition, preventing dangerous conditions, and warning residents of hazards. The complaint also alleges HB Rubicon failed to provide appropriate "care… assistance, shelter, supervision, and medical services."
HB Rubicon held a commercial general liability (CGL) policy with Kinsale, effective from February 19, 2026 to February 19, 2027. The policy was written on a claims-made basis, meaning it covers only claims first made and reported during the policy period, rather than any incident that happens to occur while the policy is active. The schedule described the risk as "Medical buildings - Lessor's Risk Only" - in other words, the policy was designed to cover HB Rubicon's exposure as a property owner, not the clinical operations of its tenant.
The policy carried an endorsement titled "Exclusion - Injury to Patient or Resident." It excluded coverage for any bodily injury or damage "arising directly or indirectly out of, related to, or in any way involving" any patient or resident of the scheduled premises, or anyone receiving health care or services there.
Kinsale says that exclusion fits squarely. The resident was an in-patient. The injuries arose at the insured premises. The policy, as Kinsale reads it, was never designed to cover this kind of claim.
The insurer also points to a second exclusion covering injuries that arise from the rendering of - or failure to render - health care services, supervision, or treatment. It cites the underlying complaint's own language alleging HB Rubicon failed to provide adequate care and medical services. And a separate endorsement goes further: where the policy provides no coverage, it says, there is no duty to defend.
Kinsale is not just seeking a declaration that it owes nothing going forward. It wants HB Rubicon to reimburse the defense costs Kinsale has already paid.
Here is why: when the underlying lawsuit landed, Kinsale agreed to fund HB Rubicon's defense, but it did so under what is called a reservation of rights - essentially a written notice that says "we will pay your lawyers for now, but if it turns out the policy does not cover this, we want the money back." HB Rubicon accepted those terms, according to the complaint. Kinsale has been fully funding the defense since.
The complaint cites Florida federal court precedent supporting an insurer's right to recoup those costs where it defended under a full reservation of rights and coverage is ultimately found not to exist.
One detail the filing itself flags: the policy lists the facility address as being in New Port Richey, Florida, while the underlying complaint and lease identify the same address in Trinity. Kinsale's own filing notes both refer to the same premises.
The case puts a sharp question to claims professionals and underwriters writing CGL policies for landlords of healthcare-adjacent properties: if the policy excludes all patient and resident injuries, and the premises is an assisted living facility, what exactly is left to cover?
None of the allegations in the underlying lawsuit have been tested in court, and no judge has ruled on the merits of Kinsale's coverage position.