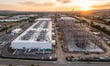
Data centre construction in Canada reached $4.6 billion in 2025, according to Gallagher's 2026 Mid-Year Canadian Construction Industry Trends report, and is projected to grow to $8.6 billion by 2031. Projects commonly exceed $5 billion to $15 billion in value. Lender requirements and insurance capacity are both being tested at the upper end.
"These aren't just technology projects anymore," said Mike Hergott, SVP and national practice leader for construction at Gallagher, at a recent Insurance Business Canada construction insurance power panel. "They're massive construction power risk transfer discussions that need to take place very much earlier."
The scale shift matters in practical terms. Todd Henderson, SVP of Aon's construction and infrastructure practice, put it plainly. "A $1 billion data centre project is really at the smaller end of the scale of what we're seeing." He described a placement his team profiled at a London conference in June - a US data centre that required US$10 billion in capacity with 75 insurers on the slip.
The capacity, in short, exists. But accessing it requires a fundamentally different placement approach than a standard builder's risk submission.
Both panelists were clear that the traditional placement sequence - build the submission, approach the market, negotiate terms - does not function at this scale. Carrier engagement has to begin far earlier, the technical presentation has to be of a different quality, and the program structure itself may need to move away from conventional builder's risk altogether.
"My perspective here is that the visibility on the project is very important," Hergott said. "And not necessarily that the capacity becomes a complete challenge to us, but it's how we engage the markets. It's a little bit more engineered in terms of the approach to engaging the carriers."
Henderson made the same point in terms of what markets require to say yes. "The capacity's there. It does have to be presented to markets, though, in a way that makes sense. Those studies around maximum loss, properly engineering it, properly understanding the technical risk and such, and presenting that to markets in a way that makes sense for what are mega-projects - is key to success in obtaining that capacity."
The PML analysis Henderson references is not optional at this scale. Industry reports indicate that many data centre projects are insured for only one-third to one-half of their total value - not because owners are unwilling to buy more, but because at the upper end of the value range, full-value insurance is simply not available in the market. PML methodology allows the risk to be sliced so that primary insurers carry the lower layers while owners retain or self-fund the top end. Presenting that structure coherently to domestic and international carriers simultaneously is what the placement engineering Hergott describes actually means in practice - and it is a capability that not every broker operating in the construction space currently has.
The major hyperscalers building globally are not passive buyers of insurance. With the balance sheet depth of a major tech firm and the sophistication to evaluate when retention is more efficient than transfer, captive structures are a live consideration for the largest players - and the dynamics playing out globally will eventually reach Canada.
Henderson drew the parallel to a cycle he experienced directly. "It reminds me a bit of the go-go years in oil and gas in the early 2010s. The scale of the projects then were refinery projects of $8 billion, $10 billion US dollars. And what the super majors used to do in oil and gas was, for them, risk transfer was a question of what's the most efficient use of my capital? So, a question of cost of capital."
Those same firms now building data centre campuses are applying identical logic. "We're seeing that too with some of these major tech firms with these very, very large, very robust, cash-heavy balance sheets, as well as the sophistication to understand when they want to retain a risk and when they want to transfer it."
Whether that dynamic has reached the Canadian market yet is a more cautious answer. "So far it's not something that we've seen per se," Henderson said - but he was clear that the arrival of certain players would change it. "When certain players come into the Canadian market, there will absolutely be a captive play."
Hergott's characterization of where Canada currently sits is precise: "Emerging at best. Very early." The implication for Canadian brokers is that familiarity with captive structures and large-scale retention strategies needs to be built before those conversations arrive in a client meeting, not during them.
The capacity conversation dominates discussion of data centre construction risk. Both panelists flagged a secondary exposure that attracts less attention and carries significant long-term consequence.
Data centre construction commands a disproportionate share of available construction labour in every geography where it is active. When that pool is stretched - and in many Canadian markets, it already is - construction quality tends to follow.
"We see this when there's been various booms over the construction industry and certain development," Hergott said. "There's a mobility of labour, certainly, but there's not an indefinite pool of that. And when we get strained, when we have people maybe pushing a little bit further than they otherwise would have, we do see quality concerns generally follow that."
The stakes in a data centre context are higher than in most construction categories. These facilities need to operate at 99.999% uptime. The consequences of a construction quality failure that only manifests during operations - in cooling, fire suppression, or structural integrity - are not measured in repair costs alone. They are measured in business interruption claims, SLA penalties, and reputational damage to the facility operator.
"How are we looking at that from our performance exposure with the contractors that are hired?" Hergott said. "Those quality concerns could be something lurking around the corner here, particularly with how these end assets are utilized and how resilient they need to be."
The coverage transition between construction and operations adds a further layer. Builder's risk policies terminate at substantial completion. The equipment-loaded campus then moves to a separate operational property program. Getting that transition right - with no gaps and no ambiguity about which policy responds to a loss straddling both phases - is a placement discipline the market is still developing at scale. For brokers active in this space, it is the question that will define program quality long after financial close.