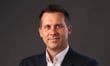
Black box insurers make plenty of promises. The data is secure, it won’t be sold to third parties, and it won’t be used to report drivers to the police for minor speeding. The trouble, according to Andrew Brown-Allan (pictured), chief growth officer at telematics firm IMS, is that customers rarely see any of them.
“Of course we’re not going to give your data to the police if we spot that you’ve gone 34 in a 30. These are all things that live in the small print,” he said.
Brown-Allan agrees with Cambridge Mobile Telematics chief executive Bill Powers, who argued last month that black box insurance has a trust problem, though he does not see trust as the only barrier. In his view, insurers could do much more to fix it, starting with bringing those promises into the open and perhaps collecting less data.
Insurers carried a trust problem long before telematics, from years of price walking before the FCA banned quoting renewing customers more than new ones from January 2022, to claims that dragged on or paid too little. Brown-Allan sees that problem amplified in black box insurance, since a pitch that data might lower the premium is heard as one that might raise it.
That is despite telematics offering something fairer than the proxies insurers rely on. A clean claims record, he noted, can sit alongside very poor driving. “It’s no kitemark, but nonetheless, it’s the only indication most insurers have got as to whether someone’s a good driver. They might just have been lucky and had a tonne of near misses.”
Take-up remains low, and part of the problem is the product itself. “You wouldn’t pay Spotify £20 a month and not expect to hear any music,” Brown-Allan said. Car insurance is a grudge purchase that many drivers pay for monthly and hope never to use. IMS’s research last year, a survey of more than 5,000 drivers across the UK, US, Canada, Germany and Australia, found that 23% of respondents had ever used a usage-based policy that tracked their driving, and 42% were aware of the product. In the UK, Brown-Allan said, telematics remains below 10% of all motor policies.
The same research suggests customers notice what is missing. After lower premiums and pricing based on actual driving, transparency in how data is used ranked third among the features respondents wanted, with more control over costs fourth. Data security ranked second or third among their concerns, something Brown-Allan said he had not expected, though he put it down to the steady run of corporate data breaches.
Insurers tend to treat security as a given, Brown-Allan said, assuming customers will take it as read that a heavily regulated firm, bound by compliance rules and GDPR, keeps their data under lock and key. If insurers want customers to share more than their age, postcode and car, assurances like that need spelling out.
The same applies after a crash. Respondents were most comfortable sharing mileage, followed by collision data, which Brown-Allan compared to drivers paying £200 to £300 at Halfords for a dashcam to prove they were not at fault. The same data can prove fault too, and customers should be told that plainly.
The other part of his answer is to change who holds the data. In the model he describes, a driving score is generated on the phone, in the background of an insurer’s existing app. It is shared at quote or renewal, or never, if the driver feels it is unfair. Second-by-second GPS data on every journey no longer has to flow to the insurer. “It doesn’t feel like a one-way mirror. It feels like nothing has to leave this device,” he said.
Cost has also held telematics back. Fitting a black box cost insurers about £120 in the first year, Brown-Allan said, which made sense on an £1,800 premium but not on mid-market policies. An app with a windscreen beacon brought that to around £30, and he expects processing on the phone, without the beacon, could take it closer to £1 per customer a year. At that price, telematics can reach drivers paying £500 to £600, for whom a £75 to £100 discount may not seem worth the hassle on its own. For those drivers, it can also bring crash detection, roadside assistance, coaching and rewards rather than discounts alone.
The insurers that have run telematics longest have tended to want ever more data on the customers they already have, and Brown-Allan is not convinced that is the answer. “I think the ones that will win will be the ones that collect and use less data across more customers in a more powerful way, because that’s the value exchange.”
A score held on the phone could also travel. Brown-Allan expects drivers may eventually be able to shop their driving score around the market as they do their no-claims discount, to get a better price on a standard policy.
Brokers led much of the early telematics innovation in the UK from around 2010 to 2015, he said, before capacity changes and the rise of direct writers such as Admiral and Hastings, which took a large share of the market. “What’s the role of a broker? Is it just to ship your risk around the market, get the cheapest price?” he asked. For most personal lines customers, he acknowledged, that is exactly why they use one. But he sees a role in steering them to products that reward safer driving and settle claims faster.
He pointed to the US, where agents can take the path of least resistance to the cheapest standard product, but the ones that build lasting relationships help customers onto the right product.
More than a decade after telematics was tipped to go mainstream, the products most likely to get there may be the ones that ask customers for less and tell them more.