Legal & General plans to reduce its workforce by around 1,000 roles, about 10% of staff, by the middle of 2027. Chief executive António Simões told employees about the plan on Wednesday.
The group will start with voluntary redundancies in the UK and will consider mandatory cuts if take-up falls short. A spokesperson said the changes would allow L&G to focus investment on the areas where it sees the best prospects for growth. Unions will be consulted.
In his message to staff, Simões said the structures, processes and ways of working that had built up across L&G over the past decade had left the group "more complex than we need to be".
The asset management division, which oversees around £1.2trn globally, is not included in the programme. It went through its own restructuring last year, so the cuts are likely to fall mainly on group functions and the life insurance and pensions businesses.
Read next: Legal & General signals strategic shift as profits set to rise
Simões, who previously worked at HSBC and Santander, became group chief executive on 1 January 2024. He told staff that the group had spent the past two and a half years simplifying L&G and building it around three core businesses.
The largest step was the sale of L&G's US protection business to Japan's Meiji Yasuda for $2.3bn. As part of that deal, Meiji Yasuda also took a 20% economic stake in L&G's US pension risk transfer unit and a 5% stake in the group. Before that, Simões dropped the group's plans for a China licence and started the sale of housebuilder Cala.
Last year L&G appointed Emma Holden from Man Group as chief people officer. She is responsible for people strategy across the group and sits on the Group Management Committee.
Read next: Legal & General to sell US arm
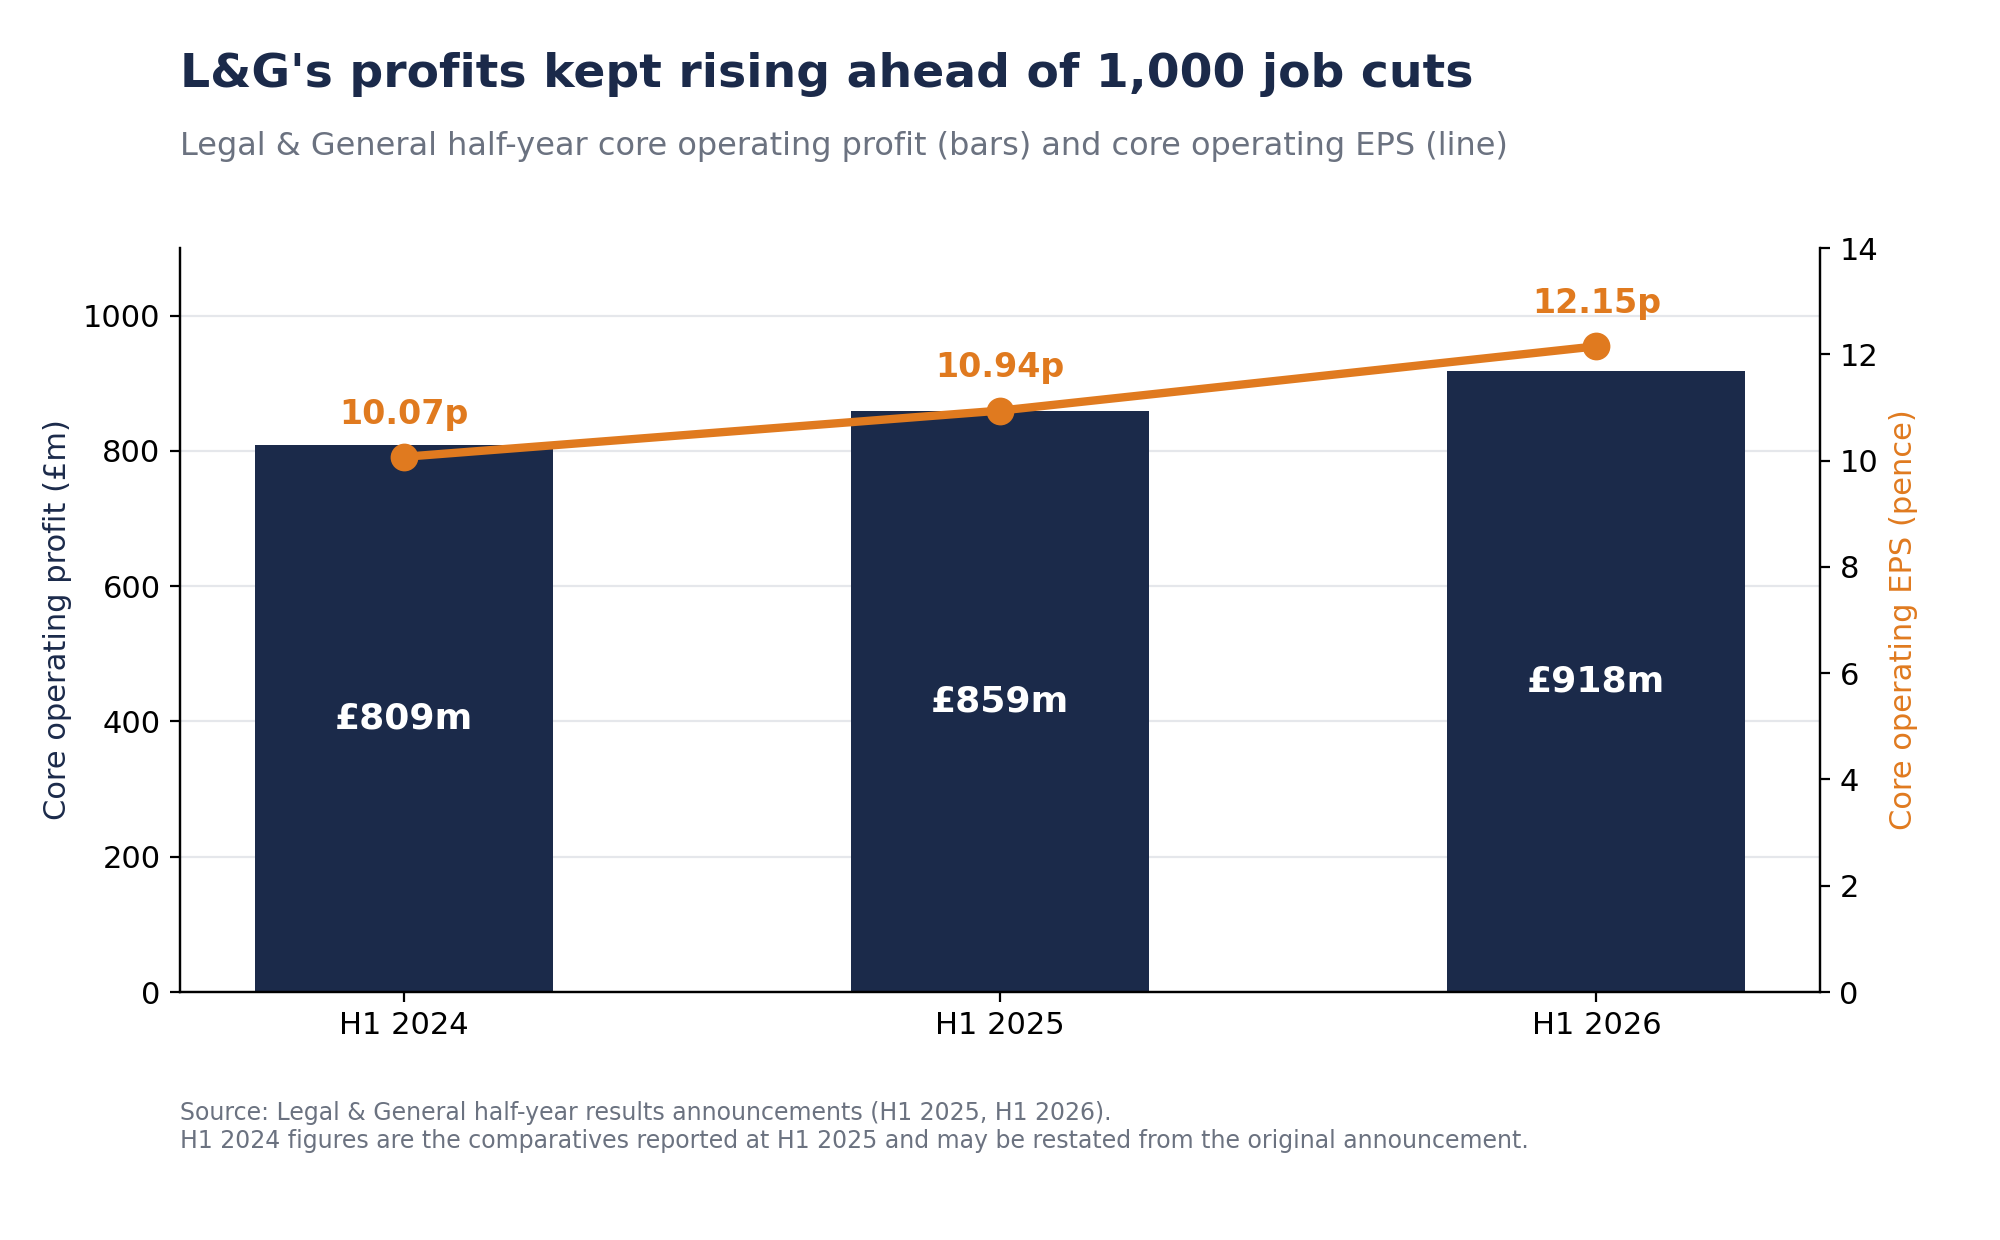
The cuts come shortly after a solid set of numbers. At its half-year results in August, L&G reported that core operating profit rose 7% to £918m and core operating earnings per share grew 11%. Its Solvency II coverage ratio was 201%, above its 160-190% operating target. A £1.2bn buyback is under way, and the group expects to return more than £5bn to shareholders between 2025 and 2027.
Investors have been told to expect a leaner group with higher returns, and reducing headcount is one way to get there. L&G has not yet said how much it expects to save, what the restructuring will cost, or when the financial benefit will show up.
L&G is one of several large UK insurers to announce job cuts over the past year or so. Aviva said its £3.7bn purchase of Direct Line would lead to up to 2,300 job losses over three years. Allianz has cut 650 UK jobs and more recently confirmed about 1,800 losses at Allianz Partners.
Read next: Allianz confirms hundreds of job cuts as AI reshapes insurance
Intermediaries will want to know whether service on L&G's retirement and protection products holds up while the life and pensions side shrinks. Bulk annuities are a particular focus, as L&G is one of the most active insurers in that market. Since the start of July it has completed a £1.65bn buy-in with Wood Group's defined benefit pension scheme. Hymans Robertson expects more deals, and higher volumes, in the second half of 2026 than in the first.
Read next: BP kicks off pension risk-transfer in £1.6 billion deal with L&G
Before any compulsory redundancies, L&G will need to run a formal consultation. Under UK law, an employer proposing 20 or more redundancies at one establishment must consult collectively, and the minimum consultation period is longer when 100 or more jobs are involved.
L&G says the cuts will free up money to invest in growth. Staff, brokers and shareholders should get a clearer picture of where the reductions will fall once consultation begins.