Transportation fleets with strong safety records are securing flat insurance renewals or modest increases, while weaker accounts face hikes of 30%-40% and fewer willing insurers, widening the challenge for brokers trying to keep financially stretched operators covered heading into 2027.
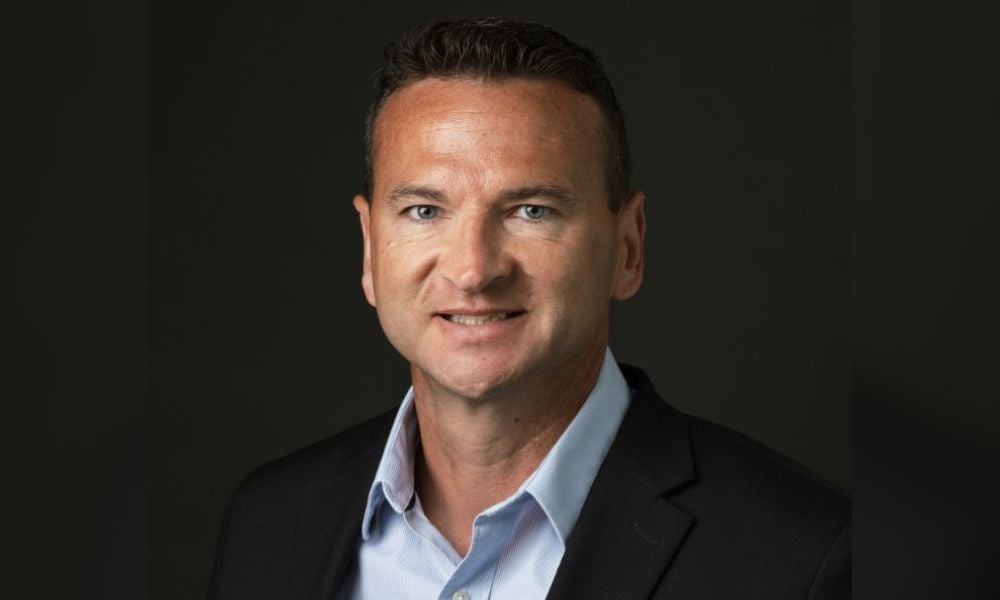
Mark Gallagher (pictured), RPS transportation leader, said the divide between accounts reflects insurers’ scrutiny of how businesses operate, including whether financial pressure is eroding maintenance spending or disrupting driver retention. Beyond pricing, some accounts can have multiple quotes, while others face non-renewal or sharply restricted access.
American Transportation Research Institute (ATRI) research published in May found trucking liability insurance premiums per mile rose 18.6% between 2021 and 2024. Among respondents, liability losses per mile increased an average of 33.1% over the same period.
Commercial auto insurers also remain under pressure. The Insurance Information Institute and Milliman forecast a US commercial auto net combined ratio of 100.9 for 2026, indicating an underwriting loss, with the line expected to remain above 100 through 2028.
Gallagher said several trucking and commercial auto insurers he met at recent WSIA (Wholesale & Specialty Insurance Association) meetings put the underlying trend requirement for their books at around 8.5%-9%. Individual renewals can look very different.
“We are seeing the best accounts still have multiple options available to them,” Gallagher told Insurance Business, “some flat or 5% rate increases.”
ATRI’s July operating-cost report illustrates the squeeze on trucking businesses. Average costs reached a record $2.336 per mile in 2025, up 3.4% from 2024, while repair and maintenance costs increased 8.6%. Operating margins in the truckload and refrigerated sectors remained below 1%.
Insurers are examining operators’ revenue and profitability, equipment investment and business longevity, Gallagher said. A fleet’s financial position can help explain changes in its risk profile before those changes produce claims.
Read more: Sticker shock ahead: How retailers can help clients navigate unbundled business auto coverage
Warning signs include aging equipment without reinvestment, deferred maintenance and reduced spending on driver training. Rising out-of-service violations and deteriorating safety metrics can provide further evidence that an operator is struggling.
“As you see margins strapped and operational shortcuts potentially occurring, that translates into higher risk down the road, whether it’s higher loss frequency or a higher loss ratio,” Gallagher said.
Conversations about maintenance budgets and staffing are relevant long before renewal. Brokers seeking alternative markets need to understand whether unfavorable results reflect problems the operator is addressing or pressures that remain unresolved.
Late claims reporting is another concern. Gallagher said insurers are watching whether operators attempt to handle incidents themselves before notifying their insurance provider, potentially delaying an investigation. He urged same-day reporting to the responsible insurer or program, even when the operator has an incomplete account of what happened.
“Even if all of the information isn’t there, they can still open the file and start to investigate and try to mitigate things,” Gallagher said.
Technology can strengthen an account’s appeal when operators use the information to change how they work. Gallagher pointed to driver coaching and adjustments to operating practices as opportunities arising from telematics data.
“When you share telematics and data, it opens up more of a world of opportunity within the commercial auto space,” he said. “We’re not only seeing it in trucking; we’re seeing it in the public auto and the business auto segments as well.”
Read more: Commercial auto telematics hitting a 'tipping point' – what does this mean for insurers?
Some programs require electronic data sharing or cameras, while certain public auto insurers also offer discounts when operators adopt the technology.
Brokers can explore how clients respond to the findings and use insurers’ loss control services. An operator’s willingness to work with safety specialists gives underwriters more information about its approach to managing exposures.
A larger deductible may offer immediate premium relief, but Gallagher cautioned that an operator’s ability to absorb future losses matters. Larger fleets with experienced risk management teams are generally better equipped to assess that trade-off.
“One of the issues that arises when you take on a larger deductible and you don’t have that sophistication, stability, or knowledge of the potential volatility, is that it can become financially burdensome” when claims do manifest, said Gallagher. For brokers exploring those structures, the renewal discussion must account for the potential cost if claims frequency or severity worsens.
“Carriers want to see that, from an operations standpoint, you’ve handled that type of large deductible in the past and you have the risk management sophistication to handle it,” he said.