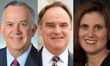
Genworth Financial chief executive Tom McInerney (pictured, left) will retire at the end of the year after 14 years leading the company, which is best known for its large legacy long-term care insurance business.
McInerney will step down as president and chief executive and leave the board on December 31. The board expects to name Jerome Upton (pictured, center), Genworth’s chief financial officer since March 2023, as his successor and to appoint him to the board. Angela Simmons (pictured, right), CFO of Genworth’s closed block, is expected to become executive vice president and CFO.
“The Board is confident that Jerome will carry this strong progress forward,” said Melina Higgins, Genworth’s board chair. She said that under McInerney the company had significantly strengthened its financial foundation, delivered value to shareholders and advanced a vision for the future in CareScout.
McInerney’s tenure was dominated by Genworth’s legacy long-term care book, one of the largest in the US. Like many long-term care insurers, Genworth underestimated how long policyholders would live and keep their policies, and how much care would cost. That led to years of losses and repeated requests to state regulators for premium increases on older policies.
McInerney said he was proud of the company’s progress in strengthening its financial position, returning capital to shareholders, addressing the challenges of the legacy long-term care business and launching CareScout, its care services business.
The closed block, which Simmons has overseen as CFO since 2020, includes these legacy policies. Genworth said she played an important role in keeping the closed block self-sustaining, meaning it operates without needing support from the rest of the company.
Upton has been with Genworth and its predecessors since 1998 and has held finance and operations roles across several businesses and regions. Genworth said he has worked closely with McInerney on improving the company’s financial and operating position.
“I look forward to building on the strong foundation we established under Tom’s leadership, executing our strategy with discipline, and working every day to create long-term value for our customers, shareholders, and associates,” Upton said.
For advisors with clients who hold Genworth long-term care policies, an internal succession points to continuity in how the company manages the legacy book, including its approach to premium increases and benefit reduction options. Policyholders facing large increases often need help weighing whether to pay more, reduce benefits or accept a paid-up option.
For the wider long-term care market, Genworth’s experience remains a cautionary tale about pricing long-tail health risks. New entrants, including Genworth’s own CareScout, are designing products with more conservative assumptions. Advisors should help clients understand how these products differ from older policies before they buy.