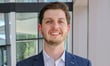
Alex Weaver (pictured) has spent his career lending money to insurance agencies, and there is one signal he has learned to read very quickly. When a seller demands 100% cash at close - no seller note, no transition period, no ongoing involvement - the question it raises is straightforward: what do they know that the buyer does not?
Weaver is vice president of specialty lending at Oak Street Funding, a First Financial Bank company that has specialised in commission-based lending to insurance agencies since 2001. He works across the acquisition and succession spectrum, and his view of the market is shaped by what brokers on both sides of deals actually do, rather than what they intend to do.
“It’s kind of like, what’s coming down the pipe?” he said of sellers demanding a full cash exit. A seller who wants out entirely and immediately is sending a message. It does not always indicate a problem. But it always warrants harder questions.
The industry norm Weaver describes is a 75/25 or 80/20 structure: the lender funds 75% to 80% of the acquisition price and the seller holds a note for the remainder. That seller note is not just a financing mechanism. It keeps the seller financially aligned with the success of the transition - motivated to help transfer client relationships, support book retention, and smooth the handover. A seller who stays involved for 12 to 18 months post-close gives the acquiring agency a materially better chance of holding the book together. A seller who wants nothing left in the game after day one removes that alignment entirely. Experienced lenders treat the 75/25 norm as a reference point in both directions: a seller comfortable holding a meaningful note is demonstrating confidence in what they are selling.
Read next: R&W claims are getting bigger, and insurers are signalling which terms could tighten
The other issue Weaver returns to consistently is one brokers on both sides of a deal tend to underestimate until it costs them: the state of your financial records determines how quickly you can act - and sometimes whether you can act at all.
Quality acquisition targets do not wait for slow buyers. A broker who can present clean financials, clear carrier relationships, and a coherent picture of their own business can move to close faster than one scrambling to produce documentation under deadline. In a competitive deal process, that speed is a material advantage. “You don’t want it to be something where that target says, oh man, it’s really kind of lingering with this buyer - I need to go try to find somebody else.”
The warning is sharper for sellers. Some agency principals run their business as a personal tax vehicle - maximising write-offs, running personal expenses through the agency, keeping reported profit as low as legally possible. That is a rational short-term decision. It becomes a serious problem when a lender examines those financials and sees an agency that appears to generate no income. “On paper their agency doesn’t make any money.” The fundability problem that creates can kill an otherwise viable deal.
Weaver also raised a point that agency owners tend to dismiss until it is too late: you do not always get to choose when you sell. Health crises happen. Partners exit unexpectedly. Market conditions shift. Agencies whose books are not in order and whose systems have not kept pace with the industry can find themselves forced into a rushed, poorly valued transaction at exactly the wrong moment. Keeping clean books year-round is not preparation for an eventual sale. It is protection against being caught unprepared for an immediate one.
The lending trend generating the most activity on Weaver’s desk right now is not acquisition financing. It is succession planning - specifically, the use of minority equity stakes to retain producers and key back-office staff who have accumulated enough of their own book to contemplate leaving.
Technology has lowered the barriers to doing exactly that. The administrative burden of running an independent agency is lighter than it was a decade ago. A top producer who wants to break away has fewer structural reasons to stay. Weaver’s view is that equity is becoming the primary answer to that problem, with agencies increasingly offering stakes of between 1% and 10% to people they cannot afford to lose. “Would you rather have 95% of a bigger pie or 100% of a smaller pie?”
The data supports the urgency. According to the Big “I” and Reagan Consulting’s 2025 Best Practices Study, only 12.5% of employees at top-performing agencies are equity owners, while roughly 30% of employees are likely meaningful value creators. That gap represents real and measurable retention risk.
The financing structure for smaller stakes is typically straightforward. The agency owner holds a seller note, funded by the distributions the new minority partner receives from their ownership share. For larger stakes the buyer approaches a lender directly - a 10% stake in a $10 million firm requires $1 million, serviced through distributions rather than salary. Many deals blend both approaches, with the mix shaped partly by the seller’s tax preferences. For principals who have resisted the idea of sharing equity, the financial mechanics are less complicated than they tend to assume. The harder work is psychological - accepting that giving away a portion of something you built is less costly than losing the person who helps it grow.
Read next: How representations and warranties insurance reshaped M&A broking
Private equity-backed and hybrid buyers accounted for 72% of all agency acquisitions in 2024, according to OPTIS Partners, and they are systematically acquiring the most attractive larger agencies. That is tightening the supply of quality targets for independent brokerages that cannot compete at that pricing level.
The response Weaver is seeing is a strategic shift toward smaller sequential deals. Rather than competing for one large acquisition and repeatedly losing to better-capitalised buyers, mid-sized agencies are building through multiple smaller roll-ups. “They’d rather do five small acquisitions that roll up into a nice big one than sit on the sidelines for two or three years.”
For brokers, the practical implication is a recalibration of what a good target looks like. A smaller agency with a clean book, documented processes, an owner willing to hold a note and stay through the transition, and no competing aggregator bids may deliver better risk-adjusted value than a larger agency in a contested process at an inflated multiple. The integration is more manageable, the financing is more straightforward, and the seller’s continued involvement - made likely by the note structure - protects book retention through the handover.
One misconception Weaver sees consistently on the sell side is worth flagging plainly. Smaller agency owners sometimes benchmark their expected sale price against deals done for much larger, more diversified firms - the transactions that make headlines. Those multiples are not transferable.
A smaller agency with a tighter book, less product diversification, and meaningful principal dependency will sell for less. That is not a negotiating position or an opening bid. It is a market reality. Discovering it mid-process rather than before engaging the market costs time, derails negotiations, and occasionally kills deals that could have closed cleanly.
The earlier a broker understands what their agency is actually worth to a buyer - built on clean financials, a transferable book, and documented processes - the stronger their position when it matters.