More than 21,000 PE-backed firms operate across the US. The American Investment Council’s 2025 private equity pension study puts their combined workforce at over 13 million workers. For the private equity insurance broker advising these accounts, the structure of the client relationship shapes every decision that follows.
Unlike a standard commercial account, this engagement involves two clients. The portfolio company is focused on running the business. The PE sponsor is focused on value creation, risk management, and return on investment. Each brings different priorities, different information needs, and a different definition of success.
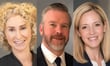
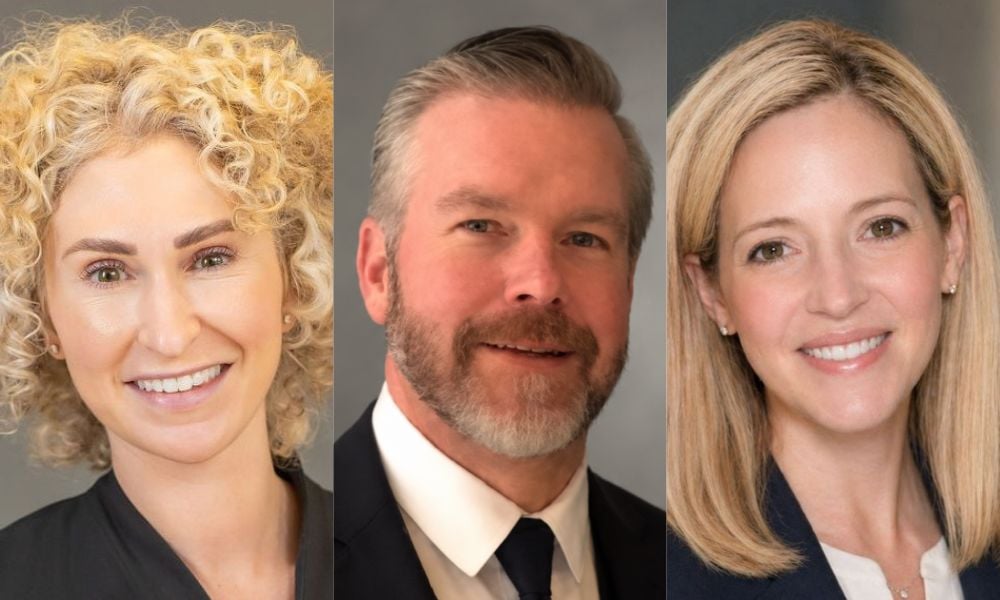
Four specialists from Denver-based IMA Financial Group’s private equity and M&A practice – Jordyn Arons Rosen, DFW market president and national practice director for private equity and M&A (pictured, left); Kevin Crowley, team lead; Shawn Carroll, national growth leader (pictured, center); and Meredith Milley, project manager (pictured, right) – detail what PE sponsors actually expect from their advisors.
The structural difference starts before a policy is written. A PE-backed account requires serving two distinct clients simultaneously, and they rarely share the same frame of reference.
The portfolio company is running the business. The PE sponsor is executing an investment strategy. The team notes that recommendations cannot simply be coverage-compliant. They must be operationally and financially sound.
“Recommendations need to be operationally sound, financially grounded and aligned with the sponsor’s broader objectives for the business,” the team said.
The scope of the engagement also shifts. A private equity insurance broker must understand the acquisition rationale, the investment thesis, the growth plan, and the exit strategy. The annual renewal is one point of contact in a much longer engagement.
“Unlike a traditional commercial account relationship, the conversation extends well beyond the annual renewal,” the team said.
That longer timeline matters because decisions compound. Program choices made at the start of the hold period affect the company’s risk profile, cost structure, and attractiveness to future buyers. The team argues that many brokers fail to account for this trajectory when they take on PE-backed accounts.
“Advising PE-backed companies requires an understanding of transactions, portfolio dynamics, value creation and the different stakeholders involved,” the team said. “It’s a more strategic and consultative approach than what many brokers are accustomed to delivering.”
Serving two clients with different priorities demands a different operating framework. From day one, the team argues, the broker’s job is to establish visibility, consistency, and scalability across the full portfolio.
“The biggest shift is moving from company-by-company thinking to portfolio thinking,” the team said.
That starts with reporting and benchmarking. Sponsors and company management are not looking for the same information. Operating executives need data to run the business. Sponsors need a portfolio-wide view that supports board discussions, investment decisions, and value creation.
According to the team, sponsors want to understand how each company’s performance compares across the portfolio, where costs or claims are running high, and where efficiency gains are available.
“Brokers should also be looking for ways to create value across the portfolio,” the team said. “That may include leveraging collective purchasing power, creating greater consistency in program structure, improving claims outcomes, identifying cost-saving opportunities and driving operational efficiencies.
“As new portfolio companies and add-on acquisitions are brought into the platform, the process should be repeatable and scalable rather than starting from scratch each time.”
That underlying expectation, the team notes, goes well beyond what most broker-client relationships are built to deliver.
“PE sponsors are looking for more than annual renewals,” the team said. “They want advisors who can provide strategic insights, measure performance across the portfolio and help support the sponsor’s broader objectives.”
The program a company carries into a PE deal is rarely the one it should carry through it. The team explains that the insurance strategy needs to track the business at every stage of the investment.
“At acquisition, we’re focused on understanding the deal, not just the company being acquired,” the team said. “We work closely with sponsors and management teams to evaluate the transaction structure, investment thesis and financial objectives behind the acquisition.”
That work includes assessing the existing program, reviewing claims history and liabilities, and identifying how the risk profile may shift after closing. Representations and warranties insurance is a key consideration at this stage.
According to Marsh’s 2025 Global Transactional Risk Insurance Report, published in March 2026, average primary layer R&W premium rates in North America rose 16% year-over-year in 2025, the most pronounced pricing shift of any region globally. Pre-close program assessment carries real financial weight.
If the transaction involves a roll-up strategy or add-on acquisitions, the team notes, integration planning should begin at this point, not after close.
“During the growth stage, the program needs to evolve alongside the business and support the sponsor’s objectives,” the team said. “As the company expands into new markets, grows organically or completes additional acquisitions, we’re reassessing risk, integrating new exposures and identifying opportunities to improve program structure, efficiency and cost.
“The goal is to ensure the insurance and benefits strategy remains aligned with the company’s changing risk profile while supporting growth and EBITDA objectives.”
The exit phase calls for a different kind of discipline. “Clear claims history, strong loss performance and a disciplined approach to risk management can help reduce diligence friction and support a smoother transaction process,” the team said.
Buyers and their advisors will conduct independent due diligence. The team stresses that the program should be well documented, appropriately structured, and reflective of sound risk management throughout the hold period.
Aon’s 2026 Global M&A and Transaction Solutions Claims Study found that North American clients recovered more than $1 billion across transaction solutions policies in 2025, including more than $440 million from R&W insurance alone. A clean record carries market value.
The most common failure, according to the team, has nothing to do with coverage. It starts with the wrong frame of reference.
“Private equity firms are not simply purchasing insurance. They’re executing a value creation plan,” the team said.
Advisors who approach a PE-backed account the way they would a standard commercial relationship will miss that distinction consistently. The team explains that effective PE advisors go well beyond evaluating coverage. They help sponsors identify liabilities, assess post-close risk, evaluate costs, uncover savings opportunities, and support better investment decisions throughout the hold period.
“Generalist brokers can also struggle with portfolio-level thinking,” the team said. “While each portfolio company has unique risks, sponsors are often looking for consistency, efficiency and scalable solutions across the broader portfolio. That may involve harmonizing programs where appropriate, leveraging purchasing power, identifying common operational challenges and creating processes that can scale as the portfolio grows.”
Timelines compound the problem. PE transactions and integrations move fast. The team points out that advisors who cannot mobilize quickly, or who slow down a deal by failing to provide actionable guidance on short notice, create friction at exactly the wrong moment.
“The most effective advisors function as an extension of the sponsor’s deal and operating teams, helping identify risks, unlock opportunities and support successful outcomes throughout the investment lifecycle,” the team said.
When a PE firm is evaluating a potential advisor, the team argues that firm size is the wrong starting point. The more relevant questions center on demonstrated experience with PE sponsors and portfolio companies specifically.
“PE firms should ask a broker how much experience they actually have working with private equity sponsors and portfolio companies, not simply how large the brokerage is,” the team said. “How many PE-backed companies do you currently serve? Do you have a dedicated Private Equity & M&A practice? Can you support diligence and transaction-related needs before a deal closes?
“Just as importantly, can you support the business after close? The expertise required to execute transaction liability insurance, and diligence is often very different from the expertise required to serve a middle-market or lower-middle-market operating company over the next five to seven years.”
Sponsors should press equally hard on how the broker approaches the portfolio as a whole. According to the team, sponsors should ask whether the broker can track and benchmark programs across the portfolio, identify purchasing-power opportunities, and support add-on integrations without rebuilding from scratch each time.
“Having specialists is important, but having a structure that encourages collaboration and allows those specialists to be brought together seamlessly is what ultimately creates value for the client,” the team said.
The team also points to a question that most capabilities presentations never address: what happens when something goes wrong? Who handles a significant claim? Who leads a complex diligence project? Who steps in when an acquisition enters the portfolio on a tight timeline?
“The answers to those questions often reveal far more about a broker’s capabilities, responsiveness and ability to support the investment lifecycle than a standard capabilities presentation,” the team said.