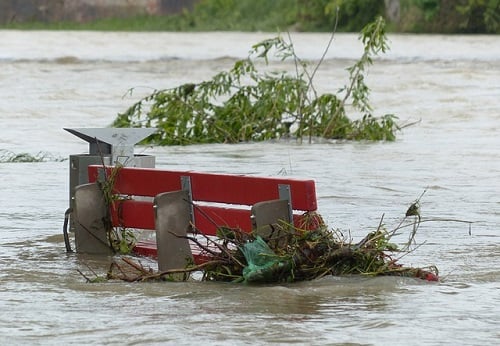
The rising water levels of Okanagan Lake are keeping one insurance broker busy, as more and more concerned policyholders approach him to add to their insurance coverage in anticipation of flooding.
The body of water has exceeded its previous record height and experts say that the water level could rise another 10-15 cm, endangering residents who live nearby.
Due to the seemingly inevitable risk of flood, Brett Innis of Kelowna Valley Insurance said that he has been fielding more inquiries from customers in the area than usual.
Search and compare insurance product listings against Overland Flooding from specialty market providers here
“We have a couple of claims, and some people are adding to their policies,” Innis told Castanet on Monday.
Innis added that regular homeowners’ insurance on its own does not cover exposure to flooding from rising lakes, rivers or streams, also known as overland flooding. Such insurance was only made available about four years ago following a major flood disaster in Calgary.
“Before that, there were only government programs for financial assistance,” he noted.
Innis explained that while currently more insurers have started adding overland water coverage, “they stay away from the word flood.”
“Most, but not all, now offer it. It has been slowly growing in the industry,” he observed.
“Not all [insurers] use the same formula. Some go by longitude and latitude, or postal code. But, if you’re in a flood plain, you will likely be excluded.”
Premiums for overland water coverage can be as low as $40 or up to thousands of dollars, depending on risk, Innis explained. He pointed out that he does have clients with coverage, and that he has seen premiums as high as $6,000, with a $1,000 to $2,000 deductible.
Aside from covering for water damages and repair costs, overland water coverage can also cover for additional living expenses based on a percentage of what the house is insured for. The policyholder, however, must first be covered for the specific peril.
“The key is the words ‘sudden and accidental.’ That’s what you want to insure. Don’t wait until the flood is coming because insurance probably won’t be available.”
Related stories:
Is it time to stop building in flood zones?
Few Canadians are aware that their homes are at high risk of flooding: Study