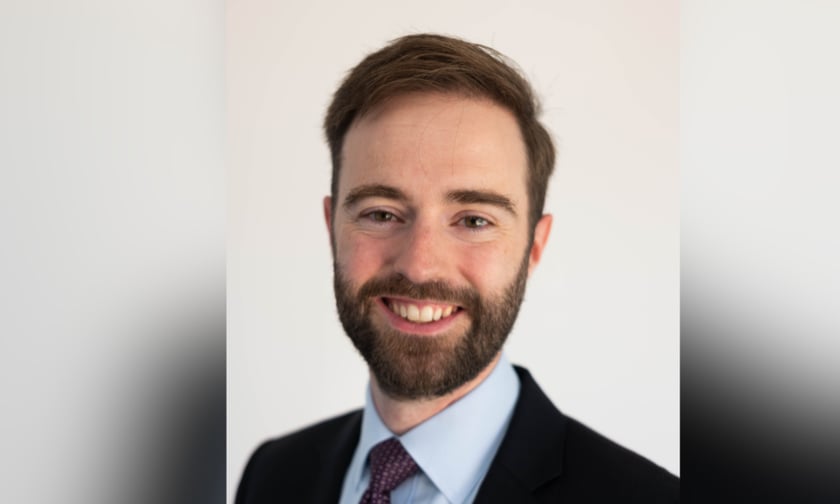
Hugh Selka (pictured) has spent 11 years writing trade disruption insurance, and he says the biggest misconception he encounters is not about pricing or appetite. It is that clients "are worried about supply chain risk, but they're generally not aware that it's insurable."
That means businesses can end up carrying supply chain exposure on their own balance sheet or making a rough proxy allowance for it because they assume no insurance product exists. For UK brokers advising on commercial and specialty lines, that gap between concern and awareness creates an opening.
Selka, an underwriter in the special risks team at Tokio Marine Kiln in London, said the reaction when clients discover the risk can be insured is immediate.
"Finally there's a solution which they've been looking for for all their lives, but they just weren't aware of," he said.
The coverage gap emerges when disruption occurs without physical damage, whether from a blocked port, embargo or war. The financial loss can be substantial, but conventional policy wordings may not respond.
Part of the problem, Selka argued, is structural. "Supply chains are weird in a way that doesn't really align with the way insurers look at them in general," he said, pointing to how property and political risk teams are built around well-defined, surveyable assets rather than sprawling, multi-peril supply networks. That reflects a wider frustration among corporate buyers. A joint Airmic and IUA report found large businesses frustrated by insurance built around individual product lines rather than the outcomes they need to protect.
Selka also argued that supply chains have grown longer and more concentrated since China joined the World Trade Organization (WTO), with sourcing shifting from multiple nearby suppliers towards fewer, distant, lower-cost origins, leaving less room to absorb a shock.
Selka pointed to demand surge and port concentration as two areas businesses can underestimate. When a disruption hits, affected companies turn to the same alternative suppliers at once.
"It's going to be an everyone problem all at the same time," he said, pushing up costs beyond what an individual business may have anticipated.
Selka described reviewing one US client whose supply chain analysis showed roughly 70% of turnover moving through just two ports, with around 45% passing through a single East Coast facility and another 25% through one on the West Coast. It was an individual example rather than a market-wide figure, but it illustrates the questions brokers can ask about concentration: if a dominant route is blocked, businesses may simultaneously need alternative warehousing, additional trucking capacity and shorter delivery windows, while competing with other affected companies for exactly the same resources.
The effect can be more severe for specialist operations. Selka pointed to a client moving food-grade liquid in bulk by tanker, which relies on a specific port facility to pump cargo directly into its terminal. If that facility becomes unavailable, the business cannot simply redirect to another port. It has to rebuild its supply chain from the origin, reloading into containers or ISO tanks, shipping to a different port and unloading onto trucks for onward processing, with each step adding cost.
Cover for those additional costs has also been shrinking, Selka said: "Even if the cargo market is reasonably soft at the moment, you're still seeing what they call additional expenses, sub limits being reduced." Once close to $1 million a few years ago, he said, those limits have fallen to the low hundreds of thousands.
That cover can also depend on a cargo-damage trigger, meaning disruption such as the Baltimore Bridge collapse or the Ever Given blocking the Suez Canal may leave cargo stranded without the physical damage needed to trigger conventional cover.
That exposure rarely shows up straight away. Clients carry varying levels of inventory, Selka said, with around 30 days typically used as a starting point when structuring cover, meaning the financial impact of a major disruption may not appear immediately.
"We are just a sticking plaster to give clients the breathing room to adapt their supply chain," he said.
The potential exposure can also extend beyond lost revenue. Selka pointed to liquidated damages clauses carried by businesses heavily dependent on one customer, creating another potential cost when disruption prevents them meeting contractual obligations.
Recent events have made those dependencies harder to ignore. The cyberattacks on Marks & Spencer and Jaguar Land Rover demonstrated how disruption at major businesses can spread through their supplier networks. The knock-on effects highlighted how quickly concentration risk can become a wider business interruption problem.
But for brokers, the opportunity is not simply introducing another insurance product. It is identifying where clients are already carrying potentially significant supply chain exposures themselves because they have never considered them insurable.
That turns supply chain resilience from an operational concern into an insurance conversation, and gives brokers a reason to ask a more fundamental question: where would a client's business actually start losing money if the chain stopped moving?