With US employers facing projected healthcare cost increases of approximately nine percent from 2026 to 2027, on top of roughly seven to eight percent the prior year, a veteran employee benefits advisor says the industry cannot keep absorbing this unsustainable trend and that the pushback has to start with advisors themselves.
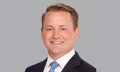
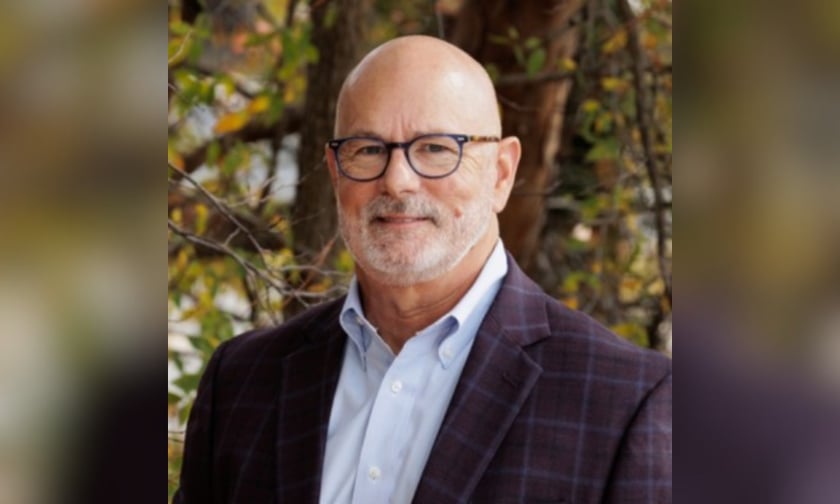
Wayne Bowling, Employee Benefits Practice Leader at CAC Agency at The Baldwin Group in Birmingham, Alabama, has been in the group benefits business since the 1980s. In a conversation with Insurance Business Benefits US, he made the case that advisors, sitting at the intersection of employer and carrier relationships, are uniquely positioned to drive systemic change on healthcare costs.
"It is our responsibility as advisors within Baldwin and really anyone that's in this profession to represent our clients to the best ability that we can," Bowling said. "We have great relationships with insurance companies, with third-party administrators, with stop-loss carriers and pharmacy benefit managers. But we've got to collectively work together to find some solutions here."
Bowling entered the business selling life insurance at kitchen tables before a referral to a small business owner set him on the path to health coverage, a pivot that would define a 45-year career.
He sees a pivot in the industry too. Pre-pandemic, a renewal often meant minor plan adjustments, while today it requires analyzing network differences, pharmacy benefit manager (PBM) formularies, regulatory compliance, and the root causes of cost inflation.
The Affordable Care Act (ACA) has built what Bowling calls a "rigid box" that constrains what advisors can offer.
"When employers are seeing year-over-year increases like this, there's a tendency for all of us to race toward the next shiny object, the next point solution," Bowling said. "It is our job as advisors, especially within the Baldwin framework, to understand and know where these different ideas really play into the mix on helping us control cost and improve health."
Bowling noted analysis of self-funded plan data at CAC Agency at The Baldwin Group which points to a clear culprit for rising medical trend: high-cost claimants, not routine care.
Specialty drugs including glucagon-like peptide-1 (GLP-1) medications and therapies are among the most acute cost drivers.
"We should be using that data to predict high-cost claimants way before they become high-cost claimants," he said. "If we're not doing that, we're being irresponsible."
On the pharmacy side, Bowling described a structural imbalance that leaves US employers with little practical leverage.
Unlike virtually any other consumer purchase, employers cannot reject a drug's price outright without running into what he called a "moral dilemma" - removing a therapy from a formulary that an employee may genuinely need. He argued that the United States uniquely absorbs global pharmaceutical pricing.
"No one else is paying the cost of drugs that we are in the US," he said. "We've got to push back collectively as a community."
Asked who should drive the industry's response to unsustainable cost increases, Bowling is clear that advisors hold the most power, because they maintain relationships on both sides of the equation - with employer clients and with carriers, third-party administrators (TPAs), and PBMs alike.
Emerging price transparency rules are beginning to give advisors data they can act on and identifying cases where a preferred provider organization (PPO) network is paying significantly above the transparent average cost for a service.
The logical next step, Bowling argued, is demanding that administrators pay only the average. He acknowledged that networks are currently pushing back but framed this resistance as something the advisor community must overcome.
"Brand A is going to lose the business" if it refuses to cooperate with data-sharing and cost management, Bowling said, describing a market mechanism that can shift the dynamic if advisors are willing to use their leverage consistently. "It's our conversation to start."
He cautioned, however, that renegotiating any single lever in a self-funded arrangement, whether network, PBM, or stop-loss, has ripple effects on the others. "Everyone needs to be at the table, eyes wide open, because there are so many moving parts and you don't want to miss one when you're trying to negotiate one," he said.
The Department of Labor's (DOL) ongoing transparency rule enforcement provides a regulatory foundation for the data access Bowling describes.
Beyond healthcare cost management, Bowling identified employee assistance programs (EAPs) as one of the most cost-effective benefits an employer can offer in a post-COVID environment, but only when structured properly as a standalone program, not tacked on to a life or disability product. Mental health, front and center since the pandemic, can be meaningfully addressed through a well-designed EAP at relatively low cost, he said.
On voluntary benefits, Bowling pointed to the multigenerational workforce as a critical planning variable. The needs of a young couple starting a family differ sharply from those of an employee within five to 10 years of retirement.
"Communication is the key," Bowling said. CAC Agency at The Baldwin Group has responded to this challenge by investing in a dedicated communications team to help advisors improve how employers talk to employees about their benefits packages.
On artificial intelligence, Bowling expressed measured skepticism that the technology will displace the human advisory role in any meaningful timeframe. He sees AI accelerating good work - surfacing relevant information more quickly - but not replacing the judgment required to assess an employer's culture, leadership dynamics, and workforce-specific needs.
He pointed to long-term disability insurance as a concrete example of product complexity that AI cannot yet reliably navigate for a general consumer: comparing definition-of-disability language across multiple contracts requires a level of nuanced analysis that, in his view, remains "a long way away" from reliable automation.
"AI is not going to take the responsibility on conversations that can take into the importance of the culture of an organization, what message they're trying to convey to the employees," Bowling said. "AI can't do that."