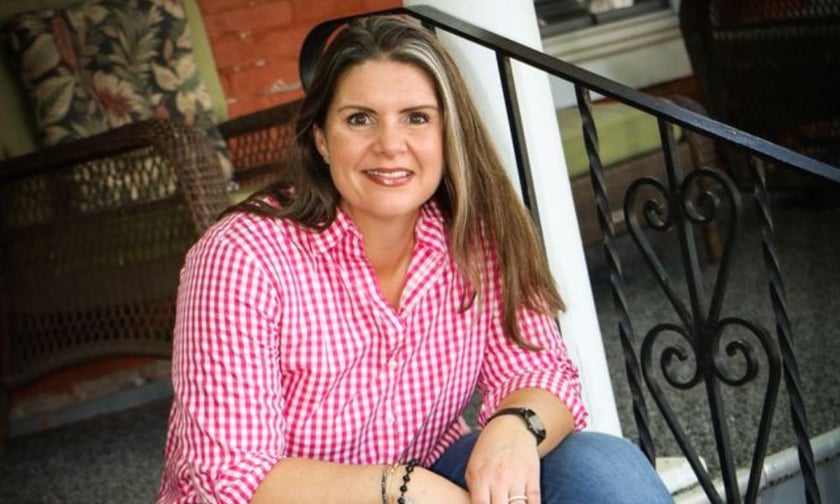
When Susan L Combs (pictured) was 26 years old, she sat across a desk from a CFO who handed her a management trainee contract with no salary and told her to “trust us.” She replied that trust does not pay the bills. He told her that refusal meant they were finished. She walked out and spent the next 21 years building Combs & Company to prove the point.
Today, Combs is founder and president of the New York-based brokerage, a PPACA-certified expert witness who has worked on court cases in 47 states, a former national president of Women in Insurance and Financial Services, and a two-time author. The thread connecting it all is a talent for reading what the numbers are not saying, and the confidence to say so out loud.
“Nobody ever grows up and says, I want to be an insurance broker,” Combs says. “It is either a legacy thing or you fall into it by accident.”
Her version was the latter. She graduated from the University of Missouri in 2001 with a hospitality degree, having arrived on an Air Force ROTC scholarship in chemical engineering before switching tracks to what she describes as “a glorified business degree with cooking classes.” She accepted a banquet manager role at the Marriott at the World Trade Center. Two weeks before her start date, a budget cut eliminated the position. Detroit or New Orleans were offered as alternatives. Her mother had already ordered a going-away cake decorated with images of New York City. Marriott was unmoved.
She went anyway, stayed in a military hotel, and gave herself a month. A head-hunter placed her at Paychex. When the firm launched a workers’ compensation product that no one knew what to do with, she learned it and became one of their first workers’ comp representatives. People in those insurance meetings started asking about other coverage types. She began referring leads to a benefits agency and noticed the recipients were building compounding income while she reset to zero every month. “I am a Taurus,” she says. “I think a lot about money and how to make it.”
She landed at DeWitt Stern, then the largest entertainment insurance brokerage in the United States and now part of Brown and Brown, of which she runs a producer group in addition to her ownership of Combs & Company. DeWitt Stern required all staff to obtain property and casualty licenses, expanding her reach. She negotiated ownership of her own book of business from day one as a 1099 contractor. Her annual draw was $24,000. She became a certified personal trainer to make ends meet.
After a year, the CFO presented a management trainee contract with no salary and told her to trust the firm. “Trust does not pay the bills,” she replied. A mentor told her she could do it alone. On June 24th, she walked out with her broker of record letters already prepared. By July 1st, her income had more than doubled. She set aside 30 percent of every payment for quarterly taxes. Combs & Company began in her apartment on 32nd Street in Manhattan. When the Affordable Care Act arrived in 2010, many brokers fled or folded. New York had made her better prepared: the state had long operated with community rating, guaranteed issue, and most of the ten essential benefits already in place. “We were ACA before the ACA,” she says.
The operating philosophy of Combs & Company is three words: do more better. “There is always one more thing you can do for somebody, or you can do it better,” Combs says. She applies it to competitive weightlifting and to client service in equal measure.
The insurance industry, she argues, sometimes forgets it is a service industry. That does not mean absorbing mistreatment without limit. She applies a three-strike policy. One bad day passes without comment. A second triggers a direct conversation: the people who work here spend a significant portion of their lives supporting you, and they do not deserve to be mistreated. A third ends the relationship. What this communicates to her staff is as important as the message it sends to the client: she has their back.
On compensation, she is equally direct. “If you lead with commission, you are going to always lose on commission. If you do right by the people, the money comes.” She has received responses to emails sent ten years ago, from contacts who remembered who helped them without expecting anything in return. Clients do not remember commission rates. They remember the call taken at inconvenient hours.
Her business model is deliberately diversified so no single account loss threatens the payroll. She has colleagues carrying six large clients who spend every renewal cycle in dread. “I look at worst-case scenarios for a living,” she says. “Spread out your risk.”
The agent-versus-broker terminology debate is one Combs finds genuinely draining, not because the distinction does not matter, but because its inconsistency across state lines makes it actively confusing. In New York, everyone is on the same page: an agent represents the carrier; a broker works for the client. “I do not care what carrier you go with. I do not care how much I make from the carrier. The rates are the rates. The percentage is the percentage. I want to do what is best for you.” Go to California, where everyone calls themselves an agent regardless of alignment, and the clarity dissolves. Some regions insist that brokers should rebrand as consultants. “We have to play in the same sandbox,” she says. “Wouldn’t you want somebody who actually understands that sandbox?”
Combs & Company focuses on small groups. Client conversations begin with straightforward questions: which doctors do you see, which medications do you take, where is the nearest hospital to your home? Because the firm’s client base is broad and diversified, the commission on a five-person group, which may be $30 a month rather than $3,000, does not change the quality or speed of service. Roughly 89 percent of American companies have fewer than 20 employees. Those companies need broker support as much as, or more than, any large account. Some brokers do not want to be bothered with a five-person group. Combs and her team are not among them.
One of the firm’s most distinctive market segments is foreign corporations opening their first American offices. Companies whose employees are accustomed to the National Health Service or to commercial insurers like Bupa encounter a steep learning curve with the American network-based model. The initial guidance is intensive. Once clients understand the system, they stay. Technology has a growing role, Combs acknowledges. But it has not yet displaced the need for a human being when an employee calls, cancer diagnosis just received and employer not yet told, needing someone to walk them through what their coverage actually means. “They need a person,” she says. “They need an advocate.”
The Transparency Act, implemented as part of the ACA framework, requires hospitals to publish machine-readable files disclosing what they charge different carriers for the same procedures. The stated intent was market efficiency. The consequence has been carriers engaged in a competitive standoff: one insurer sees that another is being paid more for a given service and demands parity, prompting midterm contract renegotiations with hospital systems.
The casualties are patients. Someone in the middle of cancer treatment should not learn that their hospital has fallen temporarily out of network. “I have never seen it not work out,” Combs says: coverage is eventually reinstated and backdated. But the stress placed on patients is entirely avoidable. A friend was admitted for a procedure while the carrier and hospital were disputing network status. Four days in the hospital, thousands of dollars in incurred claims, and the procedure did not happen. As an in-network provider, the admitting physician was responsible to verify network status before proceeding. The verification did not occur.
The mechanism behind these disputes is the chargemaster: a hospital billing list with no mathematical foundation, originally a physical book kept on every billing department desk and since digitized without reform. A delivery that carries a chargemaster price of $100,000 might settle at a negotiated in-network rate of $27,000. The Transparency Act made such gaps visible across carriers simultaneously, and the ensuing competition to close them has become a primary source of disruption. “It is almost like a turf war,” she says. “And it is rough.”
The regulatory proposal that has Combs most intrigued, and most measured in her enthusiasm, is the introduction of no-network plans to the individual marketplace. Originally targeted for 2027, the concept has already been pushed to 2028 while implementation details are resolved.
The premise is to give consumers direct negotiating power with providers. Say your plan will pay $1,000 for a Mohs surgery; will the dermatologist accept it? “It sounds good,” she says, “if you say it really fast.” In practice, most people do not know what medical procedures cost, and most will not travel to a less convenient facility because it is cheaper. Where she does see potential is in the companies that will emerge to help consumers navigate the terrain: a model analogous to debt consolidation services, in which a firm helps negotiate down a provider’s bill and takes a flat fee or a percentage of the saving. That market does not yet exist because the plans do not yet exist for individual consumers. But she can see it coming.
Her broader market prescriptions are specific. Catastrophic health plans, traditionally restricted to adults under 30 and for qualifying hardships or affordability exemptions through the exchanges, should be available based on who wants it rather than age: the under-30 cohort are precisely the people with the smallest financial cushion if something serious occurs. She would also like to see stop loss coverage made accessible to small groups in New York State, where it is currently illegal to write it for groups under 100 lives.
The larger diagnosis Combs offers for the American healthcare market is structural, and it does not begin with insurance. “You have to fix the healthcare before you can fix the health insurance,” she says. The chargemaster, the midterm network renegotiations, the misaligned incentive structures that drive utilization rather than outcomes: these are problems of healthcare delivery, not insurance design. Universal coverage generates enthusiasm. As a fiscal proposition, it runs into mathematics. A state-level universal healthcare plan in New York carries an estimated price tag three times the state’s annual budget. The arithmetic does not work. What can work, and what she sees gaining traction, is the expansion of direct primary care contracts: a model in which access to a physician is prioritized and the conversation about what a patient genuinely needs comes before any battery of tests is ordered.
Eleven years ago, Combs entered a line of work that almost no benefits broker occupies: expert witnessing on the Affordable Care Act (ACA), primarily in high-end medical malpractice cases.
Her PPACA certification, obtained through NABIP, required ten modules delivered through a combination of in-person instruction, self-study, and online coursework, followed by ten proctored examinations. New York administered the process to a higher standard than other states. It was not a click-through exercise. Biennial continuing education is also required.
The opportunity came through Joan Fusco, who had taught much of the certification curriculum. A law firm approached NABIP looking to incorporate ACA expertise into litigation strategy and asked for a recommendation. Fusco put Combs forward. The fit was immediately apparent. Her father had been a Major General in the Air Force and, in the civilian world, a judge. She had grown up around attorneys. He left her with a principle she applies in every case: “It is important for you to be understood, but it is more important for you not to be misunderstood.”
She has now worked on cases in 47 states, the majority medical malpractice matters. She also takes on trip and fall litigation, construction cases, and automobile accidents. Her central contribution is the analysis of life care plans: documents that map everything a plaintiff will need from the point of injury through their life expectancy, covering physicians, medications, equipment, and home care. “A life care plan tells a story,” she says. “And when the story does not add up, that is where I come in.”
One case involved a plaintiff living in a care facility costing $600,000 a year. The level of care described in the life care plan did not, in Combs’s reading, match the profile of someone requiring full-time residential placement. She asked why he was there. He was homeless. His relationship had ended after the accident. He had no family and no alternative, and the facility had become the default. Her proposal: buy him a home in the city where he was living. Two years of facility costs would fund a property that would belong to him outright. A home health aide for ten hours a week would address his actual support needs. “He is not that broken,” she told the attorneys. The solution matched what the life care plan was genuinely describing and delivered a substantially better outcome while eliminating an unnecessary cost.
The principle extends to settlement figures. A life care plan carrying a headline demand of $52 million is not necessarily wrong; the question is how to use the available financial tools to deliver that outcome as efficiently as possible. A fiduciary, by law, must be prudent with money. An economist converts future costs into present value. An annuitist structures the settlement so it grows with interest. A $52 million demand can be met at a fraction of that nominal figure while preserving equivalent long-term value for the plaintiff. The approach is not about diminishing the value of a plaintiff’s needs, but rather determining how those needs can be funded most effectively over their lifetime. Combs works with attorneys on both sides to look beyond the headline number and focus on the long term outcome. “How can we make it better for this family?” is the question she is brought in to answer.
In a recent Mississippi case, the plaintiff was moved to discover that a properly structured settlement would fund not only the medication she had been unable to access because of her injury but an array of other services as well. Combs was in the strategy session explaining the mechanics to both plaintiff and defense counsel. She never serves as the broker on any case she advises: that would be a conflict of interest. Her father died nearly eight years ago from Agent Orange-related throat cancer. Through her legal connections, she arranged a second opinion at MD Anderson following his treatment at the Mayo Clinic. She was in the room when he told the physician: “It is the practice of medicine. You are not God. Bad things happen to good people every single day. And you are human.” That perspective is what she brings to the attorneys she works with. Not an adversarial posture. A practical one.
Outside of insurance and the courtroom, Combs is a competitive weightlifter and CrossFit athlete who applies the same one percent better philosophy to every domain. She has written two books, “Pancakes for Roger: A Mentorship Guide for Slaying Dragons” and “Wonder Women: The Untold Stories of Female Veterans,” both connected to a nonprofit she founded that provides housing support grants for veterans. She was the first woman named Broker of the Year by BenefitsPro. The two subsequent female recipients, have become her closest professional peers. The three connect daily and discuss personal and professional challenges openly, a peer mentorship arrangement she considers more valuable than any conventional model.
Twenty-one years after walking out of that meeting with nothing but broker of record letters and a refusal to accept less than she was worth, Combs has built something that compounds in ways a draw never could.