A renewable energy project can go years without a claim and still face tighter coverage at renewal if insurers have paid for grid outages affecting similar projects nearby.
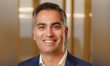
Jatin Sharma (pictured), executive vice president at Amwins Energy & Infrastructure, said underwriters may look at losses across a regional grid when setting terms for contingent business interruption (CBI). The coverage can protect a wind or solar project against lost revenue when damage to third-party equipment cuts off its ability to sell power.
If an insurer thinks the kind of grid failure that caused a claim at a nearby project could also disrupt the client’s operations, it may narrow the client’s coverage at renewal, Sharma said.
A single substation can serve several projects, leaving them dependent on the same equipment and on a third party’s ability to repair it. In Oaxaca, Mexico, earthquakes in September 2017 damaged two substations in the Isthmus of Tehuantepec. Mexico’s grid operator said it coordinated the reconnection of nine wind farms served by one of those substations after repairs.
The scrutiny comes as renewables insurance gets cheaper. Willis, a WTW business, reported in June that most renewable energy placements were drawing more capacity than buyers needed. Its 2026 market review put pricing reductions at 20% to 30% for well-engineered accounts with clean loss records and large premiums.
Read more: Slower growth ahead for renewables sector, but insurance can keep the market charged
Carriers restricted CBI terms during the 2020-2023 hard market, but over the past two years, deductibles have come down and insurers have offered higher limits and longer indemnity periods, accoding to Sharma. A covered substation failure can now leave insurers paying for a larger share of the outage. The daily loss can also be substantial because a project may lose its entire revenue while its grid connection is down.
And while routine equipment failures give insurers a history to model, but outages at shared substations are harder to predict. “When the losses happen, they tend to be significant," Sharma noted. "There’s no attritional CBI loss. It’s either a bang or it’s not there.”
Underwriters are still working through some of those losses ahead of January 1, when many carriers renew their reinsurance treaties. For generators, even a small change in the period their policy will pay for can matter if a third-party operator needs months to source and install a replacement.
Operators can take steps to speed up repairs to their own assets, but their options are more limited when the equipment belongs to the transmission operator. Sharma said: “A lot of them might be able to source spare equipment for themselves, get crane mobilization, or get specialists to come and fix things, but it’s outside of their care, custody and control."
Before renewal, brokers can identify which substations a project relies on and ask how long it would take to restore the connection if a key component failed. A repair that might take 90 days in favorable conditions could stretch to 180 if weather makes it harder to get replacement equipment to the site, Sharma said. That gives brokers a concrete scenario to compare with the proposed indemnity period.
Read more: Soft power insurance market hides a harder renewal problem
If an insurer proposes a shorter period, Sharma said buyers can discuss it with their lender’s consultant and price an excess CBI layer before renewal. The broker can then compare the cost with the revenue at risk after the underlying coverage ends and check whether the proposed layer would actually pay for that additional time.
The Amwins executive has also seen more inquiries about deductible buydowns as clients redirect savings from cheaper renewals. A buydown reduces how much the client absorbs at the start of a covered loss. A client concerned about a long outage still needs to look at how long the policy will pay.
The month an outage starts matters. US wind projects, for example, can earn a disproportionate share of their revenue from April through June. An April substation outage could therefore cost a project much more than an equally long outage later in the year.
"Things like contingent risks are very difficult for an insured that has these generation assets to control. That's why they need the coverage," said Sharma. "Part of being a competent broker and representative for clients is to get ahead of those losses and to anticipate what could happen."