Most deal teams handle M&A insurance due diligence last. The insurance advisor arrives a few weeks before closing, when the time to address structural issues has already run out. That compressed timeline limits what the advisor can accomplish.
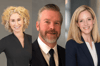
Four specialists from IMA Financial Group's private equity and M&A practice address how to manage insurance at each phase of the deal. They are Jordyn Arons Rosen, DFW market president and national practice director for private equity and M&A (pictured, left); Kevin Crowley, team lead; Shawn Carroll, national growth leader (pictured, centre); and Meredith Milley, project manager (pictured, right). Together, they cover what brokers and buyers need to get right, and when.
The scope of the work changes depending on when the insurance advisor enters a deal. Arriving in the final weeks before closing shifts the entire nature of the engagement, the IMA Financial team notes. Structural decisions, alternative markets, and long-term planning all get pushed off the list.
"When advisors are brought in late, the focus often shifts from optimization to execution," the team said. "The conversation becomes, 'What do we need to do to get this deal closed?' instead of, 'What should this program look like over the next three to five years?'"
The team's answer is to engage at the letter of intent (LOI) stage. "That doesn't mean immediately sending the seller an extensive diligence request list," the team said. "But it does allow the advisor to understand the transaction timeline, identify key workstreams and prepare to move quickly as information becomes available."
As information arrives, the team adds, the advisor can assess the existing program, flag potential concerns, and begin evaluating how the risk profile will shift after closing. That runway is what makes the difference.
"The earlier the advisor is involved, the more strategic the conversation can be," the team said.
Not every insurance issue in a deal is the same, according to the team. Some findings are expected. Others can stop a transaction in its tracks.
"The most common findings involve gaps in the existing insurance program, uninsured or underinsured exposures and claims history that presents a different risk profile than management initially described," the team said. "Those issues are generally straightforward to evaluate, but they can still have meaningful financial implications."
The team also flagged a separate class of issues that never appear in a standard renewal process. They include change-of-control provisions, consent requirements, tail coverage obligations, and policy provisions that directly affect the purchase agreement. No two carriers handle change-of-control language the same way, the team notes.
"Perhaps the most important question isn't whether the company has insurance," the team said. "It's whether the existing program is transferable, adequate and appropriate for the business that the buyer will own after closing. That's where much of the real diligence takes place."
Insurance diligence is among the first workstreams to get deprioritized when a deal gets complicated, the team notes. Keeping it on track takes a specific approach.
The team notes that the process starts with prioritization. Not every item on the diligence list carries equal weight. The focus goes to the requests with the greatest impact on the transaction. That also prevents sellers and management teams from being overwhelmed at a sensitive point in the process, they explain.
"When you're working on transactions every day, you learn how to triage issues quickly," the team said. "You can distinguish between concerns that could affect valuation, deal structure or closing and those that can be addressed after the transaction is complete.
"Insurance has its own language, but buyers don't need a lengthy report filled with technical terminology. They need to understand the issue, the financial implications and the available options."
The goal, the team adds, is to give buyers what they need without adding to the complexity of a transaction that is already demanding. "We're trying to provide buyers with credible, data-driven advice without creating additional noise during an already complex transaction."
Maintaining continuity from diligence through integration is one of the biggest challenges in M&A insurance work, according to the team. What gets learned during a deal does not always survive the close.
"Too often, that knowledge is lost at closing," the team said. "The transaction team completes its work, the file is handed off to a traditional service team, and the client is forced to revisit conversations that have already taken place."
The team argues that the most effective advisors treat closing as a transition into the next phase, rather than an endpoint. The post-close team should already know what was found during diligence, what recommendations were made, and what changes need to be put in place. The long-term strategy should also be clear before closing day arrives.
"The portfolio company and sponsor should not have to retell the story of the transaction or re-explain the priorities that were identified during diligence," the team said. "The real test is whether the advisor can carry the knowledge, momentum and objectives of the transaction into the integration phase and beyond."
According to the team, much of the groundwork in M&A insurance due diligence comes down to which documents the advisor receives and when.
"Current policies and complete loss runs are non-negotiable," the team said. They form the foundation of the insurance analysis, and the earlier we receive them, the faster we can understand the risk profile, identify potential issues and provide meaningful guidance."
For businesses with significant contractual or project-based operations, a current certificate of insurance list is also worth requesting before closing, the team notes. It can prevent a substantial amount of post-close remediation work and reduce disruption during the transition.
The document advisors least often receive early enough, the team said, is the most recent renewal application. "Renewal applications often provide insights that policies and loss runs cannot. They show how the company presents itself to carriers, what exposures have been disclosed, how the business has evolved over time and what underwriting narrative has been communicated to the marketplace."
"Those details frequently provide context that helps us understand not just how the company is insured today, but why the program looks the way it does," the team added.