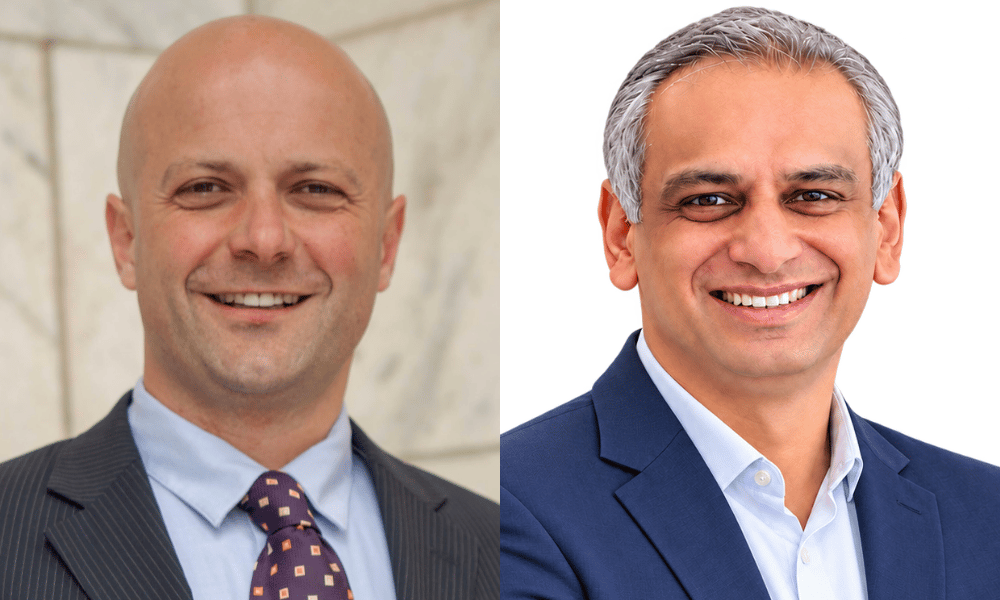
“Sometimes a business deal doesn’t give you what you expect, instead it gives you something you least want.”
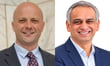
Ilya Filipov (pictured, left), general manager for North America at Cogneesol, is not being dramatic. He and chief operating officer Ashim Khurana (pictured, right) have spent years working with agencies on post-acquisition integration, and the quote above captures, more accurately than most management frameworks, what first-time acquirers discover once a deal closes. The book looked right. The retention rates looked right. The multiples were negotiated hard. And then the operational reality hits.
There were 695 insurance agency deals in the US and Canada in 2025, according to OPTIS Partners. Volume has dipped three years running, but the pace of consolidation remains significant - and the buyers driving it are not all seasoned operators. Many are acquiring for the first or second time, inheriting complexity they did not fully stress-test during due diligence. The ones that get it wrong do not usually fail visibly. They just quietly fail to hit the multiples they negotiated, and spend the next two years working out why.
Filipov and Khurana group the operational issues that surface after close into four categories: people, technology, processes, and carriers. Each is predictable. Each is routinely underestimated. And critically, each one interacts with the others - which is why agencies that think they have contained one problem often find it resurfaces through a different door.
The people problem arrives fastest and hurts most. When a larger agency acquires a smaller shop, it needs the existing staff to stay. Those are the people who know the book, the clients, and the workarounds built up over decades. Lose them and you lose institutional knowledge that no data migration can recover. “They know where the skeletons are hidden,” Filipov said, “and how to fix those.” A producer who leaves takes client relationships with them. An operations manager who walks out takes the tribal knowledge of how that agency actually runs - knowledge that was never written down because it never needed to be.
Read next: How timing determines what M&A insurance due diligence can accomplish
Khurana put the management challenge plainly. Forcing a new operating culture on day one is a losing move. “It’s always easy to come and force yourself and say that from tomorrow onwards start following the way that we’ve been doing it. But you’ve got to give it time.” The change management plan needs to be built before close, not improvised after it. And it needs to reckon honestly with the possibility that the acquired agency does some things better than the acquirer - in client service, in process efficiency, in how producers are managed. The assumption that the larger firm’s way is automatically the right way is one of the more expensive mistakes a buyer can make.
The technology problem is more visible but no less disruptive. Acquiring agencies typically run an established core platform. The acquired agency is often on something smaller and more idiosyncratic. Running parallel systems doubles cost and creates a book of business that is effectively invisible to half the organisation. Having staff manually rekey renewal data from one platform into another is expensive and demoralising - and it creates the conditions for errors that eventually show up as client complaints or worse. Sending the work offshore could add other complexities to the mix. Any agency management system, however capable, accumulates years of legacy data that carries its own complexity. Knowing where the hidden problems tend to live - the data gaps, the non-ACORD fields, the supplemental information that systems quietly discard - is not something most acquiring agencies have mapped in advance, regardless of which platform they are running.
The carrier problem gets the least attention but carries real financial stakes. Carrier codes, contingency compensation structures, and points of contact all shift when ownership changes. If a catastrophe loss strikes while the carrier has not yet been updated on the new ownership structure, contingency calculations go wrong and claims handling gets complicated. “Sometimes the carrier finds after the fact that agency XYZ was acquired by a larger agency and then they have to scramble,” Filipov said. Contingencies do not get calculated correctly. Compensation structures that were negotiated on the basis of one agency’s book suddenly apply to a combined book the carrier did not price for. These are not small numbers.
The fourth issue - process alignment - compounds all three. How a claim gets logged, how a renewal gets chased, how a client communication goes out: none of these things are universal. When staff are already unsettled by an ownership change, discovering that the new parent does everything differently adds friction at exactly the wrong moment. The best processes from both agencies need to be identified and adopted. That takes time and deliberate management. It rarely gets either.
The most underappreciated risk in post-acquisition integration is the errors and omissions exposure that opens up when systems and processes do not align cleanly - and it is almost entirely absent from pre-deal conversations.
The Big “I” released a mergers and acquisitions handbook aimed specifically at helping agencies manage E&O risk during ownership transitions, noting that integration timelines are often compressed and that knowledge gaps among staff translate into errors in policy handling, documentation, and client advice.
Read next: Insurance M&A surge prompts Big “I” to release E&O risk guide
Filipov identified two specific scenarios he sees repeatedly, and both should concern any broker who has been through an acquisition or is planning one. The first is a producer who does not know that a coverage type is available to a client because that client’s data sits on the old system the producer does not regularly access. The client suffers a loss. The coverage existed. Nobody offered it. “Hey, you have access to coverage X and you haven’t offered it to me - how come?” That is an E&O claim with a straightforward plaintiff argument. The second is renewal communications that failed to reach clients on time during the transition. That problem became particularly acute during the hard market, when rate increases needed to be communicated clearly and promptly, and the operational disruption of an integration meant they sometimes were not.
Both scenarios share a common root cause: data that is fragmented across systems and a team that does not have full visibility of the book it is supposed to be servicing. The practical implication for brokers is specific. Before close, map every coverage type held by the acquired agency’s clients against what your producers will actually be able to see on the platform they will be working from on day one. If there is a gap - and there almost always is - that gap needs a manual process to cover it until the data migration is complete. It is not glamorous work, but it is the difference between an integration and an E&O claim.
The issue is not limited to retail agencies. Khurana flagged the MGA space specifically as a context where platform fragmentation runs deepest. MGAs operating across multiple delegated authority relationships, each with its own data, reporting, and bordereaux requirements, carry additional complexity into any integration. Many have not moved to a single platform even when the operational case for doing so is clear - because migration competes with the demands of running the book. That fragmentation does not disappear when ownership changes. It transfers, in full, to the new owner - along with every carrier relationship that sits on top of it.
Most acquirers come to due diligence focused on book value, client retention rates, and revenue multiples. Filipov and Khurana argue that the operational picture deserves equal scrutiny - and that the right questions go considerably deeper than most buyers ask.
Do not just ask what system the agency is on. Ask what the data structure actually looks like, field by field, and where the gaps are. A book that has been managed on the same system for 30 years has accumulated 30 years of inconsistencies, missing fields, and workarounds. Some of those will be cosmetic. Some will break your migration. Find out which is which before you sign, not after. Ask who built the system configuration and whether that person is still at the agency. Ask where process documentation lives - and if the answer is “in people’s heads,” treat that as a material risk, because it is.
On the people side, go beyond the org chart. Identify the two or three individuals whose departure would genuinely hurt the book, and build retention structures around them specifically before close. A blanket retention bonus applied evenly misses the point. The producer who manages your three largest commercial accounts and the operations manager who knows how the agency’s Epic configuration actually works are not interchangeable with everyone else.
On carriers, audit every relationship before close. Know which codes are in use, what the contingency structures are, and what the notification requirements are for a change of ownership. Build a carrier communication plan that runs in parallel with client communication, not after it.
That last point - client communication - is where many integrations lose ground they never recover. Clients of the acquired agency are not automatically loyal to the new owner. They were loyal to the principal, the producer, and the name above the door. A well-timed, personal communication that explains what is changing, what is not, and who their point of contact will be is not a nicety. It is retention management. Leave it late or delegate it too far down the organisation and you will see it in your next renewal cycle.
The age dynamic shaping this market makes all of this more urgent. According to the Big “I” and Reagan Consulting Best Practices Study, the average age of insurance agency owners and workers has risen to 54.4 years. Many agency owners are selling because retirement has arrived before a succession plan did. The acquiring brokerage inherits not just a book of business but a staff whose loyalties were built around someone who is now gone. As Khurana put it: “What exactly has made this work - that’s the most critical part.”
Filipov noted that the best-prepared acquirers have built dedicated integration task forces - some with five people, some with 20 - whose sole function is to execute the integration plan from the moment a deal closes. They track staff retention, manage client communications, coordinate the technology transition, and monitor whether the acquired book is actually performing to the negotiated multiples. “What’s the single throat to choke if something goes wrong? That better not be the principal.” Mid-sized brokerages doing their first or second deal typically have no equivalent. The principal ends up running the integration alongside everything else, and something gives.
The integration challenge does not begin on the buyer’s side alone, and sellers who have done the groundwork create fundamentally different transactions from those who have not.
An agency with poorly documented processes, inconsistently structured data, and a book sitting on a system the buyer has never encountered is a significantly more expensive and riskier integration. Those costs work against the seller too. They show up in lower valuations, more conditional deal structures, and harder post-close negotiations over earnouts. Buyers who discover operational problems after signing do not absorb the cost quietly - they find other ways to recover it.
The practical preparation for a sale is not complicated, but it takes time that most agency principals underestimate. Start with the data: commission a full audit of your agency management system, identify missing fields and inconsistencies, and begin cleaning them before you go to market. Document your processes in writing - not at a high level, but specifically enough that someone who has never worked in your agency could follow them. Understand your carrier relationships well enough to explain them clearly to a buyer, including every contingency structure and notification requirement. And think hard about which members of staff a buyer will most need to retain, and what it would take to keep them through a transition.
Khurana was direct about what happens when this work is not done: “Garbage in, garbage out.” The agencies that come to market prepared do not just attract better buyers. They close faster, negotiate from a stronger position, and give the acquiring brokerage a realistic chance of delivering on the investment thesis - which ultimately protects the earnout the seller is depending on.
Both executives expect AI to materially change the technology burden of post-acquisition integration. Models capable of entering a legacy agency management system, interpreting inconsistent data structures, normalising them, and populating a modern platform without human intervention are, in Filipov’s view, a matter of when rather than if. When that capability matures, the heaviest and most error-prone part of an integration becomes automatable - and the timelines that currently stretch to months compress accordingly.
But Khurana was quick to identify the limit of that logic - and it brought him back to the problem that sits beneath every acquisition, however cleanly the technology eventually runs. “I don’t want AI to do chess so that I can do my laundries and chores,” he said. “I want AI to do my chores so that I can play chess.”
For brokerages, the implication is straightforward. Technology will eventually handle the data problem. The relationship problem - clients staying because they trust a person, not a platform - is not going anywhere. That is what first-time acquirers tend to discover after the punch lands.