The following article was written in association with Applied Systems.
There is a fraud pattern running through the trucking sector that most agency principals do not know about. That is precisely why it keeps working.
A trucker needs insurance for a specific load. Carriers do not sell daily policies, so they bind a standard policy. The trucker writes a check. The agency binds coverage. The trucker moves the load.
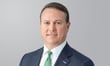
Three days later - inside the standard window for a check to clear - the check comes back as insufficient funds. The trucker has already completed the haul. The insurance was never needed again. And the agency is left holding what Chase Petrey (pictured) calls the MIP: the minimum initial payment the carrier requires upfront and will not refund, regardless of what happens to the premium payment.
"Agencies are losing money on payment fraud all the time within trucking," said Petrey, president of strategic business units at Applied Systems, in an interview at Applied Net 2026 last week. "The trucker will bind a policy, write a bad check, and then they're covered. By the time the check comes back noting insufficient funds, the trucker's already completed their need for the insurance."
The solution is straightforward in principle. Real-time digital payments confirm fund availability immediately, removing the float window the fraud depends on. The harder question is why the move to digital payments in insurance has been so slow - and the answer, Petrey argues, is that most people in the industry have been misreading the problem entirely.
The dominant narrative about slow payment modernization in insurance is that the industry is stuck with an old-fashioned customer base writing paper checks. Petrey's view, after several years running Applied's financial management and payments business, is that this narrative is wrong.
"Almost all of the checks written are not written by a human," he said. "They're written by a financial institution on behalf of the payer, because it's a B2B payment."
The mechanics explain why. Commercial P&C policies - which dominate the agency bill channel where agencies collect premium and remit to carriers - are paid by businesses, not individuals. Businesses run payments through accounts payable staff, logging into their bank to authorize transfers. When the receiving entity does not have an ACH setup, the bank issues a check automatically on the payer's behalf. The human never touches a checkbook.
Applied's average transaction size is $10,000. Multi-million-dollar payments move through the platform hourly.
"It's not a matter of an antiquated customer base," Petrey said. "It's a matter of it being a B2B thing for enormous amounts of money. Paying a $3 million policy is very different than paying for coffee."
That distinction matters for how agencies think about payment modernization. The friction is not on the client side. It is structural, sitting in the B2B payment rails that the banking system runs on - and those rails are not going to shift on the insurance industry's timeline alone.
FedNow - the US Federal Reserve's real-time payment network - is live, and Applied supports it. The obstacle is not the technology. It is adoption.
"Both the payer and the merchant have to be boarded onto FedNow for it to actually work," Petrey said. "Which nobody is. So it's going to take 20 years, unfortunately."
Applied already offers instant settlement to some agencies - but Petrey is direct about what that actually means. The platform fronts its own funds to settle immediately, then waits for ACH to clear over the standard three-day window. It is a risk-float model, the same mechanism Venmo and Square use, not a function of real-time payment infrastructure.
The only scenario Petrey can see accelerating the timeline is a government mandate. He points to India's UPI rollout, where mandated adoption and merchants refusing cash drove near-universal uptake across a vast market. Absent that kind of intervention in the US, he does not see a market-led path that compresses the timeline meaningfully.
"If the federal government said we're not going to clear funds through ACH anymore, you better believe everyone would be on FedNow tomorrow," he said. "But there's nobody forcing it now."
For agencies evaluating vendors who promise frictionless instant payments, Petrey's framing is a useful reality check: the technology to move money faster exists, but the infrastructure that makes it work across all parties does not yet, and a vendor offering instant settlement today is almost certainly floating the funds themselves rather than running on genuinely real-time rails.
Applied's head of fraud is not currently focused on known fraud patterns. He is focused on a category that does not yet have confirmed cases - AI agents sophisticated enough to pass KYC checks.
KYC, or know your customer, is the international regulatory standard for verifying identity when onboarding participants into the financial system. Every procedure currently in use for conducting a KYC check was designed before AI agents existed. The concern is that an agent can now impersonate a real person convincingly enough to pass those checks - and that once inside the financial ecosystem, there are far fewer controls on the other side.
"An agent can really look like a human and can spoof a human very, very well," Petrey said. "If an AI agent can spoof a real person to get into the ecosystem, then it's like, what can they do? And nobody knows."
The reason there is no defense yet is that there is no confirmed pattern to build defenses around. Fraud models are built from observed behavior. A threat that remains hypothetical cannot be adequately modeled.
"It's really hard to defend against a pattern until a pattern is a pattern," Petrey said. "Everyone in the fraud space is scratching their heads trying to put controls around what they can conceive, but it's all hypothetical. There's not enough patterns to have best practices around these things yet."
For agencies handling large commercial premium flows daily, the exposure is not abstract. Fraud liability in the payments ecosystem sits with the merchant - which in the agency context means the agency itself. That is where the gap between KYC procedures built for a pre-AI world and the agents that now exist will be felt most directly, and most expensively, when the pattern eventually materializes.
The accounting and financial management lag that has characterized agency management systems for decades has a structural explanation Petrey traces to how the industry evolved.
When agency management systems were first built, accounting was an afterthought - a byproduct of policy administration rather than a function in its own right. In an era of owner-operated agencies, it was part of someone's job, not a department. The past decade of M&A activity and private equity roll-ups changed that: accounting became one of the largest departments at modern agencies, with demands the original system architecture was never built to serve.
"If I built automations before the industry even needed them, I'd be building into a void," Petrey said. "It's just a natural consequence of the industry maturing - specialization is now required, and there's enough demand that it makes sense to invest."
The technology timing has converged with that demand. The critical shift Petrey describes is AI models gaining the ability to contextualize numbers the way an accountant does - not just performing arithmetic, but understanding what a figure means, whether it matches expectations, and what to investigate when it does not. Large language models were historically poor at computation. The development of what Petrey calls "skills" - discrete tools an LLM can invoke on demand, such as a calculator - means the model can now handle both the computation and the contextualizing that previously required a human.
"The combination of an LLM that can contextualize numbers like an accountant, with the ability to launch a skill like a calculator, is really the result of what an entry-level accountant does," Petrey said. "That's only happened in the past 18 months."
Applied's R&D investment is focused explicitly on insurance accounting - the policy-driven transactions that are tightly coupled to the management system and that general-purpose platforms like Workday or Oracle cannot serve without an AMS underneath them. That is where Petrey sees the highest concentration of staff hours and therefore the largest automation opportunity. The implication for agencies is direct: the reconciliation work that many are currently outsourcing to BPO firms at significant cost is exactly the category that the technology is now capable of handling - and where the case for investment is clearest.