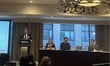
Canada's insurance industry doesn't operate in a vacuum next to the US market, it operates in reaction to it, according to Alan Murray (pictured left), director at AM Best, and Cristian Sieira (pictured right), senior financial analyst at AM Best, speaking at a recent industry briefing. Litigation risk, underwriting appetite, and even corporate ownership are all shaping themselves around the same dividing line: the border itself.
Asked about the growing role of litigation funders in Canada, Murray was direct about where the real volatility sits right now: south of the border.
"Broadly speaking, I'd say our analytic group spends a bit more of our time looking at the US market than the Canadian market in aggregate," Murray said. In the US, major casualty lines have carried a negative outlook for years, driven by aggressive litigation financing, a plaintiffs' bar Murray described as running "a well-oiled machine," and social inflation that has normalized higher punitive damages.
Canada hasn't seen the same deterioration, Murray said, though the reasons aren't fully settled.
Read more: AI-assisted cyberattacks are the biggest wildcard for Canada's life insurers, analyst says
"Our sense in the Canadian market is that this has been a less severe phenomenon here, perhaps for social custom issues, maybe it’s also the nature of the courts and litigation," Murray said. Part of the gap, he added, comes down to a specific US dynamic that hasn't shown up the same way in Canada: the reopening of statutes of limitations tied to historical abuse claims, which has driven a wave of adverse development through insurers' prior-year results in the US.
That distinction matters for how the two markets are being read right now, Murray said. In the US, current-year underwriting decisions are constantly being revised by losses tied to years-old policies, a pattern that hasn't meaningfully shown up on the Canadian side yet. Whether that gap holds, he said, remains something AM Best continues to watch closely rather than assume as a permanent feature of the Canadian market.
That same US/Canada divide is showing up directly in underwriting decisions, according to Sieira, particularly around cross-border trucking and commercial auto exposure. A Canadian-insured vehicle causing a catastrophic loss in the US carries a materially different risk profile than the same accident happening domestically, and insurers have responded by limiting how much of that exposure they're willing to carry.
"We've seen many carriers in Canada limit their risk appetite for cross-border, specifically on the trucking and commercial auto side, where we see the potential for greater losses," Sieira said. Trade tensions and tariffs have reinforced that shift, Sieira said, pushing more Canadian insurers to focus on domestic trucking rather than expanding across the border.
"I don't think it's particularly much of a concern at this point in time, but it's something we continue to monitor," Sieira added.
That caution isn't just defensive positioning, Sieira said. It reflects a broader pattern of Canadian insurers treating the border as a genuine underwriting variable rather than a formality, pricing and limiting exposure specifically because losses that originate on the US side of a Canadian policy behave differently than domestic ones, both in frequency and in severity.
The border logic extends to who owns what, not just what gets underwritten. Asked about US insurers exiting the Canadian market, Sieira pointed to Definity's acquisition of Travelers Canada as a clear example: a US carrier treating its Canadian book as peripheral to a much larger US-focused portfolio, and a Canadian insurer eager to consolidate around it.
"It was more of the fact that they have a large US exposure and the Canadian piece was relatively smaller compared to their broader portfolio, and they just, it looked like an opportunity for a Canadian insurer to dive in and gain market share," Sieira said.
Read more: A major earthquake could take down more than the Port of Vancouver, Swiss Re exec says
That pattern isn't necessarily a sign of trouble in the Canadian market, Sieira said, but more a reflection of where global carriers are choosing to concentrate their attention.
"I think most primarily it's more of a pivot to focusing on core competencies, where these larger carriers are going to invest in some of their Canadian operations, rather than anything structurally wrong with the Canadian market," Sieira said.
That reallocation of capital and attention, Sieira said, is part of a broader wave of consolidation reshaping the Canadian market, one driven less by weakness in any single acquired business and more by how global insurers are choosing to prioritize their operations on either side of the border.