The federal government will indefinitely suspend its plan to extend medical assistance in dying (MAID) to people whose only underlying condition is a mental illness.
The move removes a scenario that Canada's life insurance industry had explicitly left out of its guidance on MAID claims.
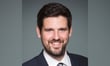
Justice Minister Sean Fraser (pictured) said the government would introduce legislation in the coming weeks to suspend the expansion, which had been due to take effect in March 2027. He cited a lack of consensus in the medical community on who would be eligible.
"While there is not a perfect consensus on this issue, we believe this is the correct approach at this particular time," Fraser said.
The same bill will allow patients with a progressing incurable illness to consent to MAID in advance, before their condition deteriorates to the point where they can no longer give consent. Provinces will decide whether to permit these advance requests. They are not currently allowed under federal law, but are permitted in Quebec for people with serious and incurable illnesses.
A parliamentary committee recommended earlier this year that people whose sole condition is mental illness be excluded indefinitely. A federal court challenge to the earlier delays is still under way, and lawyers for the claimants expect a lengthy legal fight.
Since MAID became legal in 2016, Canada's life insurers have treated it differently from suicide. The Canadian Life and Health Insurance Association's position is that a MAID death carried out under the government's rules and processes is not considered suicide for life insurance purposes.
In practice, that means the standard suicide exclusion, which typically applies during the first two years of a policy, does not apply to a MAID death. Insurers can still contest a claim on the usual grounds, such as material misrepresentation on the application, or a medical condition that was specifically excluded when the policy was issued.
The CLHIA's guidance includes a significant caveat. It states that the position does not cover the government's efforts to extend MAID to people whose sole underlying condition is a mental disorder. It also says the position could be updated once the details of any such expansion are announced.
That question will now remain open for the foreseeable future. If the expansion had gone ahead in 2027, insurers would have had to decide whether mental-illness-only MAID deaths should be treated like other MAID deaths. That is a sensitive issue for underwriting and claims, given the industry's long-standing approach to the suicide exclusion period.
The provision on advance requests is likely to need closer attention from insurers. A person could consent to MAID while healthy enough to do so, potentially years before the procedure takes place. Insurers and advisors may need to consider how that interacts with disclosure on applications and the contestability period, particularly for policies taken out after a diagnosis.
Because each province will decide whether to allow advance requests, the rules could vary across the country. That may complicate claims handling for national carriers.
For life insurance advisors, the immediate effect is continuity. Clients considering MAID under current eligibility rules can continue to expect their claims to be treated in line with the CLHIA's 2016 position, provided the legislated process is followed.
Advisors working with clients who have progressive illnesses should watch the new bill closely, along with any provincial rules on advance requests. Accurate disclosure when applying for coverage remains the main protection against a contested claim, whatever the outcome of the legislation.