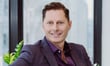
The insurers that backed out of hard-to-place specialty classes five or six years ago are wandering back in as the market softens, and Cameron Copeland (pictured), president and CEO of Specialty Program Group Canada (SPG Canada), says his answer as an MGA leader is to dig in deeper.
Read more: Chasing growth from a shrinking pie: SPG Canada's Copeland on specialty market pressures
Talking to Insurance Business, Copeland said SPG Canada is going further into its core niches and wrapping services around its products, from wildfire protection to towing, because capacity alone no longer sets an MGA apart.
Copeland described the current market pattern as part of the usual cycle. In a soft market, he said, insurers begin writing across more segments than before. In a hard market, capacity tightens and they pull back to core business or more standard lines, leaving transitional business to the subscription market, where MGAs spread risk across several carriers rather than one carrier taking all of it.
He said that transition is visible in D&O, cyber, E&O, construction (including frame construction) and complex casualty, as well as high-hazard classes such as liquor liability, hot roofing, protective services, sprinkler contractors and snow removal. Competitors are returning to those classes, Copeland said.
"We go deeper in those niches. Those are core niches for us," he said.
Copeland said SPG Canada is responding by also layering services onto its products. This year, he noted, it added wildfire defense services for semi-protected and unprotected property, under which service providers carry out physical protection work, such as clearing debris from around a building, when a wildfire threat is imminent.
In boats and motorcycles, the company added towing services and personal property coverage. In construction, he said, inspections now include testing warranties, so that if there is a loss there is no question about whether the insured complied with them. He said that produces a better outcome for clients and brokers.
"It's not just a matter of having capacity or having choice now, but really differentiating on what we bring to the table," Copeland said.
Copeland said the way the market is now structured brings its own risks.
"The insurance market right now is highly consolidated, and that's something we haven't dealt with before," Copeland said. He noted that consolidation is producing hybrid and integrated value chain business models, which can redirect customers away from a basket of market choices and toward in-house products.
Copeland said that isn't limiting innovation at present, because the organizations involved are innovating to meet those needs directly. Over the longer term, he said, less choice for customers could stifle innovation and make it harder for product-focused players to reach customers and show what sets them apart.
Copeland said MGAs face a market where scale now matters, and larger players are emerging. But scale alone isn't enough, he said: brokers still expect MGAs to show up as niche specialists who can solve niche problems. An MGA that does both, he said, has a viable position.
He said the large, consolidated distribution networks that now dominate the market are looking for partners built around trustworthiness, compliance and governance. Those partners need the product range the networks require, he said, along with accountability on both underwriting and claims handling. Players looking to de-risk their operations, Copeland noted, need that combination.
Read more: Under the hood of SPG Canada's consolidation: What it means for broker relationships
"We bring the trustworthiness of a carrier, but we have that DNA and the product shelf of an MGA," Copeland said, talking about his company's approach to this market.
Copeland said pricing is part of SPG Canada's culture. He noted that there is always a band of pricing, and that it is rarely one perfect number. The company's underwriters are experienced in assessing the risk factors that lead to a price and in judging what is adequate, he said, and they are trusted either to put that price out with confidence or to walk away if it is too low.
Many of them have worked through pricing cycles before, he said, and have built up expertise in pricing judgment over that time. That protects the bottom line, he said, while still allowing the company to bring service forward for customers.
Copeland said the shift from a hard market to a soft one is less a matter of learning something new than of returning to what the industry already knows. Anyone who has been through a hard-to-soft cycle change knows what comes next, he said, but the last transition like this was over twenty years ago.
"You've just have to dust off that playbook and rework some old muscles that you haven't worked for a long time," Copeland said.