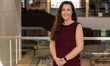
Many Canadians are reducing their home insurance coverage to manage rising costs, widening a protection gap that is already showing up in high-risk areas where some insurers don’t write business, according to Tara Laidman (pictured), vice-president of home and auto insurance at Co-operators.
Homes in areas more exposed to extreme weather are increasingly expensive to insure, and as economic pressures mount, policyholders are cutting back on coverage, Laidman told Insurance Business. The protection gap is the difference between total weather losses and the share of those losses covered by insurance, she said.
Read more: Soft market is squeezing claims firms on fees, ClaimsPro president says
“We feel strongly that we risk a future where insurance will become inaccessible or unaffordable to many Canadians. That is a direct threat to our purpose,” Laidman said.
Catastrophic weather caused more than $2.4 billion in insured losses and an additional $1 billion in uninsured losses nationally in 2025, she said. Severe weather events are becoming more frequent and costly, driving higher claims volumes and larger losses from flooding, wildfire, hail and wind, and repair and rebuilding costs are rising with them.
“There is a direct correlation between the increase in frequency and severity of claims and the rising cost of insurance,” Laidman said.
Climate risk is no longer only an environmental issue but increasingly a financial security issue for households, she said, and research shows many Canadians are not financially prepared for unexpected climate-related losses.
“As a country, we can’t insure our way out of the climate risk issue,” Laidman said. “We need to implement resilience measures to help bend the cost curve.”
The timing of the co-operative and mutual insurance sector’s letter to Ottawa reflects both the rise in severe weather losses and federal policy discussions on housing, infrastructure and affordability, Laidman said. Resilience needs to be built into those decisions now to avoid higher costs later, she said.
Co-operators has spent decades helping Canadians recover from unexpected events, but as severe weather becomes more common and costly, a focus on recovery alone is no longer enough, she said. Insurance helps people recover after disasters, but preventing losses is the most effective and affordable approach, she said.
Laidman said the co-operative and mutual insurance sector wants Ottawa to make climate resilience a national priority by integrating climate risk into housing policy, infrastructure investment, land-use planning and building standards. The sector has made the case in a letter to the federal government that calls for climate-ready homes, retrofits and a streamlined National Building Code with stronger resilience requirements.
All of the measures are interconnected, and meaningful progress cannot come from taking only one or two of them, Laidman said. Of those measures, stronger and more consistently enforced national building standards would have the greatest long-term impact on claims because they reduce risk at the point of construction, she said.
“The most affordable home is the one you don’t have to build twice,” Laidman said.
Retrofits matter as well, she said, because much of Canada’s housing stock is already built. Standards should also reflect regional differences in exposure, with stronger flood protection requirements in flood-prone areas and wildfire-resilient construction in wildfire-exposed regions. Climate-risk mapping should become a routine part of planning and development decisions, in the same way communities already assess transportation and utility needs, she said. She pointed to the Canadian Climate Institute’s Close to Home report, which modelled the financial costs of future floods and wildfires on new housing slated for construction by 2030, as a guide to where homes can be built responsibly.
“Canadians are facing two challenges at once: a housing affordability crisis and an accelerating climate threat. They’re not separate problems; neither are the solutions,” she said.
Read more: AI wants to please you, and that’s a problem for claims, Allianz exec warns
Research from the Canadian Climate Institute has found that rebuilding after damage is usually more expensive than planning for risk in the first place, Laidman said. The Institute also found that each dollar invested in adaptation returns $13 to $15 in direct and indirect benefits, and that $4 billion invested in fortifying aging public infrastructure could save governments up to $8.6 billion a year.
Insurers have a role in educating customers about risk and encouraging preparedness, Laidman said. Co-operators frames resilience in three stages: helping people plan for and prevent risks, absorb and respond when shocks happen, and recover afterward, she said.
“Climate risk should be viewed as a current and growing household financial risk, not a future issue,” Laidman said of the message brokers should give personal lines clients heading into 2027.
Clients should understand their risks, review their coverage regularly and consider measures that reduce the likelihood or severity of future losses, she said.
“The most important message is that resilience pays,” Laidman said.