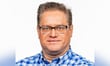
On large, complex property claims that can take years to resolve, insurers say they are broadly willing to make partial or advance payments to help policyholders start recovering sooner, but Brian Rosenbaum (pictured), national claims director at Aon, said the amount of documentation some insurers still require before releasing that money remains a real point of friction.
Rosenbaum raised the issue directly with a group of insurers at a recent symposium hosted by the brokerage, stressing that these insurers are among the most collaborative in the industry, willing to speak directly to clients about insureds' pain points rather than being a source of them. He used a hypothetical scenario to illustrate the kind of claim where the problem shows up most: an entire city block destroyed by wildfire, a loss so large it could take years to fully investigate, even as the building's owners need to start repairs immediately to resume operating their business.
Read more: Outside legal counsel is showing up earlier in claims, and it's straining broker-insurer trust
"It's going to take a tremendous amount of time to fully investigate the loss, particularly the quantum of it, to figure out exactly what's there," Rosenbaum said. "That could take years, but the owners of the building need to restore it as soon as possible to resume business operations."
In a scenario like that, Rosenbaum said, a policyholder is typically facing two connected problems at once: lost income from the disruption itself, and the need to physically repair the property before the business can even reopen. Meanwhile, the insurer's investigation into the full scope of the loss, which it is entitled to conduct thoroughly, can stretch on for months, leaving the policyholder stuck in place with no ability to move forward on either front.
His central question to the group was straightforward, Rosenbaum said: even if an insurer doesn't yet know the full value of a claim, is it willing to release funds against the portion it already knows it will owe? He described the kind of arrangement he had in mind directly to the group, a scenario where an insurer is confident it owes at least $20 million of a $100 million loss, even if the final total won't be confirmed for another six to eight months, and asked whether they would release that known portion right away rather than waiting for the full investigation to conclude.
The response, Rosenbaum said, was unanimous.
"We love interim payments as long as the documentation supports it," Rosenbaum said, relaying the answer he received.
That willingness represents genuine relief for policyholders facing a long, complex claims process, Rosenbaum said, but the caveat attached to it, sufficient documentation, is where the real variation between insurers still shows up in practice. Most insurers he works with are already making these kinds of payments, he said, though not always consistently, and some remain considerably more hesitant than others.
He pointed to a real example of an insurer that handled a wildfire loss in the range of over $20 million by issuing an advance payment of roughly $5 million almost immediately, with minimal supporting evidence required upfront, proof, in his view, that fast, lightly documented interim payments are entirely possible when an insurer chooses to prioritize speed.
Read more: Clients rarely see the full expert report insurers use to decide coverage, Aon claims director says
"They cut a check right away without a lot of evidence, so the insured could deal with a bunch of issues they had to deal with," Rosenbaum said.
The remaining gap, in his assessment, isn't really about willingness anymore so much as calibration: how much documentation is genuinely necessary to justify releasing a clearly defensible portion of a claim, versus how much some insurers still request out of habit or caution rather than actual need. At the same time, Rosenbaum said insureds have to understand that a minimum level of documentation is required to justify the quantum of a claim, and that insureds themselves sometimes fall short on doing the work needed to produce it.
Whether an insurer moves quickly on a partial payment, Rosenbaum said, often comes down to a mix of internal resourcing and the specifics of the claim itself. In the wildfire example, he said, the benefit to the insurer was cementing the relationship with the insured, who was grateful for the fast response, a dynamic he described as a win for both sides. That loyalty, he said, gets rewarded.