What happened: A property owner's negligence lawsuit against her insurance broker has been dismissed by a BC court.
Who's involved: Gold Key Insurance Services Ltd., the broker being sued; The Wawanesa Mutual Insurance Company, dropped from the case in 2024.
What's at stake: The plaintiff sought roughly $70,000 in lost rent and up to $100,000 in reduced sale proceeds.
Why it matters: The case shows how courts weigh a broker's duty of care against a client's own shifting evidence.
Where it stands: Decided - dismissed September 25, 2026, with costs awarded against the plaintiff.
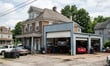
From the street, the burned-out building still looked like somebody's house - which was exactly the problem.
A Coquitlam property owner sued her longtime insurance broker, Gold Key Insurance Services Ltd., in the Supreme Court of British Columbia, arguing it should have switched her rental home from a residential policy to a commercial one once an auto shop moved in. The Wawanesa Mutual Insurance Company, the insurer that had refused to pay the claim, was no longer part of the case either - the plaintiff agreed to drop her claim against it back in 2024.
She and her husband owned several properties around Coquitlam, along with a pizza restaurant nearby. In 2006, their broker at Gold Key added a two-storey rental house to an existing policy, describing it in the application as a "single family rental dwelling." Coverage was written on that basis - roughly $188,500 for the building itself.
Later that year, the property was rezoned for commercial use. The residential tenants stayed on for about six months before an auto repair shop next door expanded into the building. From the outside, nothing looked different.
The house never got a new coat of paint. It never got a new insurance policy, either.
The husband testified he called the broker twice - once when he learned about the rezoning, once after signing the lease with the auto shop - and that the broker congratulated him on the good news the first time. The broker denies either call happened.
That denial might have been a straight credibility contest, except the couple's own accounts kept shifting. At trial, the husband said there were two calls; years earlier, in a sworn statement well before the trial, he'd said there was only one. His wife's version of that first call changed too - the date, whether it came from a landline or a cellphone, even how much later the commercial lease followed it.
The judge liked a simpler explanation better. Switching the policy to commercial coverage meant a higher premium, and a higher commission for the broker - there was no obvious reason for him to sit on that.
The fire hit on March 4, 2014, destroying most of the building. Wawanesa's adjuster wrote to the couple weeks later, saying the policy was void because it had never been told about the change in use, and that it "would have declined to insure the risk" had it known an auto repair shop was operating there. The insurer refunded $11,445 in premiums collected since the estimated date of the change.
Even leaving the broker's conduct aside, the couple still couldn't show they'd actually lost anything - the auto shop was already behind on rent when the fire hit. They pointed to $5,775 a month in lost rent for six to nine months, a range that works out closer to $35,000 to $52,000, well short of the $70,000 figure they'd claimed when the lawsuit began. They also said the fire cost them $90,000 to $100,000 off the sale price of the property, part of a roughly $7 million deal already under contract at the time.
None of it was backed up with paper - no lease, no closing documents, no correspondence about the reduced price. The couple had been asked for this material as far back as 2017, and it never turned up.
The court dismissed the claim on September 25, 2026, and ordered the couple to cover Gold Key's legal costs.
A documented, unbroken paper trail - applications, renewal letters, photos on file - just carried the defendant through, even as the client's own account of what he'd disclosed kept moving.